
Is Advance Auto Parts (AAP) Cheap After Improved Earnings And Lower Full Year Guidance?
Advance Auto Parts (AAP) is back in focus after its latest earnings update, where net income improved despite flat sales, along with a maintained quarterly dividend and a trimmed full year sales outlook.
At a share price of US$45.88, Advance Auto Parts has seen a 1 month share price return of 8.46%, yet the 1 year total shareholder return is down 8.25%. This hints that recent enthusiasm after the earnings, dividend affirmation and lower guidance sits against a much weaker multi year record, and suggests momentum is only tentatively rebuilding. Scan the auto parts space beyond Advance Auto Parts by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) for ideas where earnings updates and dividend decisions could tell a different story.Advance Auto Parts now trades only slightly below the average analyst target and at a deeper discount to some intrinsic value estimates. After that recent bounce, where does a reasonable fair value range actually sit?
Most Popular Narrative: 8% Undervalued
On the analyst consensus Narrative on Simply Wall St, Advance Auto Parts screens as modestly undervalued, with a fair value of $49.95 against the latest $45.88 close, based on a 12.54% discount rate applied to analysts' earnings and margin forecasts.
Advance Auto Parts is still working through a multi year plan to lift adjusted operating margin toward 7%, with recent guidance pointing to further margin expansion in 2027 that, if delivered, would continue to support net margins and earnings.
See why 12 investors see Advance Auto Parts as 8% undervalued.
Result: Fair Value of $49.95 (UNDERVALUED)
Still, that margin focused story for Advance Auto Parts can break if transitory restructuring costs linger or if softer DIY demand continues to weigh on comparable sales.
Find out about the key risks to this Advance Auto Parts narrative.
Another View: What P/E Says About Advance Auto Parts
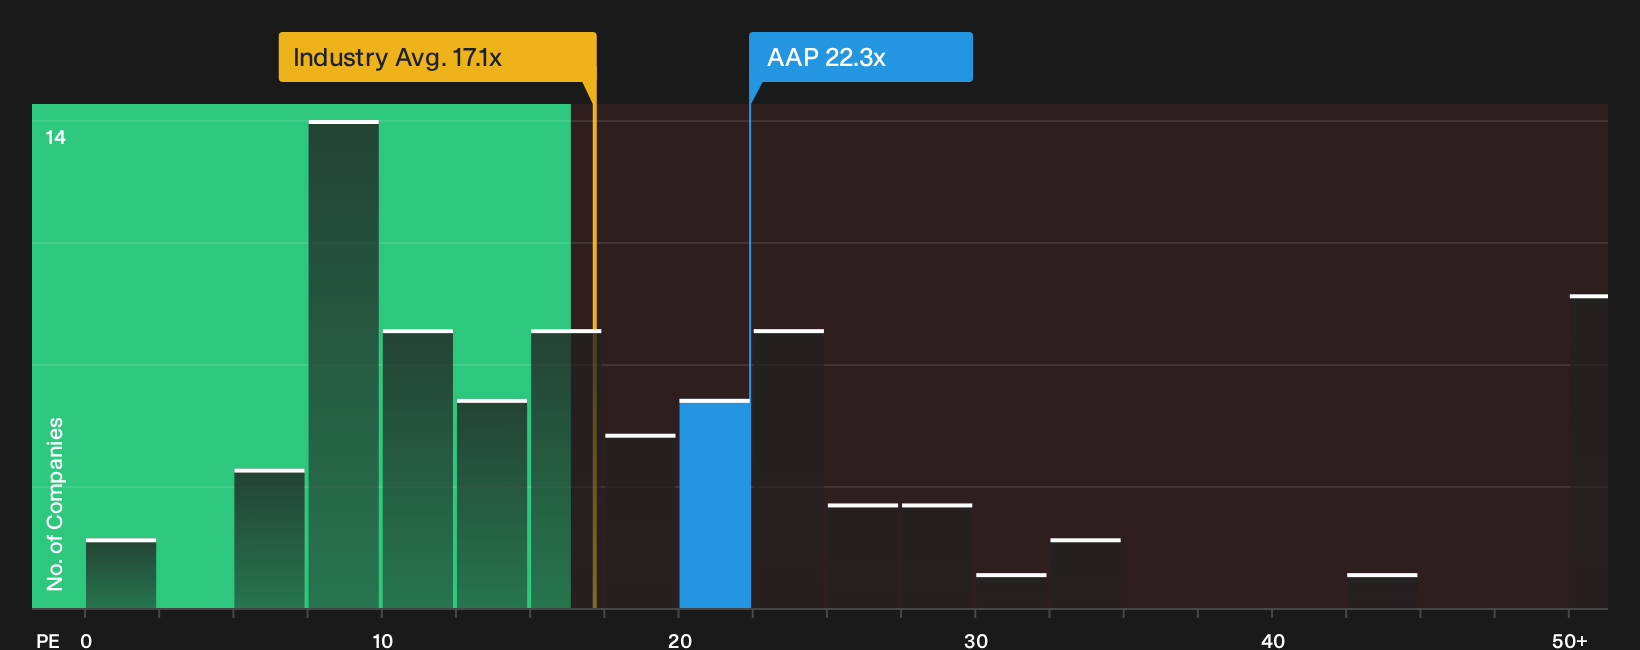
There is a catch. On a simple P/E check, Advance Auto Parts looks expensive at 22.3x earnings versus both the US Specialty Retail industry and direct peers at 17.4x, and above its own fair ratio of 19.2x. This points to less cushion if the turnaround stumbles.
That gap leaves an open question for you: is a richer multiple a reasonable price for the margin story, or a sign to demand a wider discount before feeling comfortable with the risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Advance Auto Parts is split, with both concerns and bright spots on the table. Move quickly and decide where you land by reviewing the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Advance Auto Parts?
If Advance Auto Parts has your attention but you want broader context, use the Simply Wall St screener to spot other opportunities before they move without you.
- Target sturdier balance sheets by reviewing the list of solid balance sheet and fundamentals (24 results) to see companies with financial cushions that may better withstand tougher conditions.
- Hunt for potential mispricings by scanning the 35 high quality undervalued stocks where quality fundamentals and discounted market prices sit side by side.
- Prioritise resilience first by focusing on the 30 resilient stocks with low risk scores to find businesses that score well on stability and risk controls.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com