
Does Raised Earnings Guidance Change The Bull Case For Woodward Stock (WWD)?
- Woodward raised its 2026 earnings per share guidance and reported strong segment margins, supported by solid free cash flow generation and disciplined capacity and automation investments.
- The business now leans more heavily on sustained free cash flow to fund reinvestment, maintain balance sheet resilience, and support potential capital returns, which concentrates execution risk in its long term cash generation.
- We will look at how Woodward's higher 2026 earnings guidance reshapes the longer term investment narrative built around free cash flow.
Compare Woodward's free cash flow story with other businesses on our hand picked list of 35 high quality undervalued stocks that may be pricing in similar long term cash generation narratives.
Woodward Investment Narrative Recap
To own Woodward, investors need to believe its free cash flow engine can stay dependable while heavy aerospace and industrial programs scale. The analyst consensus narrative on Simply Wall St leans on consistent cash conversion to support reinvestment in automation and capacity while keeping leverage contained. The updated 2026 guidance aligns with that view rather than reshaping it, so the headline story does not materially change.
The more immediate swing factor is execution on large aerospace and industrial orders flowing through production and aftermarket. Any slowdown in commercial aerospace service activity or a choppy productivity ramp on new facilities would hit that free cash flow story first. That remains the biggest operational risk in the near term.
The raised 2026 earnings per share guidance is the announcement that ties most directly to this setup. It points to Woodward managing higher segment margins while still funding capacity moves, automation projects and working capital for OEM build rates. For holders, the interest sits in whether those higher earnings translate into equally strong cash generation.
If cost overruns crop up in projects like A350 spoiler capacity or the expanded Glatten fuel injection value stream, the higher guidance could coexist with softer free cash flow. The same applies if aftermarket growth in commercial aerospace cools versus expectations. Those are the pressure points to track against the current valuation and the free cash flow narrative.
Woodward's current narrative connects analyst expectations for US$5.3b of revenue and US$835.5m of earnings by 2029 with an assumed 8.2% yearly revenue growth rate and an earnings increase of about US$283.5m from US$552.0m today.
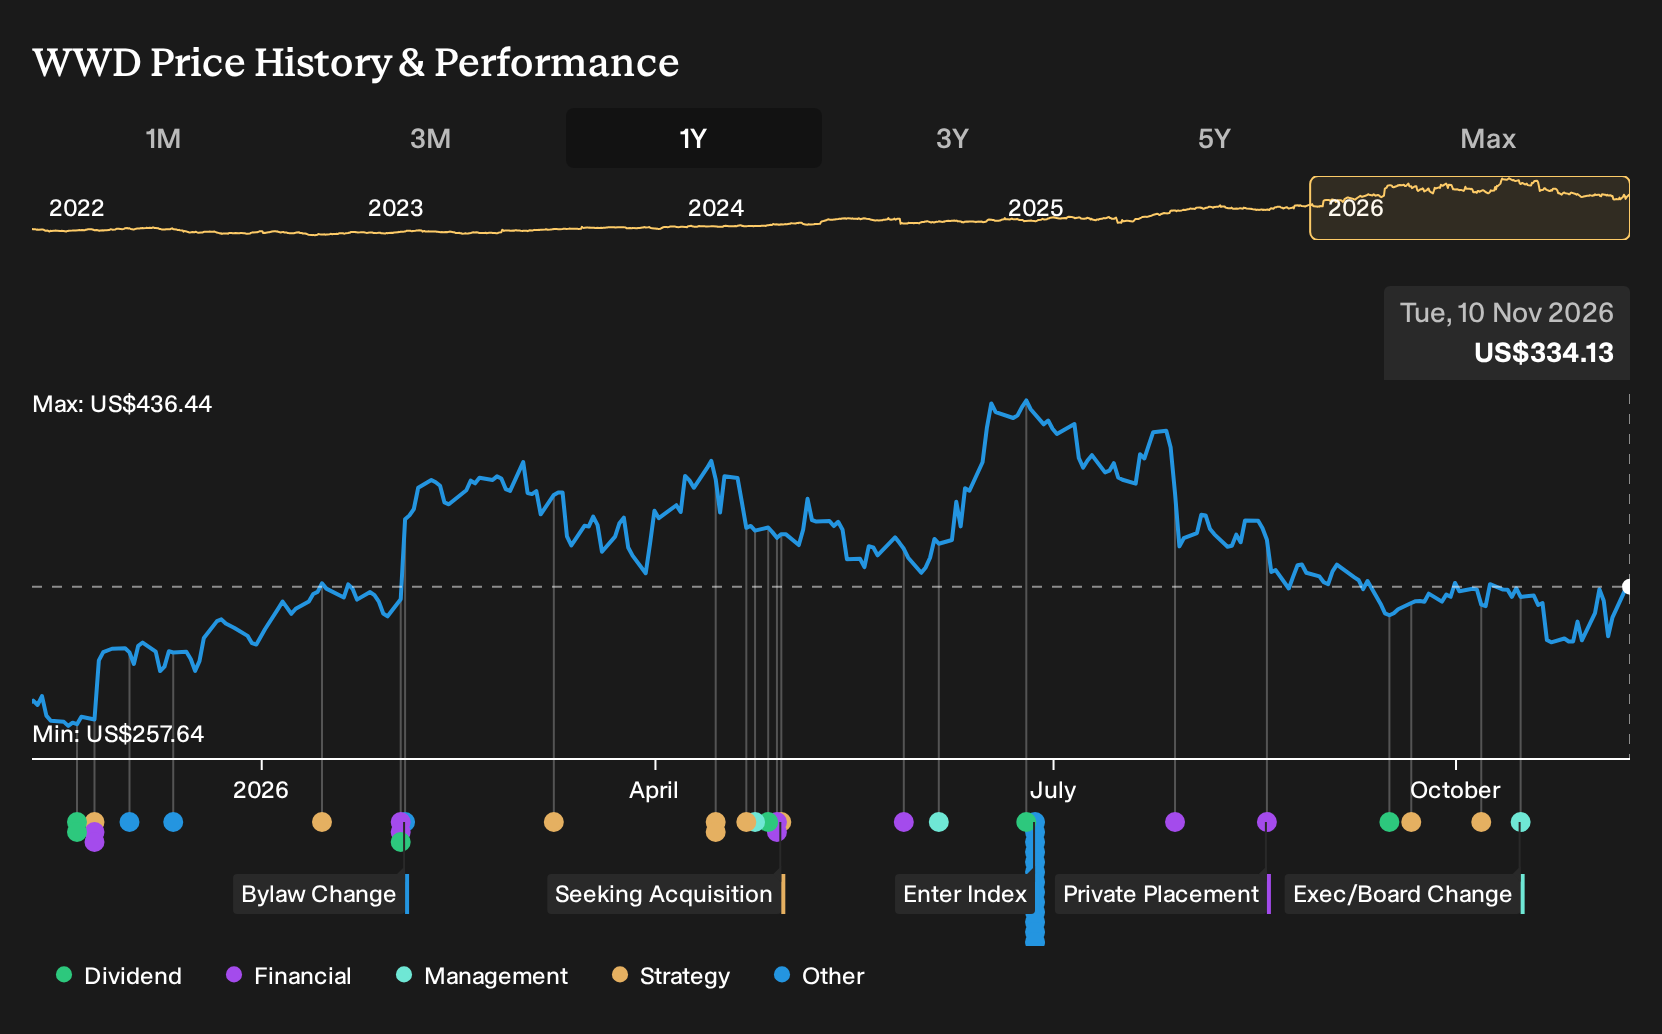
Uncover how Woodward's fair value indicates a 27% potential upside to its current price that could narrow quickly if free cash flow execution improves.
Exploring Other Perspectives
One alternate take on Woodward puts commercial aerospace slowdown risk front and center. The most cautious analysts were penciling in about US$5.4b of revenue and US$826.5m of earnings by 2029 before this guidance news. That is a more reserved cash flow story. Use it as a reminder that forecasts differ widely and may shift again from here.
Explore 4 other Woodward fair value estimates, including one that suggests it could be worth just $337.63.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Woodward research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Woodward. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodward's overall financial health at a glance.
Looking For More Investment Ideas Beyond Woodward?
Once you have a view on Woodward, it helps to compare that thesis with other businesses that fit different return and risk profiles. The Simply Wall St Screener can surface companies with cash generation, balance sheets, and income profiles that line up with what you want from your portfolio.
- If you care most about resilient earnings and capital preservation, focus on companies that show lower risk characteristics through the 30 resilient stocks with low risk scores.
- Income focused investors who want yield backed by fundamentals can use the 5 dividend fortresses to spot higher payout opportunities.
- For those who like finding early stories with strong financial underpinnings, the 20 high quality undiscovered gems can help surface underfollowed businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com