
Earnings Beat Could Change The Case For Novanta Stock
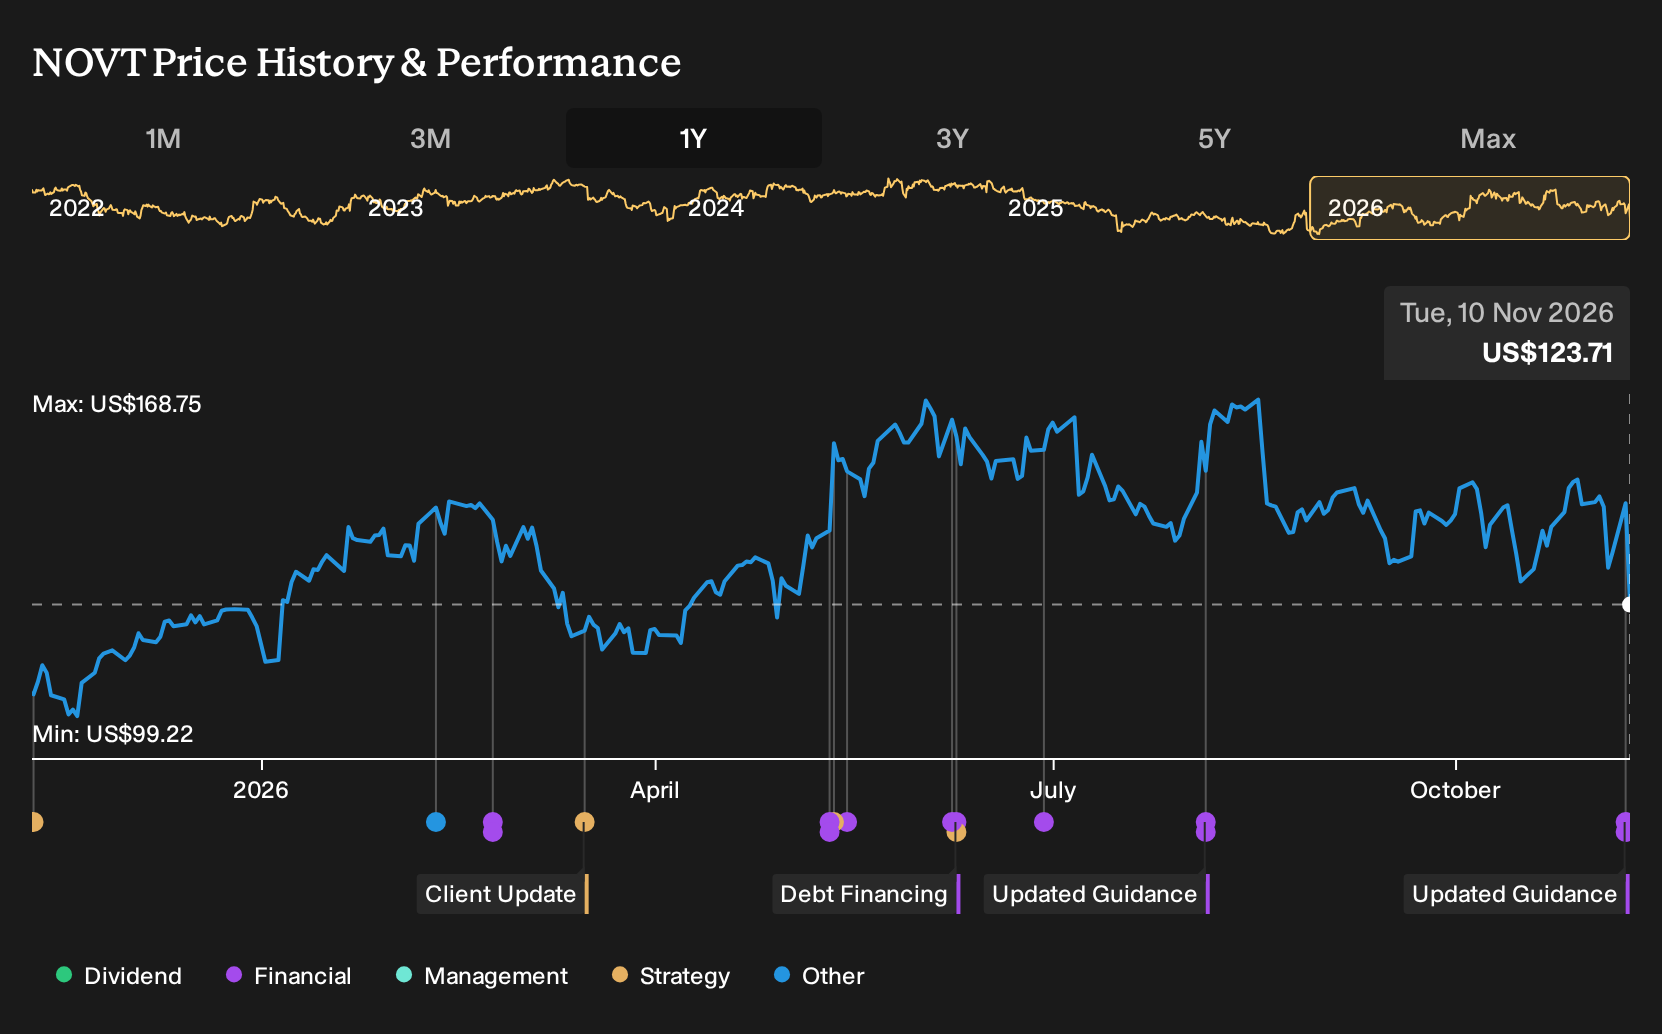
- Novanta reported Q3 2026 revenue of US$305.01 million with GAAP net income of US$2.02 million, while affirming strong adjusted earnings and issuing Q4 and full year 2026 revenue guidance that points to double digit top line growth including Riverpoint Medical contributions.
- The acquisition of Riverpoint Medical, which added about US$33 million of Q3 revenue and increased recurring medical consumables exposure, now sits alongside a manufacturing consolidation program that is reshaping Novanta’s margin and cash flow profile.
- We will now look at how Novanta's earnings beat and raised 2026 revenue outlook could influence the longer term investment narrative.
Scan beyond Novanta’s guidance and earnings beat to spot other potential breakouts in high quality medical and automation suppliers using our curated 20 high quality undiscovered gems list.
Novanta Investment Narrative Recap
For Novanta, the big picture hinges on belief in its medical and automation focus, the higher mix of recurring consumables from Riverpoint Medical, and the manufacturing consolidation program described in the analyst consensus Narrative on Simply Wall St. The near term swing factor is whether this operational reset can translate into cleaner margins after a period of one off costs and lower GAAP earnings.
The main risk today is execution against higher leverage and integration complexity after the US$1.45b Riverpoint deal, especially with Medical Solutions margins already under pressure. Q3’s guidance raise and revenue beat support the top line story, but they do not fully resolve concerns about cash generation, one off items and earnings quality.
The most relevant announcement here is Novanta’s new Q4 and full year 2026 revenue guidance. Management now expects Q4 GAAP revenue of US$306 million to US$312 million and full year GAAP revenue of US$1.135b to US$1.140b. This implies mid teens reported growth and ties directly to the Riverpoint contribution and stronger automation demand.
For you as a shareholder, that outlook keeps the core catalysts on the table, including recurring medical consumables, automation exposure and the manufacturing transformation. At the same time, the updated guide does not change the key watchpoints around leverage, cash coverage of debt and the impact of factory transition and acquisition related costs on reported net income over the next few quarters.
Novanta's narrative projects US$1.7b revenue and US$168.2 million earnings by 2029. This assumes 17.1% yearly revenue growth and requires earnings to increase by about US$106 million from US$61.8 million today.
Uncover why Novanta's fair value indicates a 57% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$80 to almost US$195, which shows just how far apart retail views on Novanta can be. You are weighing upbeat guidance, acquisition driven revenue and margin reset plans against risks from leverage, integration and past share price weakness after good results. Consider exploring those contrasting viewpoints before deciding where you sit.
Explore 2 other Novanta fair value estimates, including one that suggests as much as 35% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Novanta research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Novanta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novanta's overall financial health at a glance.
Looking for more investment ideas beyond Novanta?
Once you have a view on Novanta, it can help to compare it with other opportunities that share similar quality markers but differ on price, income potential or balance sheet strength. The Simply Wall St Screener lets you scan for that next idea without having to build complex filters yourself.
- If you want potential mispricing to be the starting point, check out a curated set of 35 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- If capital protection and steady compounding matter more to you than excitement, focus on our 30 resilient stocks with low risk scores that score well on resilience and financial stability.
- If balance sheet strength is non negotiable in your process, start with the list of solid balance sheet and fundamentals (24 results) and narrow down to businesses that match your thesis and time horizon.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com