
Casella Waste Systems (CWST) Stock Dropped, What Is Behind The Latest Attention?
Casella Waste Systems (CWST) just posted third quarter results that missed earnings and revenue expectations, raised its full year sales outlook slightly, and kept free cash flow targets intact, all under a fresh spotlight from Jana Partners.
The mixed quarter and guidance tweaks have hit sentiment in the short term, with a 1-day share price return of down 6.08% and a 7-day share price return of down 3.36% after Casella Waste Systems reported. Even so, a 30-day share price return of 11.00% and a 1-year total shareholder return of 5.38% suggest recent momentum has picked up from a weaker year to date as investors weigh the earnings miss, updated outlook, and Jana Partners' push on profitability and capital allocation.
Scan how Casella Waste Systems compares on valuation and quality with other potential candidates by reviewing a curated set of 35 high quality undervalued stocks.
Casella Waste Systems now trades near US$93, with analysts clustered around US$107 and one intrinsic value estimate implying a far steeper discount. Is recent weakness pointing to opportunity or signaling a valuation trap ahead of the numbers?
Most Popular Narrative: 12.7% Undervalued
Against a last close near $93, the analyst consensus Narrative on Simply Wall St pins Casella Waste Systems' fair value around $106.50. This frames the pullback as a gap between sentiment and long term cash flow expectations built on measured growth and margin repair under a 7.24% discount rate.
The current valuation and high P/E multiples imply that the share price already reflects strong ongoing growth and improving returns, so any renewed margin pressure or weaker EPS delivery could limit upside and increase the risk of a derating.
See why 3 investors see Casella Waste Systems as 13% undervalued.
Result: Fair Value of $106.50 (UNDERVALUED)
Still, the Casella Waste Systems story can break if acquisition integration drags on margins or if higher diesel and cost inflation continue to squeeze already thin profitability.
Find out about the key risks to this Casella Waste Systems narrative.
Another View: Casella Waste Systems on Sales-Based Valuation
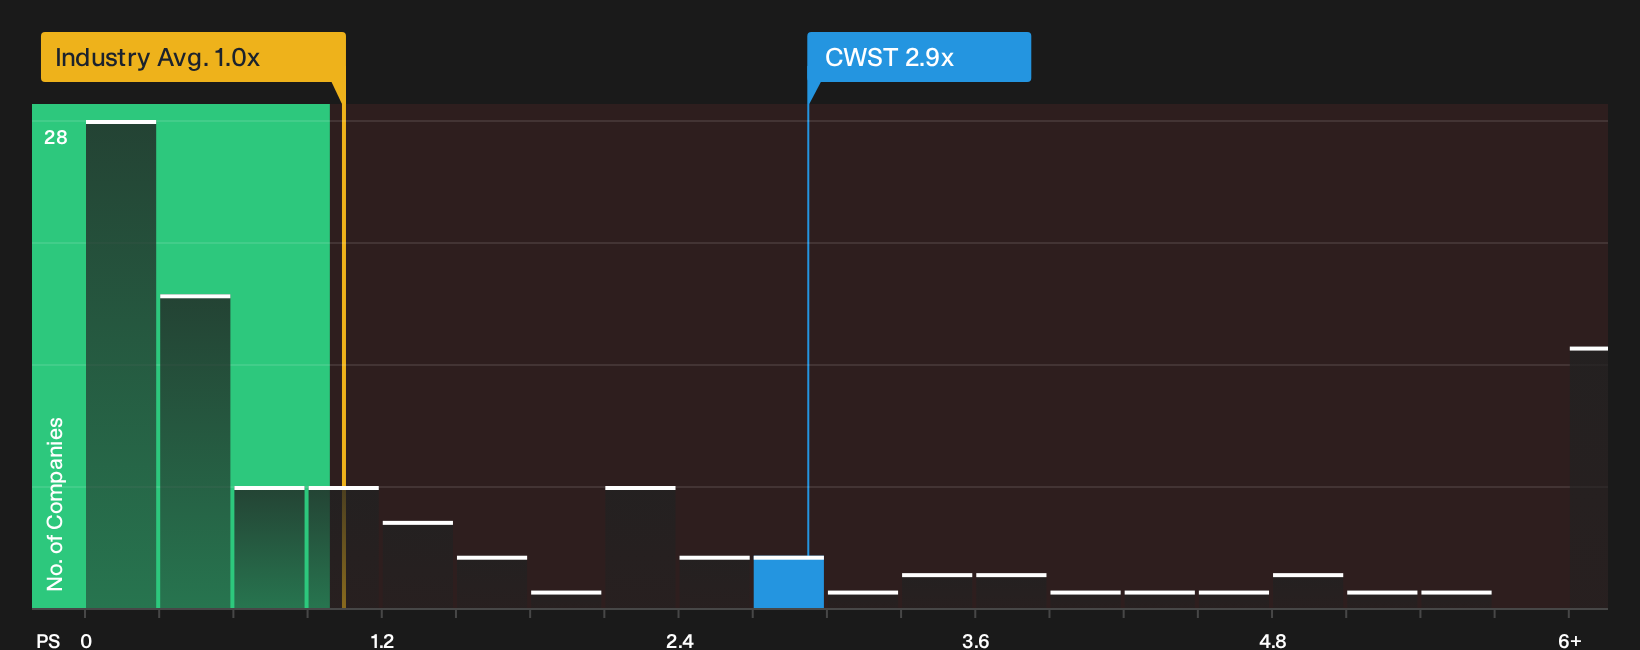
There is a different read on Casella Waste Systems when the focus shifts from discounted cash flows to what investors are paying for each dollar of revenue. On a P/S of 2.9x compared with a fair ratio of 1.6x, the stock also trades above the US Commercial Services average of 1x and a peer average of 2.4x. That gap points to a rich revenue multiple that could either compress or be worked down over time through execution.
To see what the numbers say about this price gap, investors can review the full valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Casella Waste Systems story still feels undecided, consider reviewing the data now and sharpening your own stance with 2 key rewards and 2 important warning signs rather than waiting for a broader consensus to form.
Looking for more ideas beyond Casella Waste Systems?
Do not stop with Casella Waste Systems if you want a stronger watchlist. Fresh opportunities often appear first in the data, not in the headlines.
- Target resilient balance sheets and steadier fundamentals by scanning a list of solid balance sheet and fundamentals (24 results). This can help anchor your portfolio when sentiment swings.
- Hunt for mispriced quality by checking a curated set of 35 high quality undervalued stocks that filters for stronger businesses trading at marked down valuations.
- Stack potential income and staying power together by reviewing a focused list of 5 dividend fortresses that combines higher yields with durability screens.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com