
Caught Out By Bilibili's Fall? Here's What The Bears Saw
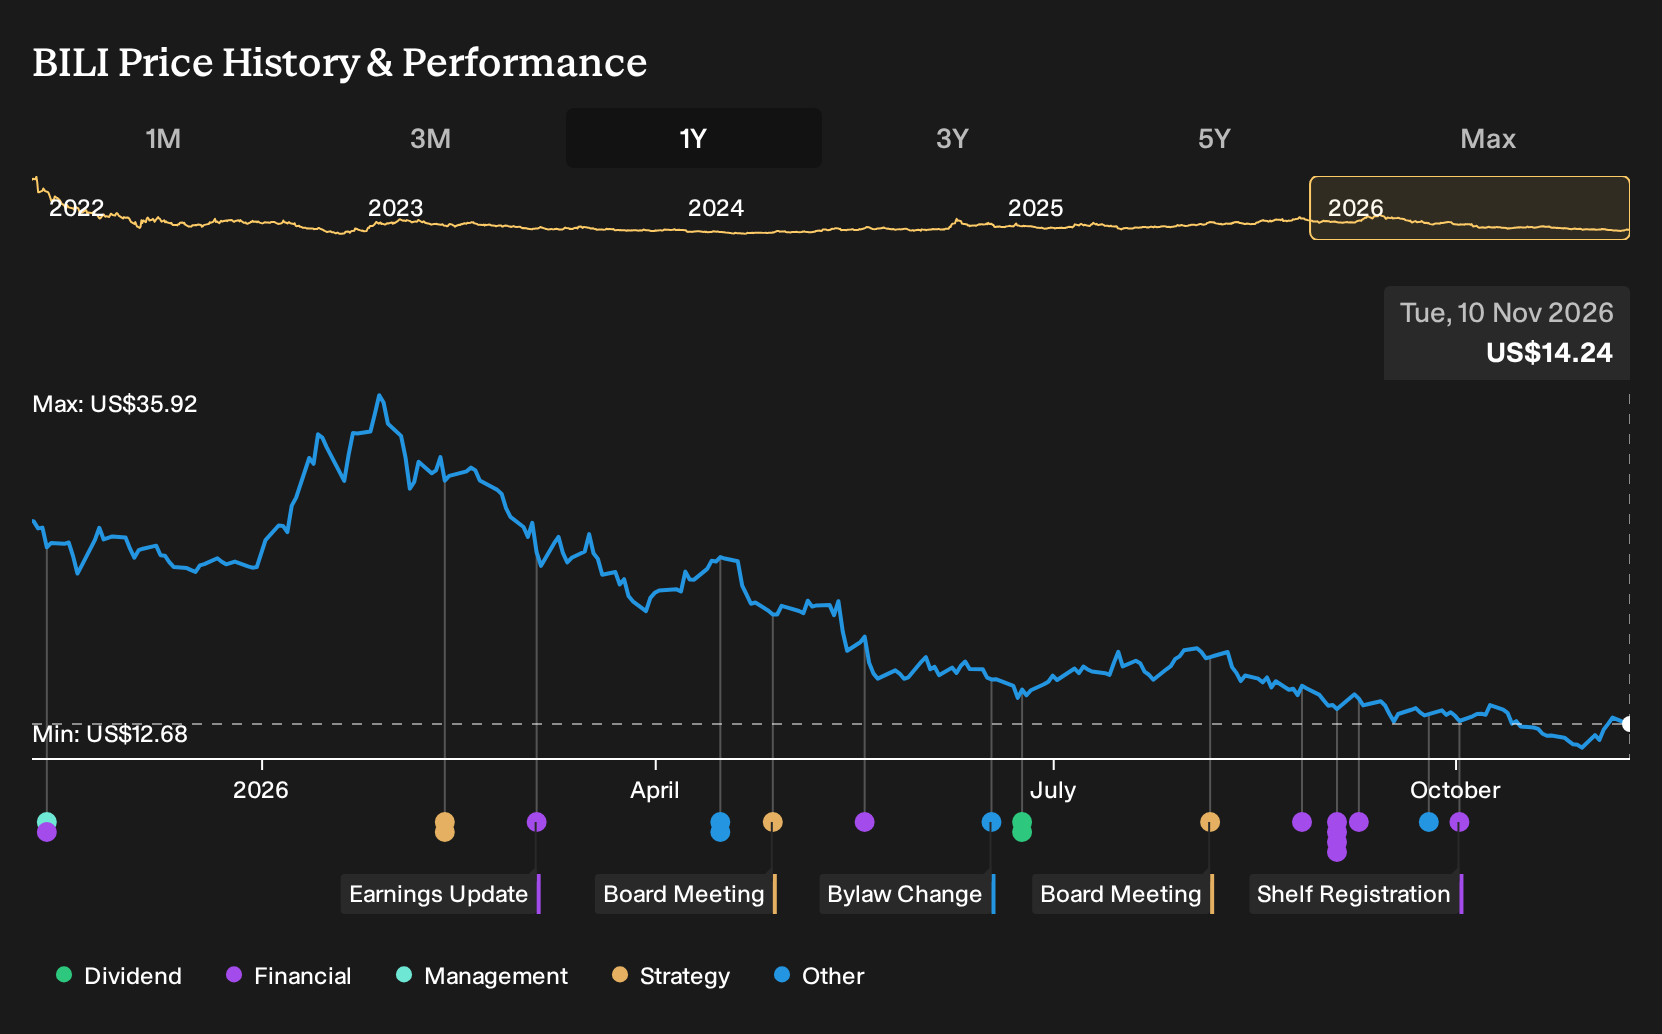
If you backed the Bilibili story that AI-fuelled advertising and gaming would reward patience, the outcome has been painful. For Bilibili shareholders, the loss over the past year was 47.5%, including dividends. If you had bought in expecting rising Gen Z engagement, expanding margins and a higher long term P/E to converge with the bullish scenario, which of those specific assumptions about ad growth, gaming durability or regulatory risk now looks most at odds with what actually happened?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Bilibili has already moved. See which of 35 high quality undervalued stocks still trade below our estimates.
The Argument Bilibili Investors Were Really Weighing
The shares cost US$27.6 at the start of the period, and you had to decide whether Bilibili was a growth engine waiting to be recognised or a maturing platform facing harder limits.
The bullish narrative saw fair value at US$36.98, about 34% above the start price. It hinged on assumptions of AI-driven ad upgrades, durable marquee games such as San Mou, and sustained ARPU expansion from a sticky Gen Z+ base.
The bearish case put fair value at US$19.94, roughly 28% below the start price. It was built on concerns about China’s shrinking youth demographic, tighter regulation on online content, and high ongoing costs for content, servers, and user acquisition.
What The Bilibili Evidence Put Under The Microscope
The biggest surprise was how Bilibili’s AI advertising push lined up with the bullish script. Q2 2026 ad revenue and broader top line both rose, and net income increased from ¥219.0m to ¥343.7m as net margin improved from 3.0% to 4.3%. Gaming stayed softer, so the evidence cut both ways for the original thesis.
The useful checkpoint for the next company you study is simple. If the story hangs on AI-driven monetization, watch ad revenue growth and reported net margin together rather than just user metrics or headline profit.
What Bilibili’s Share Price Drop Now Asks You To Believe
Bilibili trades at US$14.24 today after a steep one year fall, while the bullish analyst Narrative on Simply Wall St places its Fair Value above that level.
The Narrative leans on AI led engagement, advertising breadth and buybacks. A buyer now has to judge whether AI supported monetization can outpace content, traffic and infrastructure costs.
"The main factor that has to go right is that AI enabled engagement and monetization continue to scale faster than content, traffic acquisition, and AI infrastructure spending, so that higher margins and ad mix gains are sustained."
The price and this Narrative do not agree. → Uncover what this Narrative says Bilibili is actually worth
Looking Beyond Bilibili’s Ad Story
Bilibili raises tough questions about where AI advertising budgets ultimately land. One step away, another business may sit closer to that stream.
Rather than tracking a single platform’s engagement, you might follow tools that help many advertisers target users and observe intent.
Another giant concentrates on search, video and cloud services, structured around AI models that interpret queries, rank relevance and serve targeted marketing.
Those capabilities also support enterprise customers that want AI inside their workflows. As budgets align with AI driven campaigns and infrastructure, the impact will likely extend beyond Bilibili’s chart.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 51% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com