
Is Wolfspeed (WOLF) Fairly Valued After Its ESOP Shelf Registration?
Wolfspeed (WOLF) has just filed a US$38.7 million shelf registration for 1,700,000 common shares tied to its employee stock ownership plan, putting fresh attention on how equity compensation could influence shareholder dilution and trading dynamics.
Trading at US$26.23, Wolfspeed has swung sharply this year, with a 7 day share price return of 16.99%, a 30 day share price return that is down 14.31% and a 90 day share price return that is down 17.28%. At the same time, the year to date share price return sits at 38.56% and the 1 year total shareholder return is 50.75%, hinting that recent earnings, guidance and new product and customer announcements are being reassessed after a strong longer run.
Scan beyond Wolfspeed and see which peers show similar volatility and capital raises, using our hand picked 35 high quality undervalued stocks as a starting universe.
After a sharp swing up this week, Wolfspeed now combines a fresh ESOP-related shelf with shrinking revenue and ongoing losses. Once valuation is unpacked, does that balance of dilution risk and turnaround potential still justify buyers stepping in at this price?
Most Popular Narrative: 4.9% Overvalued
The analyst consensus Narrative on Simply Wall St puts Wolfspeed's fair value at $25, which sits slightly below the last close at $26.23. That gap is small, yet it frames a view where execution risk and dilution sit in sharper focus than the recent share price recovery.
Wolfspeed is investing heavily in Gen 5 MOSFETs, 10 kilovolt MOSFETs and 200 millimeter silicon carbide capacity that are still in the early stages of commercial ramp. If customers adopt these products widely across automotive, industrial, data center and aerospace and defense markets, the company could add new revenue streams that support higher earnings and potentially a higher share price.
See why 8 investors see Wolfspeed as 5% overvalued.
In that Narrative, the discount rate of 12.54% reflects a meaningful risk premium for Wolfspeed's capital intensity, new management team and volatile recent trading, even as revenue is forecast to grow 13.68% each year. The fair value of $25 then bakes in the projected 9.25% annual top line expansion and 20.07% long run profit margin that analysts use to justify their $25 consensus price target.
Those same forecasts assume earnings pressure over the next 3 years, with profits expected to decline on average even as revenue rises, which helps explain why the Narrative result sits only modestly below the current share price rather than pointing to a large gap. The new shelf registration, prior shareholder dilution over the past year and reliance on higher risk funding sources all sit alongside that equity story, so investors weighing Wolfspeed at $26.23 are essentially agreeing with a fair value anchor that is only slightly lower.
Result: Fair Value of $25 (OVERVALUED)
Still, the narrative could crack if Wolfspeed fails to lift factory utilization and narrow losses, or if share count growth meaningfully undercuts each investor’s ownership.
Find out about the key risks to this Wolfspeed narrative.
Another View On Wolfspeed’s Valuation
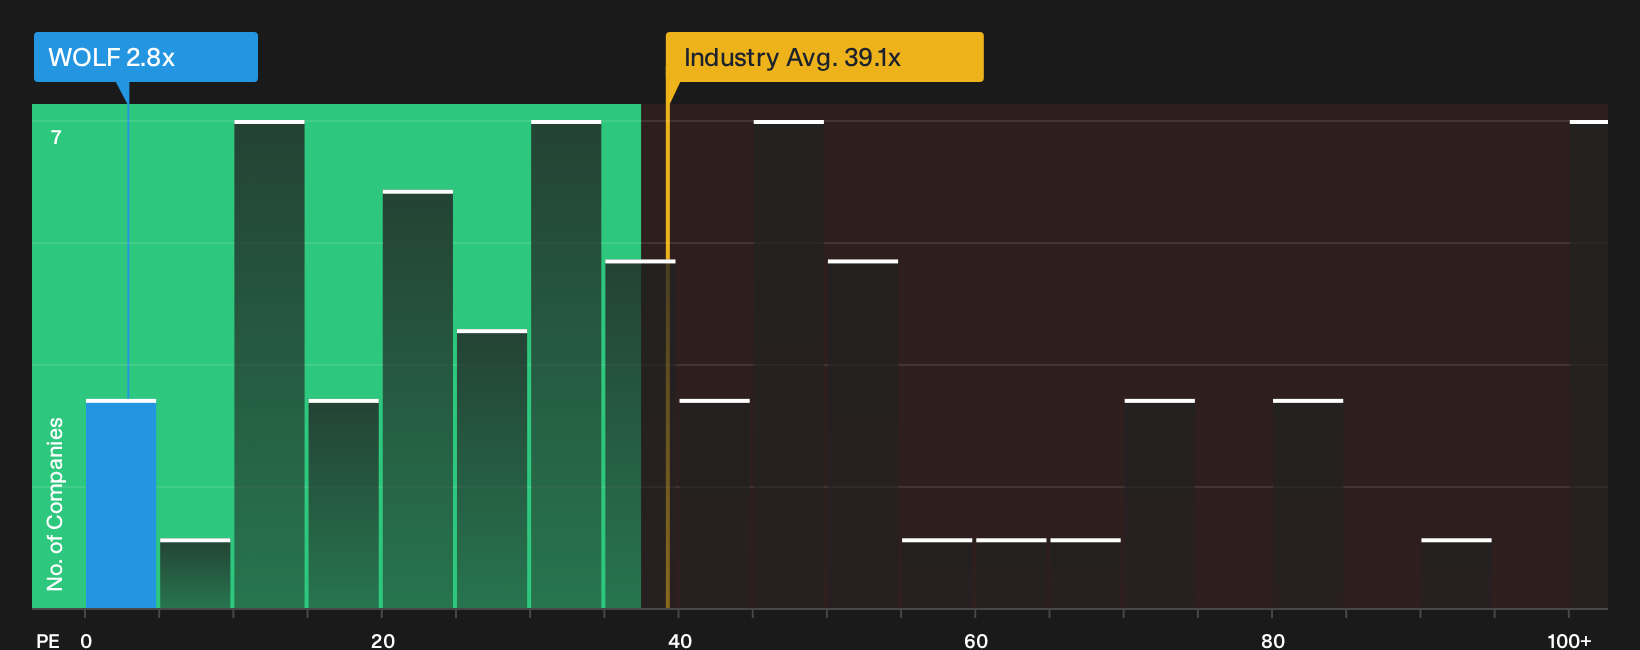
The first take on Wolfspeed leans on analyst targets and long term earnings forecasts. A second lens, the current P/E, tells a very different story. At 2.8x, the multiple is far below the US market at 17.7x and the US Semiconductor group at 38.8x.
The fair ratio for Wolfspeed is 6.3x, which still sits well above today’s 2.8x. That kind of gap can mean investors are pricing in meaningful execution and balance sheet risk rather than paying up for long range growth. The key question is whether that discount is a red flag or a potential opening.
See what the numbers say about this price in our valuation breakdown, then sense check whether they line up with your own expectations for Wolfspeed.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Wolfspeed story pulls in opposite directions. Move quickly beyond the headlines, weigh the trade off between risk and reward, and ground your own stance in the underlying data by checking the 4 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Wolfspeed?
If Wolfspeed has sharpened your focus on risk and reward, do not stop here. Extend that same discipline to a wider watchlist of opportunities using targeted screeners.
- Target resilience by scanning companies with robust finances through a curated list of solid balance sheet and fundamentals (24 results) that keeps weak balance sheets off your shortlist.
- Hunt for mispriced potential using a focused 20 high quality undiscovered gems list before other investors start paying attention to the same tickers.
- Prioritise stability by reviewing a hand picked 30 resilient stocks with low risk scores so your next idea does not rely on constant drama to move the share price.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com