
BrightSpring Health Services (BTSG) Stock May Trade At A Premium As Guidance Was Raised
BrightSpring Health Services has seen its stock surge over the past year, and that move now puts a spotlight on whether the current share price is adequately supported by the company’s earnings power. With the business drawing fresh attention after recent results and guidance commentary, the question for you is how much of that story is already baked into today’s valuation.
- BrightSpring Health Services has delivered a 115.5% return over the past year, which raises the issue of how much of its earnings profile the market may already be pricing in.
- Recent financial updates pointed to faster growth in both pharmacy and provider operations, which can influence expectations for future profitability and the earnings multiple investors are willing to pay.
- There is a second opinion on BrightSpring Health Services worth weighing. See what analysts think BrightSpring Health Services's shares could be worth.
The stock’s next move may depend on whether its current price is in line with what BrightSpring Health Services is earning today and is expected to earn in the years ahead.
If you want to benchmark BrightSpring Health Services against other opportunities where investors are weighing earnings against price, run the same test across the 35 high quality undervalued stocks.
Is BrightSpring Health Services Getting Expensive on Earnings?
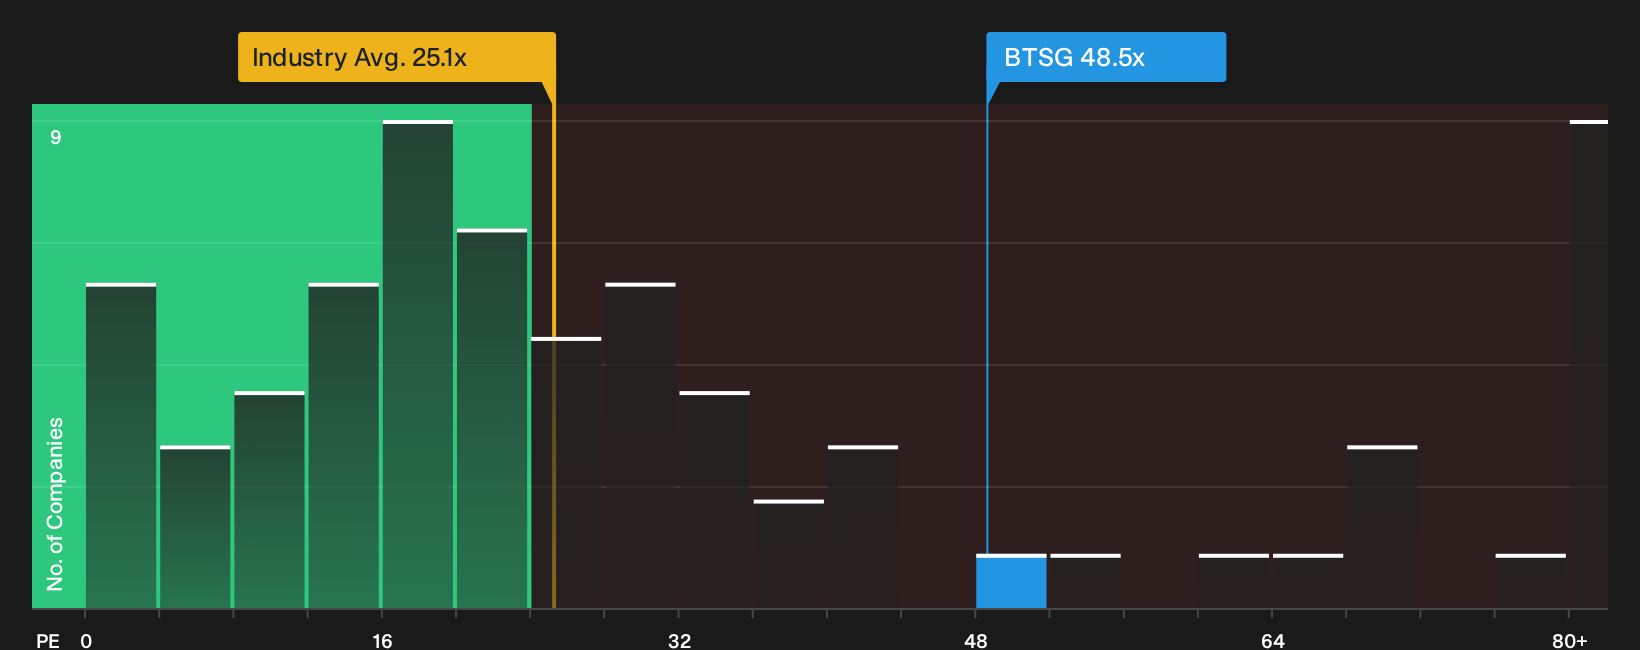
P/E suits BrightSpring Health Services because earnings have become the main reference point for how the market is judging its momentum story. The stock trades on a P/E of 48.5x, which is well above the healthcare sector average of 25.1x and also higher than the 30.8x average across its peers. That signals investors are currently willing to pay a premium multiple for each dollar of profit compared with many other healthcare businesses.
On this framework, the fair P/E implied by BrightSpring Health Services’ growth profile and risk mix comes out lower than where the shares change hands today, which points to the stock screening as overvalued on earnings. Because the Q3 2026 beat and raised guidance sharpened optimism around the story, the elevated P/E suggests a lot of that enthusiasm is already reflected in the price. Explore the numbers behind BrightSpring Health Services's P/E valuation.
The BrightSpring Health Services Narrative: What Would Justify Today's Price?
BrightSpring Health Services' valuation question sets up what Narratives try to spell out in plain terms: the future growth, margin and earnings paths that would need to hold for the stock to be worth meaningfully more or less than the current share price. These sit on Simply Wall St's Community page. Each one treats fair value as a thesis about how the business might perform over time so you can see how that view holds up as fresh information comes through.
Bulls see BrightSpring Health Services as a durable pharmacy led growth story, while bears think recent progress already looks well reflected in the valuation.
Bull case: 11% undervalued
This is based on the analyst consensus Narrative on Simply Wall St, which aggregates multiple forecasts into a single view.
"Ongoing investments in integrated service delivery, technology, procurement, and automation are enabling enhanced operating efficiencies and cross-selling, expected to deliver sustained improvements in net margins and EBITDA…"
Discover why this Narrative puts BrightSpring Health Services at 11% undervalued.
Bear case: roughly fairly valued
According to prajeeshprathap, an investor in the Simply Wall St Community, the recent step up in performance already resets expectations.
"Earnings are no longer being suppressed by restructuring, they are now being driven by scale…"
Explore why this Narrative puts BrightSpring Health Services at roughly fairly valued.
BrightSpring Health Services: Why the share price is only one part of your decision
Before you lean too heavily on valuation alone, it is worth knowing that Simply Wall St’s broader checks on BrightSpring Health Services have flagged specific areas of concern that some investors may want to review more closely. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com