
Gilead Sciences (GILD) Faces A Valuation Test Following Lenacapavir PrEP Data
Gilead Sciences (GILD) is back in focus after PURPOSE 5 data showed higher one year PrEP persistence for twice yearly lenacapavir injections compared with daily oral options, alongside fresh HIV Glasgow 2026 pipeline presentations.
Against this backdrop, Gilead Sciences has attracted fresh attention from investors. The share price is US$170.87, with a 30 day share price return of 13.03% contributing to a 40.52% year to date gain and a 5 year total shareholder return of 205.24%. This suggests that momentum has been building around a mix of pipeline updates, recent trial readouts and ongoing HIV Glasgow 2026 visibility.
Scan how Gilead Sciences compares with other drug developers riding similar clinical and share price momentum by screening for 20 high quality undiscovered gems in this corner of the market.
Gilead Sciences now pairs a high profile HIV pipeline with a share price near all time highs. The next issue for investors is how much of that strength already sits in the valuation.
Most Popular Narrative: 33% Overvalued
Compared with the last close at $170.87, the leading narrative pegs Gilead Sciences at a fair value of $128.38, implying a sizeable premium that investors need to weigh carefully. According to kapirey, an investor in the Simply Wall St Community who wrote the narrative, that gap reflects how the story around HIV, oncology and acquisitions comes together.
Gilead is transitioning from a “single-franchise HIV company” into a multi-platform biopharma with high-probability growth drivers like lenacapavir and Trodelvy. At the same time, temporary earnings headwinds from heavy M&A and pipeline investment can make near-term numbers look weaker than the long-term opportunity suggests.
See why 21 investors see Gilead Sciences as 33% overvalued.
Result: Fair Value of $128.38 (OVERVALUED)
Still, that 33% premium could unwind quickly if oncology assets like Trodelvy underperform expectations, or if fresh M&A adds more near term earnings pressure.
Find out about the key risks to this Gilead Sciences narrative.
Another View On Gilead Sciences' Valuation
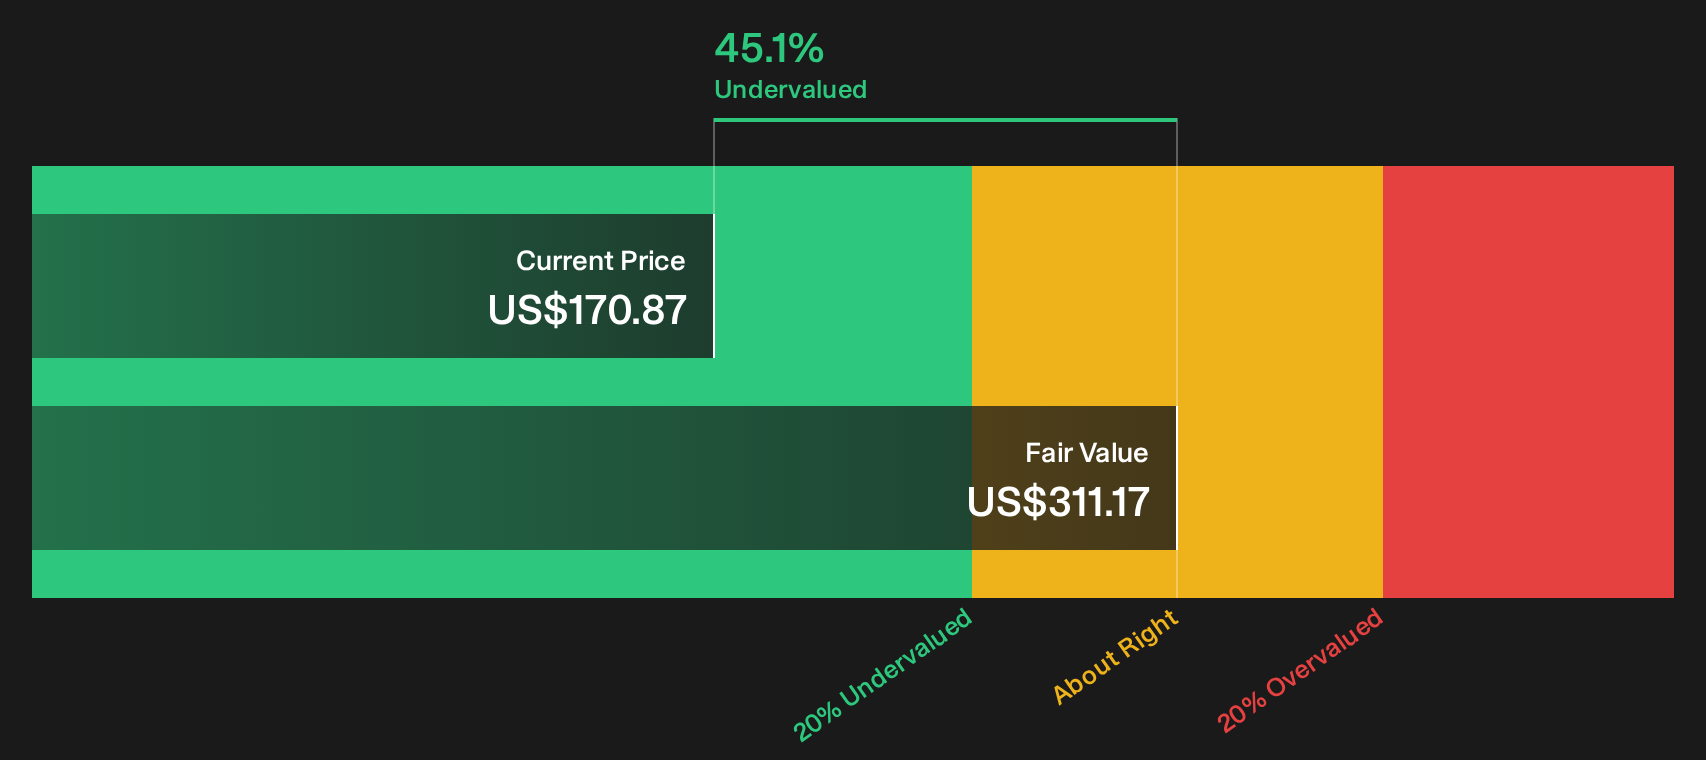
The user narrative flags Gilead Sciences as 33% overvalued at $170.87 versus a fair value of $128.38. Our DCF model lands in a very different place, with an estimated future cash flow value of $311.17. This points to the shares trading at a 45.1% discount. Which story should investors lean on?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split between fair value views feels sharp, treat it as a prompt to move fast and test the assumptions yourself using the underlying data. To see how investors are weighing both caution and optimism, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Gilead Sciences?
Round out your watchlist using the Simply Wall St Screener, so you keep Gilead Sciences in context and do not miss other potential opportunities.
- Target dependable income streams by scanning for generous payers and steady cash flows through the 5 dividend fortresses.
- Zero in on quality at a marked-down price using the 35 high quality undervalued stocks to spot companies with strong fundamentals trading below estimated worth.
- Protect the downside by focusing on resilience first and return second with the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com