
How Investors May Respond To TTM Technologies (TTMI) Strong Q3 Results
- TTM Technologies reported Q3 2026 revenue that was 60% higher than a year earlier, alongside record adjusted EBITDA margins supported by strong AI infrastructure and aerospace and defense demand.
- Management highlighted a record aerospace and defense backlog and pointed to an encouraging preliminary 2027 outlook that signals multi year revenue visibility and earnings potential tied to AI data center and defense programs.
- Next comes a look at how TTM Technologies' record Q3 margins could reshape the existing investment narrative around capital expenditures, debt and AI demand.
Scan how TTM Technologies compares with other beneficiaries of AI data center spending by reviewing a curated list of 53 AI infrastructure stocks in the same supply chain narrative.
TTM Technologies Investment Narrative Recap
To own TTM Technologies, you need to believe the AI data center buildout and aerospace and defense programs can support years of high value orders, while the business absorbs heavy capex and new debt. The recent Q3 report, with 60% year over year revenue growth and record adjusted EBITDA margin, reinforces that operating backdrop rather than changing it.
The main short term swing factor is whether AI infrastructure and defense customers keep translating pipeline into shipments at today’s pace. The biggest risk sits in execution on the large capex and acquisition plan with a more leveraged balance sheet, since any slowdown in demand or cash generation would be felt quickly.
The analyst consensus Narrative on Simply Wall St spends a lot of time on the planned US$1.1b Epiq Solutions acquisition, which is intended to deepen TTM Technologies’ engineered solutions and AI enabled RF offerings. That deal is also a key reason net leverage is expected to move to about 2.3x at closing, which matters more after the share price pullback.
Epiq is tied directly to the same themes that are driving current results, including AI heavy defense and communications programs and a shift toward higher margin RF systems. It also connects to the biggest watchpoints you should track, such as integration quality, the pace of any expected cost benefits and whether higher interest costs and capital intensity leave enough room for future flexibility.
Analysts’ narrative for TTM Technologies points to revenues of US$9.6b and earnings of US$1.4b by 2029. This implies forecast annual revenue growth of 35.9% and an earnings increase of about US$1.1b from US$268.5m today.
Uncover why TTM Technologies' fair value indicates a 157% potential upside to its current price, which could narrow quickly.
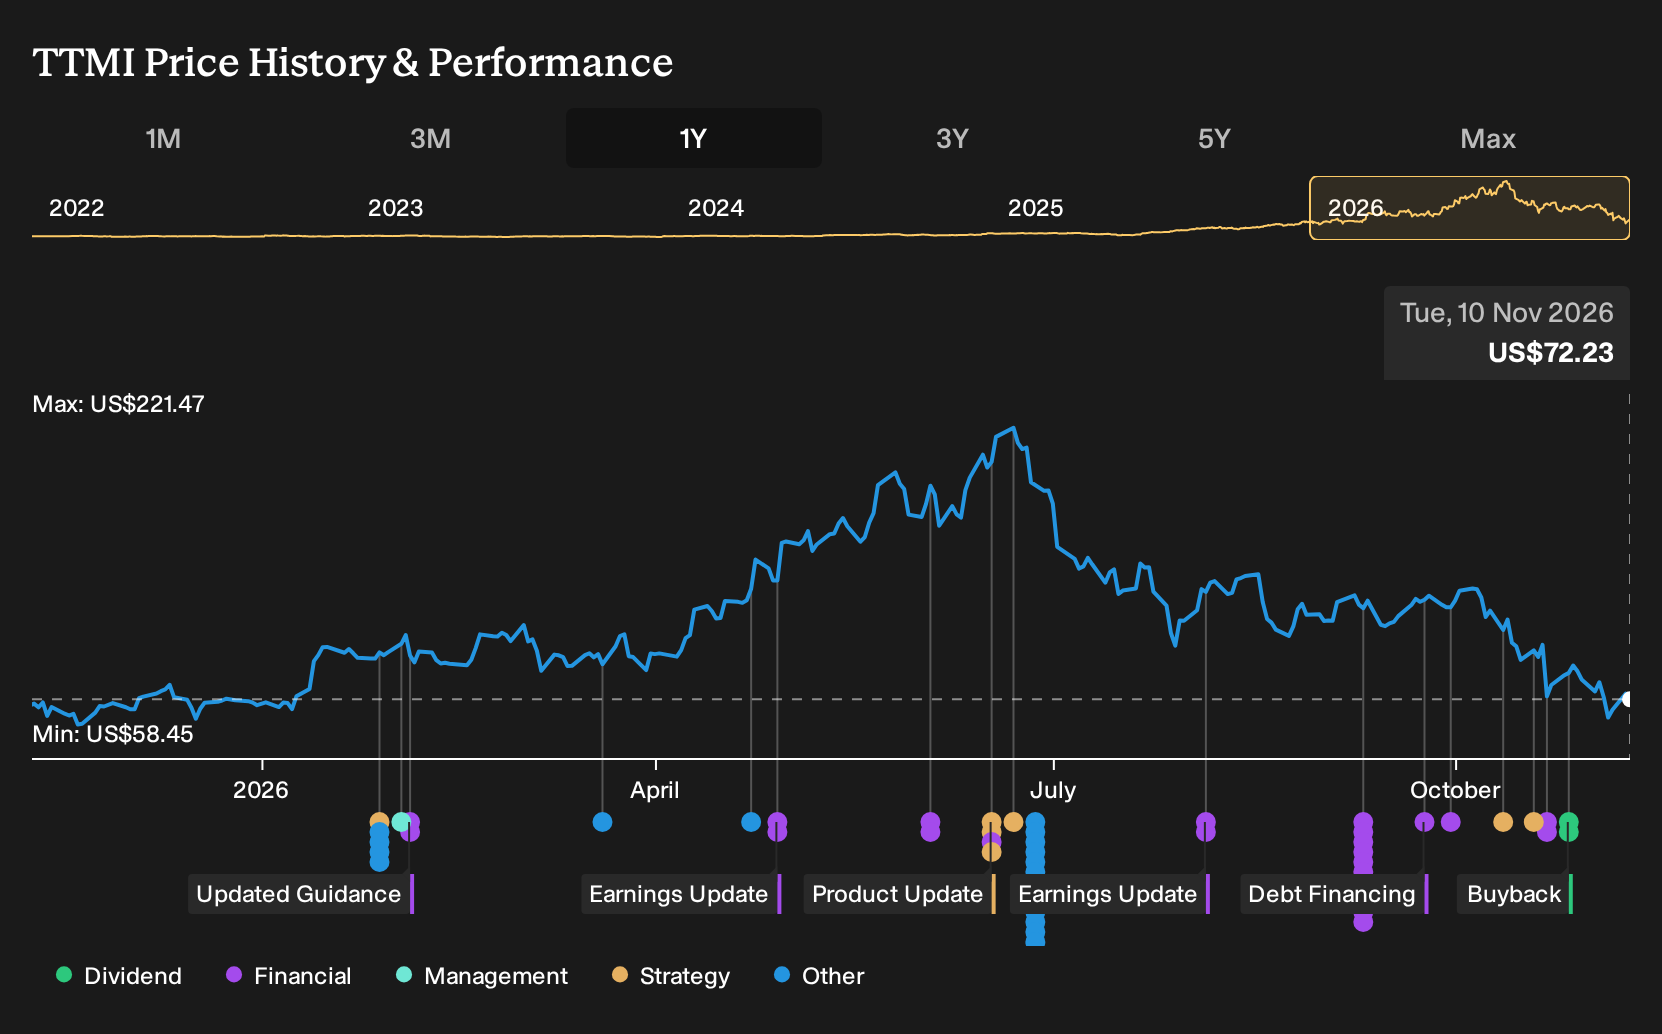
Exploring Other Perspectives
One alternate view on TTM Technologies leans hard into balance sheet risk. The lowest analysts were already assuming slightly softer revenue and earnings by 2029, at about US$9.2b of sales and US$1.3b of profit, and they see higher debt costs as a major concern. After this Q3 surprise, those more cautious narratives may shift.
Explore 4 other TTM Technologies fair value estimates, including one that suggests it could be worth just $150.00!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your TTM Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TTM Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TTM Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond TTM Technologies?
If TTM Technologies has sharpened your view on how AI infrastructure, defense demand and balance sheet choices interact, it can help to test that thinking against a wider watchlist using the Simply Wall St screener tools.
- If you care most about quality at a sensible entry point, start with a group of 35 high quality undervalued stocks that combine stronger fundamentals with more modest pricing.
- If resilience and capital strength sit at the top of your checklist, focus on a list of solid balance sheet and fundamentals (24 results) so you can compare TTM Technologies with peers that also prioritize financial stability.
- If you want ideas the market may be overlooking, widen your search to a pool of 20 high quality undiscovered gems that pair solid metrics with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com