
Spectrum Brands Holdings (SPB) Could Be 11% Undervalued Following Earnings Focus
Upcoming quarterly results for Spectrum Brands Holdings (SPB) are in focus. Wall Street is forecasting earnings of $0.83 per share on revenue of $721.2 million, alongside mixed expectations across its core segments.
Spectrum Brands Holdings shares have climbed over the year, with a year to date share price return of 47.72% and a strong 30 day share price return of 14.63% suggesting momentum has picked up ahead of this earnings release. Total shareholder return of 76.43% over the past 12 months, compared with a modest 24.44% total shareholder return over three years and a slightly negative 5 year total shareholder return, shows how recent gains have reshaped the longer term picture for investors watching the stock at around $88.69.
Compare Spectrum Brands Holdings' recent surge with a curated 35 high quality undervalued stocks that may not yet have this kind of momentum priced in.
This kind of sharp rerating in Spectrum Brands Holdings can mirror real progress in the business or simply reflect investors re-pricing the story ahead of softer earnings. Which explanation does the current valuation lean toward?
Most Popular Narrative: 11.1% Undervalued
The analyst consensus Narrative on Simply Wall St puts fair value for Spectrum Brands Holdings at $99.71, above the last close of $88.69. This frames this recent rally as still short of the narrative fair value anchored on detailed earnings and revenue forecasts.
The separation of the Home & Personal Care segment through the US$127 million Oaktree investment, structured as preferred equity and a term loan that are non recourse to Spectrum Brands Holdings, creates a clearer path toward a focused Global Pet Care and Home & Garden profile that could shift how investors value future revenue and earnings.
See why 3 investors see Spectrum Brands Holdings as 11% undervalued.
Result: Fair Value of $99.71 (UNDERVALUED)
Still, the impairment tied to the Home & Personal Care transaction and softer Home & Garden reorder visibility could quickly challenge the undervaluation story for Spectrum Brands Holdings.
Find out about the key risks to this Spectrum Brands Holdings narrative.
Another View: Spectrum Brands Holdings Through The P/E Lens
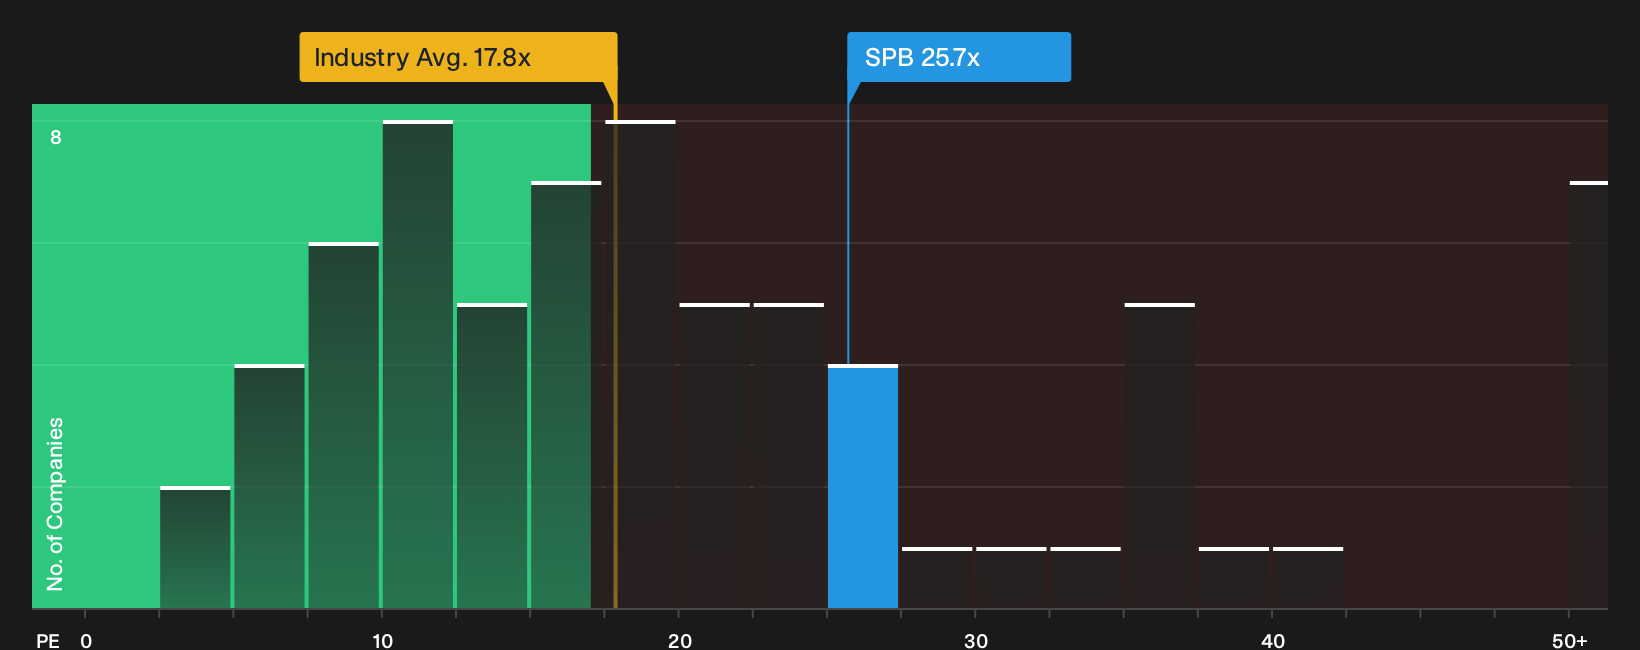
The analyst narrative pegs Spectrum Brands Holdings as 11.1% undervalued, yet the current P/E of 25.7x tells a different story. That multiple sits above the fair ratio of 19.9x, the peer average of 23.8x and the global Household Products group on 17.7x. If earnings or sentiment cool, how comfortable are you with that valuation gap?
For investors who lean on ratio based checks rather than cash flow models, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Spectrum Brands Holdings so far. Act while the debate is fresh and weigh the potential benefits against the red flags by checking the 3 key rewards and 2 important warning signs
Looking for more Spectrum Brands Holdings sized ideas?
If Spectrum Brands Holdings has caught your attention, do not stop here. Your next strong move could sit in a different corner of the market.
- Target higher potential payoffs by scanning a curated pool of speculative opportunities through the 10 elite penny stocks with strong financials.
- Hunt for quality at a discount by reviewing the 20 high quality undiscovered gems that combine solid fundamentals with limited market attention.
- Prioritise sleep at night investing by checking the 30 resilient stocks with low risk scores that focus on resilience alongside return potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com