
Plexus (PLXS) On Strong Results And Guidance Still Looks Undervalued
Plexus (PLXS) just delivered fourth quarter and full year 2026 results, reporting US$1.43b in quarterly sales and higher earnings per share, along with new guidance that outlined management’s expectations for revenue, margins and profitability.
Plexus shares have retreated recently, with the 30 day share price return down 21.9% and the 90 day move lower by 24.6%. This comes even though the year to date share price return is up 34.8% and the 1 year total shareholder return sits at 42.7%, pointing to strong longer term momentum but fading short term enthusiasm as investors reset expectations after the earnings beat, upbeat guidance and ongoing buyback activity.
Scan beyond Plexus and see how other manufacturing and hardware players are reacting to similar earnings surprises and guidance resets with our hand picked list of solid balance sheet and fundamentals (24 results).
Plexus looks like a strong operator on recent numbers and guidance, yet the share price has just been hit hard. So is this a quality business now trading at a sensible valuation or not?
Most Popular Narrative: 33% Undervalued
Against Plexus's last close of $205.18, the analyst consensus Narrative on Simply Wall St pins fair value at $304.60. This implies a sizeable valuation gap and places significant emphasis on execution of a very full order funnel, supported by sector focused expansion plans.
The main factor that has to go right is that Plexus converts its record funnel and new program wins in sectors like aerospace, defense, industrial automation and data center power into sustained revenue growth, while maintaining non-GAAP operating margins above 6% and disciplined cash cycle performance.
Find out how 2 investors see Plexus as 33% undervalued.
Result: Fair Value of $304.60 (UNDERVALUED)
Still, the Plexus story can break if insider selling keeps building pressure on the multiple, or if that US$4.5b funnel converts more slowly than expected.
Find out about the key risks to this Plexus narrative.
Another View: Plexus Through The P/E Lens
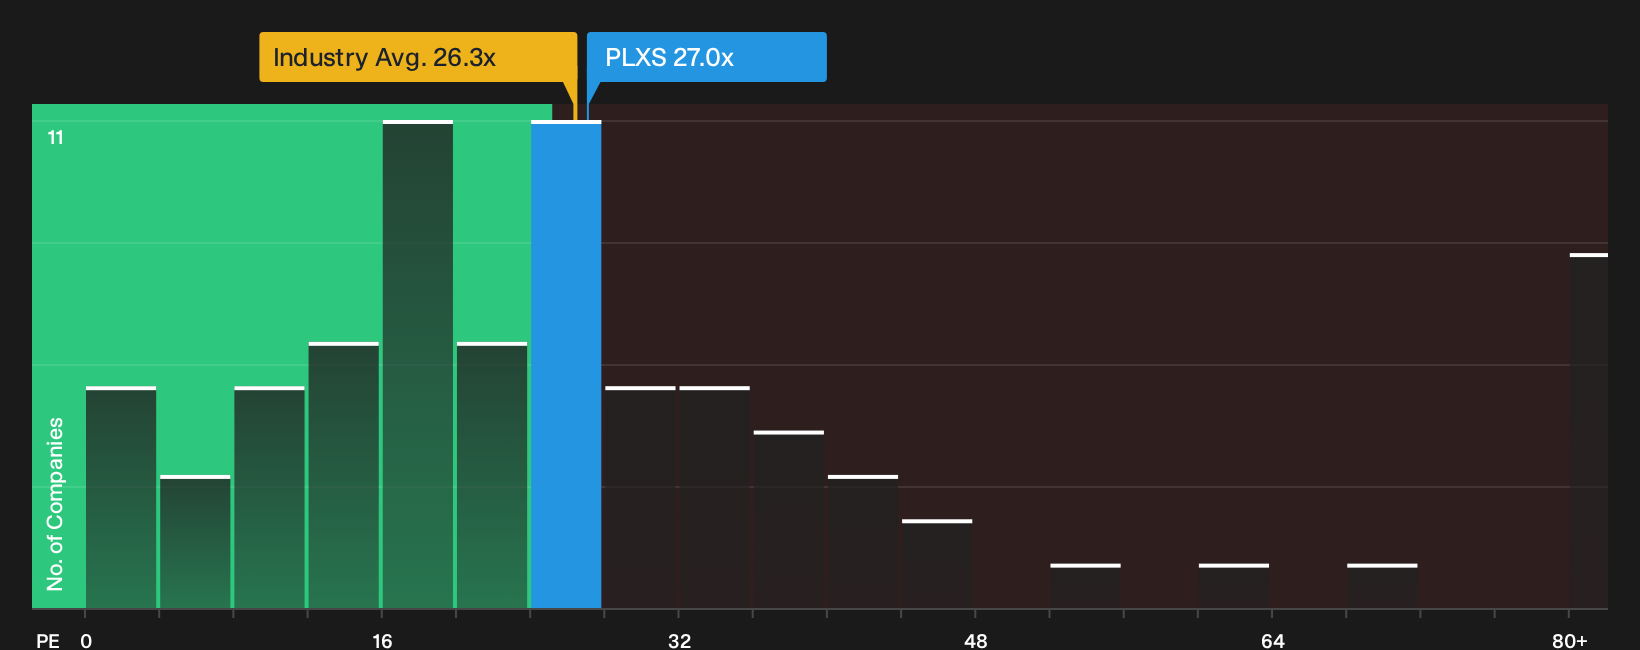
The DCF work suggests Plexus is trading at about a 20.6% discount to an estimated future cash flow value of $258.30, which reinforces the idea of undervaluation. On a simple P/E of 27x, the stock looks only slightly more expensive than the US Electronic sector at 26.4x and roughly in line with a fair ratio of 27.1x. The bigger swing factor may be how long the market is willing to pay up for the growth story.
That raises a practical question for any holder. Is the better guide the modeled cash flows or the earnings multiple that peers trade on See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Plexus setup feels promising on paper, move quickly to stress test the numbers and decide where you stand by checking the 4 key rewards.
Looking for more investment ideas beyond Plexus?
Do not stop with Plexus. Use a few targeted stock lists to pressure test your thinking and line up a stronger watchlist before the next wave of results hits.
- Target steady compounding potential by focusing on resilient balance sheets and healthy fundamentals through this curated list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality by scanning a concentrated set of companies that screen as attractively valued using the 35 high quality undervalued stocks.
- Build a sturdier income stream by zeroing in on payout heavy businesses that clear our yield and stability filters with the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com