
What Monro Investors Missed Before The Fall
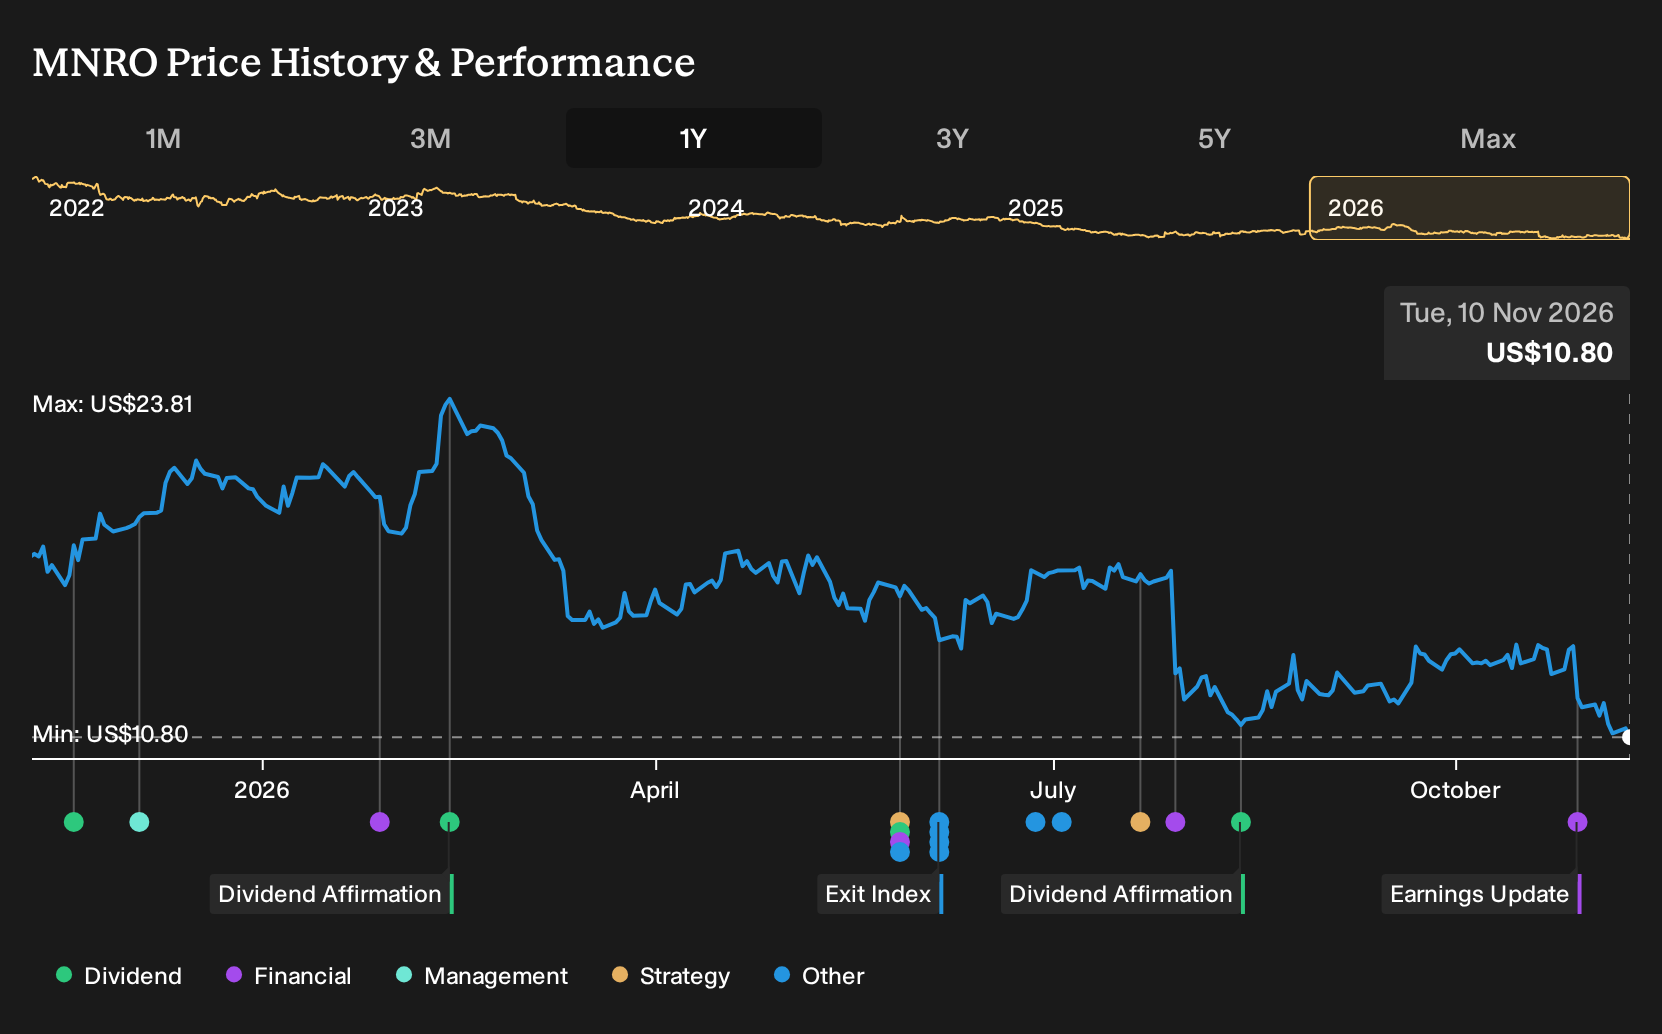
If you only skimmed upbeat analyst debates about Monro before Q2 2027, the subsequent outcome would probably have come as a shock. For Monro shareholders, the loss over the past year was 34.9%, including dividends. Both bullish and cautious views were on record at the start, each leaning on the same themes of aging vehicles, digital inspections, and store closures. If you had been weighing those arguments back in November 2025, which warning signs would have mattered most?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Monro. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Two Monro Stories Investors Had To Weigh
The shares cost US$17.85 at the start of the period, and Monro sat between two very different but reasonable stories about where the business might head next.
The bullish narrative saw fair value at US$19, or 6% above the start price, assuming revenue growth of 2.4% a year and profit margins rising to 7.3% with a future P/E of 8.2x.
The more cautious narrative put fair value at US$16, or 10% below the start price, based on 1.0% annual revenue growth, profit margins reaching 5.0%, and a future P/E of 10.5x while wage and material cost pressure remained a clear risk.
What The Results Changed For The Monro Debate
Quarterly evidence arrived on 29 October 2026 when Monro reported Q2 2027 figures. Revenue was US$283.638m against US$288.914m a year earlier, and a profit of US$5.328m turned into a loss of US$1.611m. Net margin moved from 1.8% to a negative 0.6%. That profitability slip challenged the bullish margin recovery story and leaned toward the cautious case.
The hinge here was the margin assumption. When you test another company, line up the forecast margin path against each new quarter, especially where a positive net margin was central to the upside argument.
What Monro's Lower Price Now Asks You To Believe
Monro now trades at US$10.8, well below where the story began and with this analyst consensus Narrative on Simply Wall St placing its Fair Value above the current share price rather than below it.
The Narrative leans on a reset, with store closures, heavier marketing, and digital inspections all needing to translate into healthier sales per outlet and better profitability. For the fall to look like an opportunity rather than a warning, a buyer today would need confidence that this playbook really lifts traffic, mix and earnings power.
"The main factor that has to go right is that Monro converts its higher marketing spend, digital inspection tools, and district manager playbook into better same-store sales and profit per location, despite current mix pressure and softer traffic."
One Narrative disagrees with today's price. → See where this Narrative says Monro should trade
How Could You Get There Earlier?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 33% below our estimate - sells subscription and usage based AI tools running on a shared cloud backbone.
- Company 2 - 38% below our estimate - handles airfreight and customs for AI hardware shipments and complex compliance requirements.
- Company 3 - 15% below our estimate - ships security appliances using custom chips to reduce customers' network protection costs.
That is three of the list. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com