
Keyera (TSX:KEY) Faces A Valuation Test Following Mixed Q3 Results
Keyera (TSX:KEY) just released a mixed update, reporting Q3 2026 revenue that was higher than a year ago but a shift from profit to loss, while still affirming its fourth quarter dividend payout.
Keyera’s share price has eased in recent months, with a 30 day share price return of down 5.96% and a 90 day move of down 12%, even as the latest earnings update, dividend affirmation and Plains asset integration keep the story in focus. At the current CA$51.26 share price, the longer lens still looks stronger. A 1 year total shareholder return of 27.85% and a 5 year total shareholder return of 120.66% point to momentum that has cooled near term rather than a trend that has reversed.
Scan beyond Keyera and line up other midstream and infrastructure style plays that match this blend of income, volatility and balance sheet strength using our hand picked 9 resilient stocks with low risk scores
Keyera has recently shifted from profit to loss, and the share price has cooled following a strong multi year run. Is most of the gain already behind you, or does the current price still leave room on the table?
Most Popular Narrative: 20% Undervalued
At a CA$51.26 share price versus a narrative fair value of CA$64, the analyst consensus Narrative on Simply Wall St frames Keyera as trading at a meaningful discount and ties that gap directly to execution on its NGL network and growth projects.
The acquisition of Plains’ Canadian NGL business and the remaining share of KAPS has created a larger, more connected NGL network that is already supporting record realized margins in Gathering and Processing and Liquids Infrastructure in Q2 2026, with further upside as additional contracted volumes and system optimization feed into cash flow and net margins.
See why 30 investors see Keyera as 20% undervalued.
Result: Fair Value of CA$64 (UNDERVALUED)
Still, the Keyera narrative leans heavily on successful Plains integration and higher leverage coming down on schedule. Both of these factors could disappoint if maintenance or regulatory pressures escalate.
Find out about the key risks to this Keyera narrative.
Another View on Keyera’s Valuation
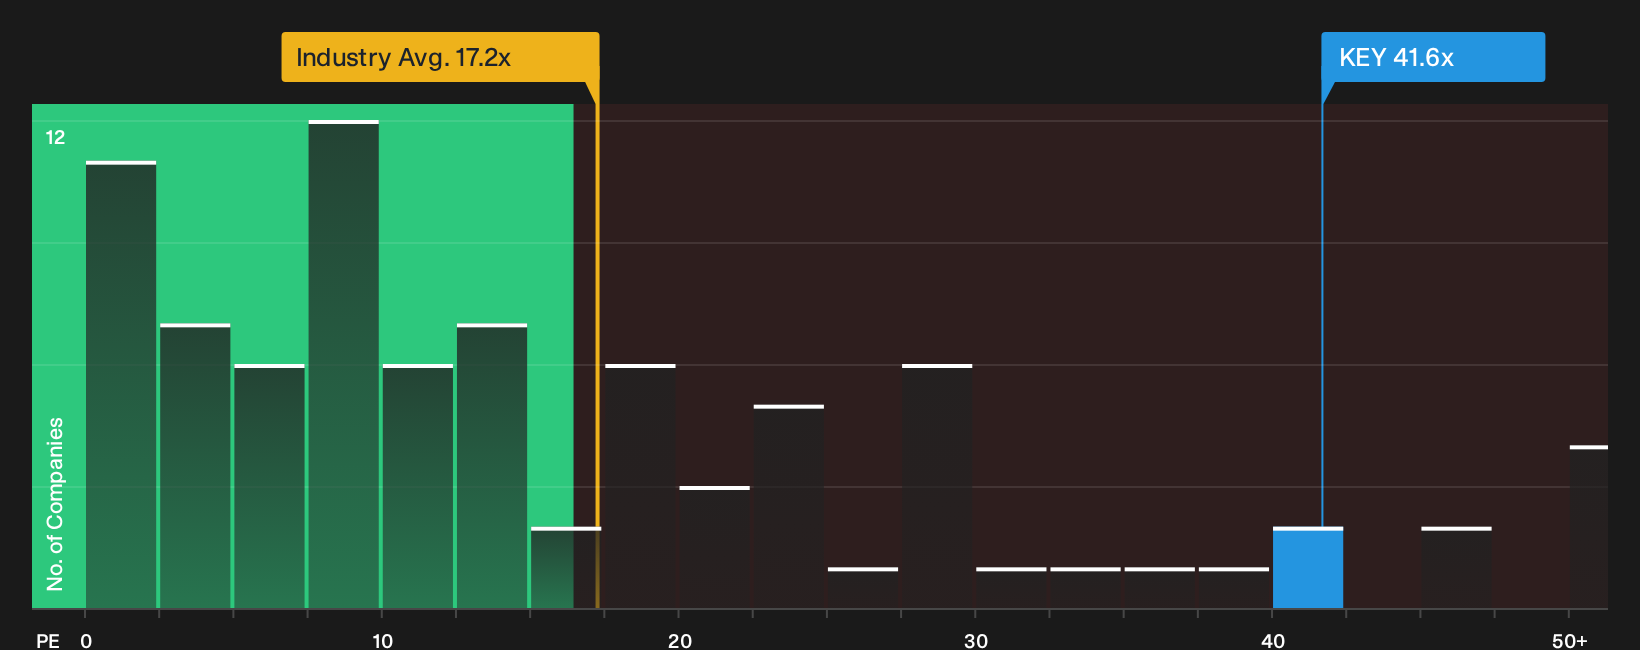
The fair value narrative for Keyera leans on future earnings power, yet today the stock trades on a P/E of 41.6x. That is rich compared with both the Canadian Oil and Gas group at 17.5x and a fair ratio estimate of 25.2x. Is the discount story already priced in, or is the multiple the real risk signal?
See what the numbers say about this price in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Keyera can be confusing, so review the full dataset promptly and pressure test your own thesis against the 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Keyera?
If you want a broader watchlist that fits your style, use the Simply Wall St Screener to surface fresh ideas before they move and sharpen your next decision.
- Target reliable cash generators that combine resilient balance sheets with earnings power by scanning our list of solid balance sheet and fundamentals (5 results).
- Spot potential mispricings where quality and valuation still line up through the focused 7 high quality undiscovered gems.
- Lock in income ideas by filtering companies that offer higher yields and robust fundamentals via the curated 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com