
Canadian Stock Market Today: TSX Futures Edge Lower On Hot US Inflation Data
The Morning Bull - Canadian Market Morning Update Wednesday, 11 Nov 2026
Canadian equities are set for a softer open as investors digest hotter US inflation that points to higher for longer rates. Sentiment leans cautious, with the US data acting as the clear reference point for today’s Canadian market tone.
US October CPI rose 0.4% month on month on the headline measure, with core CPI up 0.3%. Those readings are firm enough to reinforce the risk of a Federal Reserve rate hike in December, which is feeding into a stronger US dollar and cooler risk appetite.
Higher expected US policy rates tend to pull North American bond yields upward, raising borrowing costs for Canadian households and companies. That can pressure interest sensitive areas, while a firmer US dollar often weighs on commodity prices and, by extension, earnings expectations tied to Canadian resource exports.
The open question now is whether upcoming US producer price data backs up this CPI strength or shows some relief. If input costs echo the CPI surprise, the case for a December hike hardens and could challenge any attempt at a rebound in Canadian risk assets.
Stocks to Watch Before the Opening Bell
Altius Minerals (ALS)
Altius Minerals is buying TNR Gold in a court approved deal that values TNR at about $122 million, a 60% premium to its recent trading level. The purchase adds royalties on the Los Azules copper and Mariana lithium projects in Argentina. Recent Q3 figures show $33.3 million in attributable royalty revenue and a fresh $181.5 million equity raise plus a larger $350 million credit facility.
Crombie Real Estate Investment Trust (CRR.UN)
Crombie REIT is leaning into grocery anchored retail. Management reported record committed occupancy of 97.7% and renewal spreads 13.9% above expiring rents, while agreeing to buy 13 Ontario properties for $134 million. New Series O senior unsecured notes worth $175 million, tied to Daily Compounded CORRA plus 0.90%, are earmarked to help fund the deal and refinance existing debt.
CGI (GIB.A)
CGI just posted Q4 and full year numbers that show net earnings up 20.8% and revenue higher by 3.3% year over year. Bookings ran hot with a 109.2% book to bill ratio and a backlog of $32.07b, which indicates a substantial level of contracted work. Management also lifted the quarterly cash dividend by 8.8%, indicating confidence in the current earnings power.
Top Movers
- Pet Valu Holdings (TSX:PET) jumped 7.57% after reporting Q3 revenue and profit growth, and outlining further store expansion.
- Trisura Group (TSX:TSU) gained 4.82% as the market absorbed recent analyst target cuts and rating changes following prior weakness.
- Paramount Resources (TSX:POU) added 3.85% following a Scotiabank price target hike that reflected updated assumptions for the business.

Top Losers
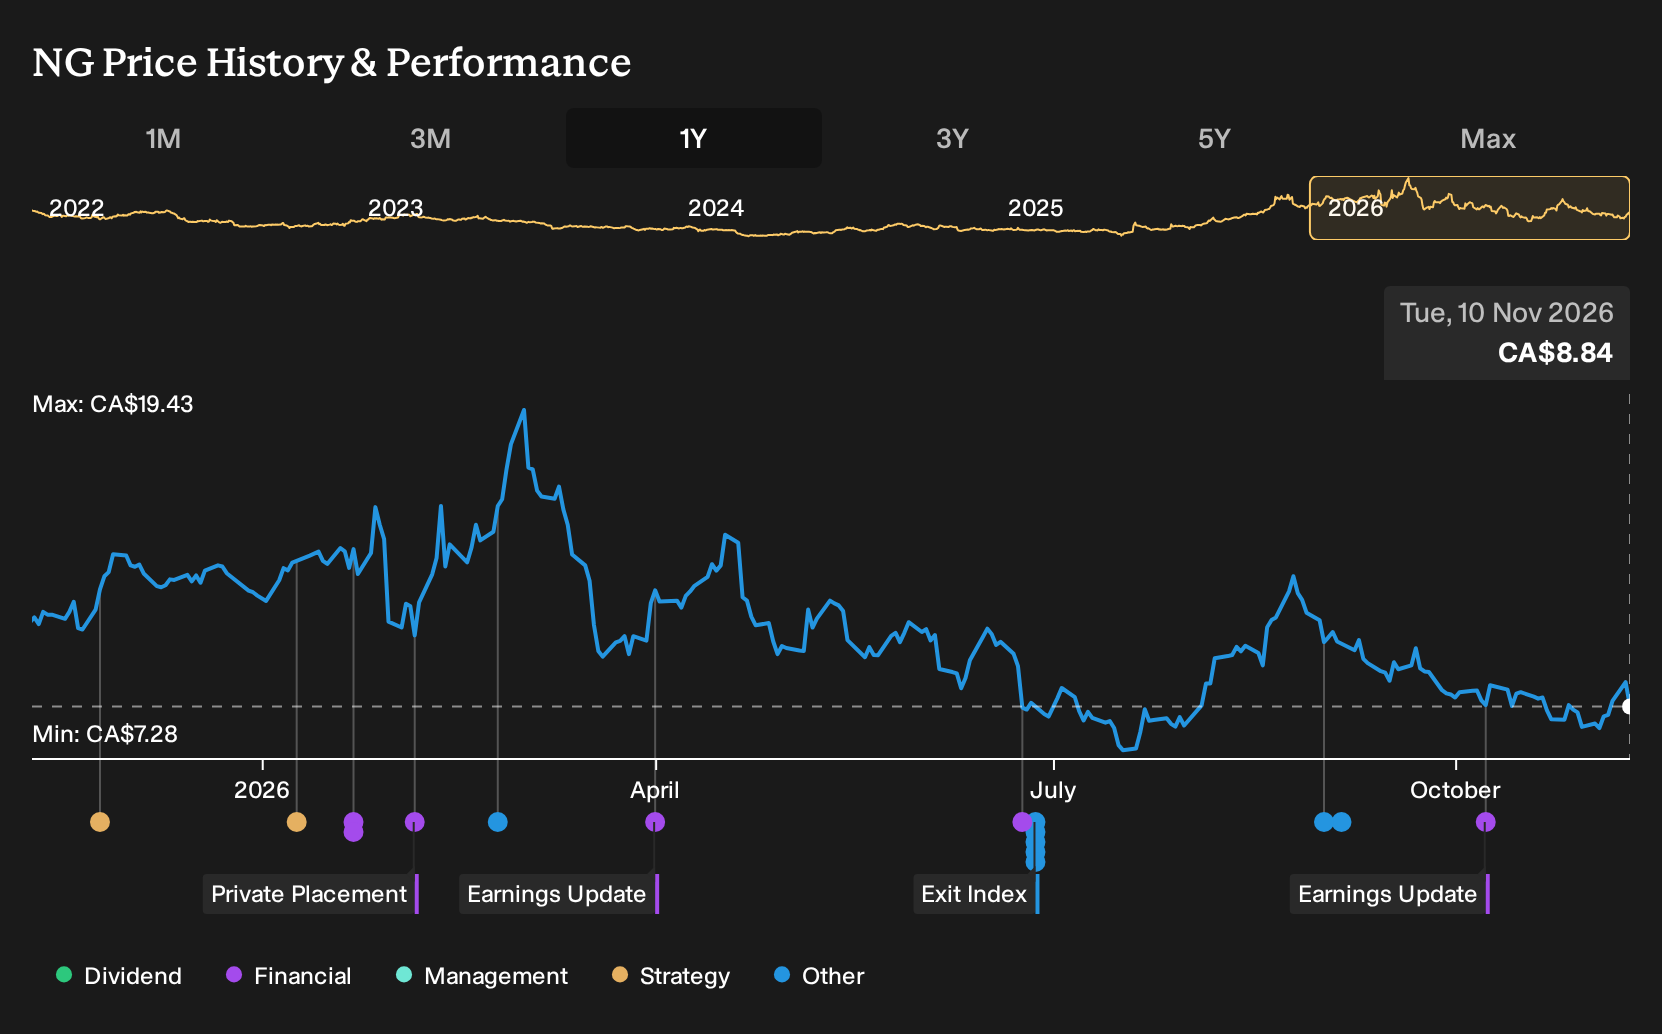
- NovaGold Resources (TSX:NG) declined 8.96%.
- GFL Environmental (TSX:GFL) fell 7.19% after rejecting buyout offers, and after JPMorgan cut its price target and maintained an Underweight rating.
- DPM Metals (TSX:DPM) declined 6.80% following approval for a Malartic drilling campaign that commits the company to cofinancing work.
On The Radar
For Canadian investors, the next stretch is all about inflation data at home and in the US, plus a dense run of TSX earnings that feed directly into banks, resource stocks and real estate plays.
- US PPI MoM, Fri 13 Nov. With consensus at 0.4% and the previous print at 1.3%, any upside surprise would harden the higher for longer Fed narrative, which tends to support the US dollar and pressure Canadian equities and rate sensitive stocks.
- Canadian Inflation Rate YoY, Mon 16 Nov. Headline CPI last sat at 3.1% and core at 2.2%, so a reading above those levels would keep borrowing costs elevated for Canadian households and could weigh on consumer and housing related shares.
- Canada Housing Starts, Tue 17 Nov. The last reading at 250,000 units is the reference point, and a weaker print would underline cooling residential construction, which matters for builders, building products suppliers and mortgage exposed lenders on the TSX.
- Canadian Tire Corporation, Thu 12 Nov. Q3 results arrive before the open, and the key focus is on revenue and retail margins, since those numbers speak directly to how well Canadian consumers are handling higher interest costs.
- Brookfield, Thu 12 Nov. Q3 earnings at 7:00 AM US Eastern hinge on fee related earnings and any comments on fundraising, which shape how this global asset manager allocates capital into Canadian infrastructure, real estate and renewable projects.
Sector & Industry Watch
Materials: Strong week on resource headlines
Materials have bounced hard over the past seven days after a weaker month, with the group roughly 10% higher on the 7 day numbers. Fresh Q3 results at CCL Industries and Neo Performance Materials plus project news from Millennial Potash and FCL X Fire & Safety keep attention on specialty chemicals, packaging and fertilizer related plays.
If you own Materials exposure, the one macro print that can quickly firm or cool sentiment is Friday’s US producer price index, since any surprise on input costs often feeds into metals pricing and margins for resource linked Canadian companies.
Metals and Mining: Battery metals and gold in focus
Metals and Mining have been one of the strongest groups this week, up a little over 10% on a 7 day view while 1 year performance is also positive. Royalty and project updates from Altius Minerals, Lithium Americas, PMET Resources, Aris Mining and a long list of junior explorers keep gold and battery metals squarely in the headlines.
If you hold Canadian miners, Friday’s US PPI release is the key macro cue, because shifts in producer price inflation can influence expectations for gold, copper and lithium prices and, in turn, how investors think about funding long life mining projects.
Energy and Oil and Gas: Softer week despite busy deal tape
Energy and Oil and Gas have pulled back over the last seven days, with both sectors down about 5% even though 12 month returns remain positive. The tape stays busy, from Logan Energy’s agreed sale and spin out to strong well results at Kolibri Global Energy, updated guidance at Keyera and fresh uranium exposure for IsoEnergy and Premier American Uranium.
If you own Canadian producers or midstream stocks, the swing factor to watch now is tomorrow’s US crude and gasoline inventory data, since a surprise build or draw can quickly sway views on oil prices and the cash flow that supports dividends, buybacks and drilling budgets.
Real Estate: REITs grind higher on retail strength
Real Estate has inched higher on both a 7 day and 30 day basis, even though returns over 1 year and year to date are still slightly weak. Grocery anchored and retail focused REITs such as Crombie, Slate Grocery and BTB are reporting high occupancy, acquisitions or take private deals, while Invesque and Dream Unlimited highlight asset sales and growing income properties.
If you rely on Canadian REIT distributions, the clearest local catalyst is Monday’s Canada CPI report, because the combination of inflation and borrowing costs shapes refinancing terms and how much rent growth tenants can handle without pushing vacancy meaningfully higher.
Tech and Semiconductors: Rate sensitive sector stays under pressure
Tech remains weaker on a 7 day, 30 day and 12 month view, with Semiconductors flat on the week but still showing a very large 1 year decline. Corporate news is active, from CGI’s solid Q4 earnings and dividend increase to HIVE Digital’s AI focused data center expansion, Sangoma’s proposed sale and Enghouse’s agreed acquisition of MIND C.T.I.
If you own Canadian Tech or chip stocks, Friday’s US core PPI release is the single macro event to track, because any shift in views on the Federal Reserve’s rate path can quickly change how much investors are willing to pay today for profits expected several years out.
Find Tomorrow's Top Performers
If the focus for you is stable income while US inflation keeps rate pressure elevated, start with this list of 3 dividend fortresses
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com