
Is Twist Bioscience (TWST) Undervalued After Its New Oncology Research Product Launches?
Twist Bioscience (TWST) just pushed deeper into oncology tools with Twist MRD Express, a custom panel offering aimed at faster, high-throughput personalized molecular residual disease testing for cancer research labs.
Despite the new MRD and antibody products drawing attention to Twist Bioscience, the stock has lost momentum in the near term, with the 30 day share price return down 17.3% and the 7 day move also weaker, even though the year to date share price return of 307.93% and a very large 3 year total shareholder return of 571.73% point to a longer-term story that has already rewarded early holders.
Scan beyond Twist Bioscience and see which other research-focused players are gaining traction with a curated list of 36 healthcare AI stocks.
The share price pullback, the analyst target gap of about 21% and a much larger implied intrinsic discount of around 61% sketch very different stories for Twist Bioscience. Where does fair value actually fall within that range?
Most Popular Narrative: 21% Undervalued
Twist Bioscience's analyst consensus Narrative on Simply Wall St pegs fair value at $168.25 versus the last close of $132.13, which points to a sizeable valuation gap that rests on ambitious growth and profitability assumptions.
In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 118.8x on those 2029 earnings, up from -79.6x today. This future PE is greater than the current PE for the US Biotechs industry at 18.8x.
See why 24 investors see Twist Bioscience as 21% undervalued.
The fair value estimate of $168.25 is built on analyst forecasts that Twist Bioscience grows revenue at about 20% a year and eventually earns margins in line with the wider US biotech group, discounted back using a 7.44% rate. That combination of growth, profitability and discount rate assumptions explains why the narrative outputs a roughly 21% discount to fair value at the current share price.
Result: Fair Value of $168.25 (UNDERVALUED)
Still, the story around Twist Bioscience can change quickly if customer concentration becomes an issue or if ongoing losses demand fresh equity and dilute existing holders.
Find out about the key risks to this Twist Bioscience narrative.
Another View: Twist Bioscience Looks Expensive On Sales
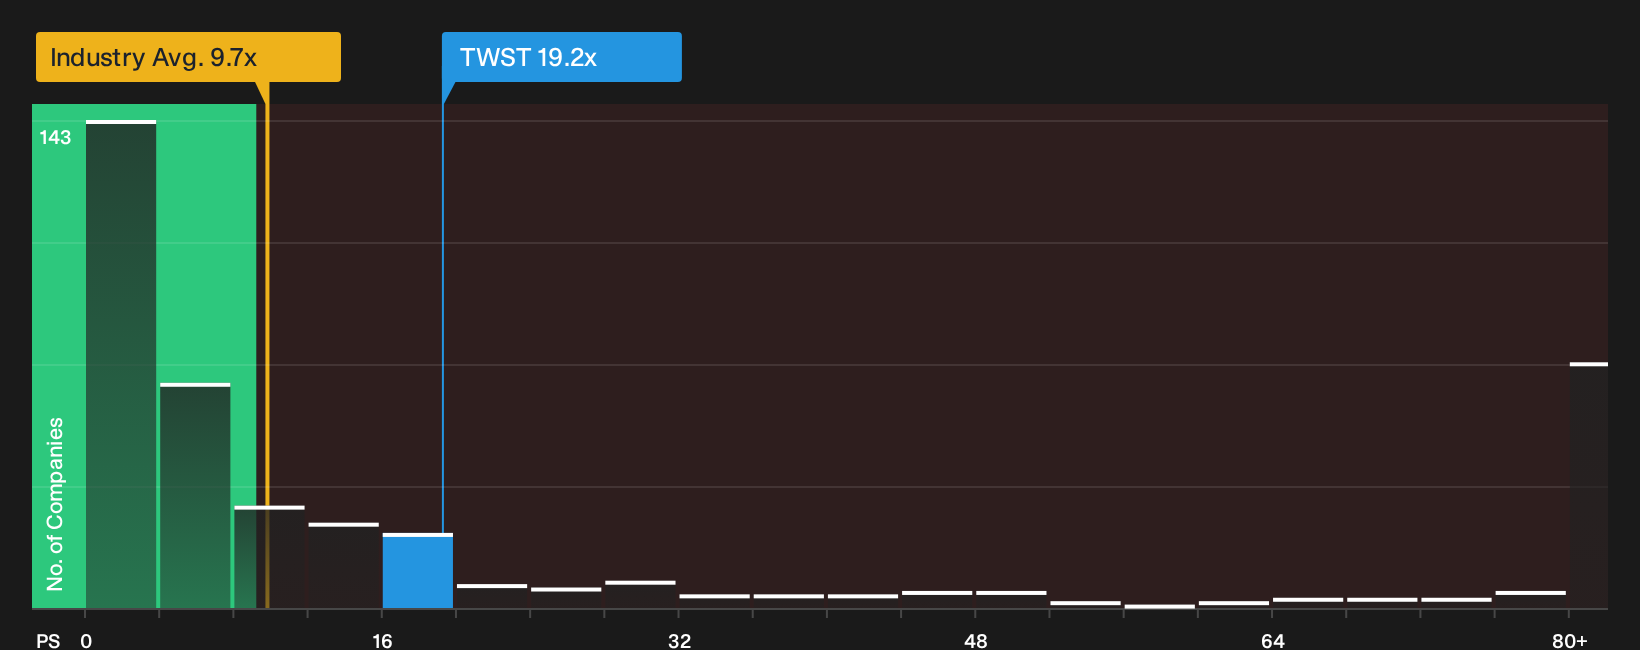
While the Simply Wall St future cash flow view suggests Twist Bioscience trades at a steep discount to intrinsic value, the simple sales-based lens tells a different story. The current P/S of 19.2x is roughly double the US Biotechs average of 9.7x and sits well above a fair ratio of 6.8x. This points to a lot of success already priced in and raises the question of how much valuation risk you are willing to accept.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Twist Bioscience's valuation and risk profile can cut both ways, so move quickly, review the underlying data, and weigh the 2 key rewards and 3 important warning signs.
Looking for More Ideas Beyond Twist Bioscience?
If Twist Bioscience has your attention, do not stop there. Use the Simply Wall St screener to quickly surface fresh opportunities that fit your style and risk limits.
- Spot potential underpriced opportunities early by scanning a 35 high quality undervalued stocks that pairs quality fundamentals with discounted valuations.
- Strengthen capital preservation by focusing on a 30 resilient stocks with low risk scores that highlights businesses with more resilient risk scores.
- Unearth lesser-known prospects by working through a 20 high quality undiscovered gems that filters for strong fundamentals outside the usual crowd favorites.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com