
What B&G Foods Bears Saw Before The Fall
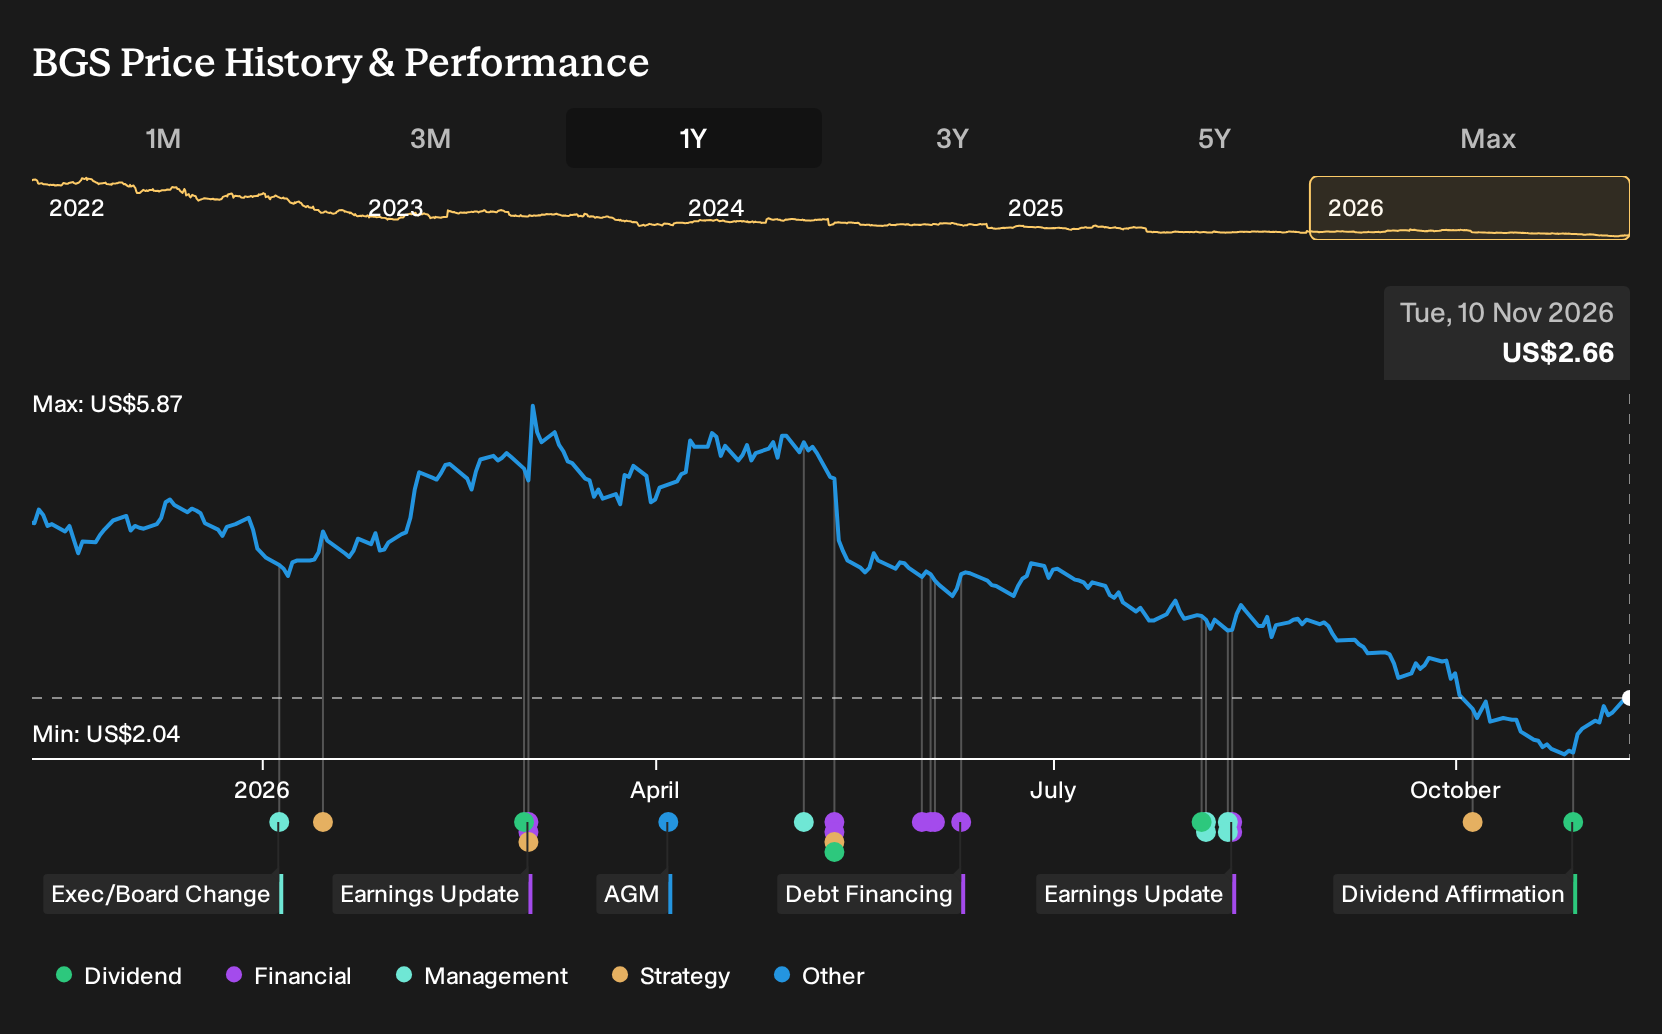
If you had backed B&G Foods based on the 2025 bullish and bearish cases around affordable packaged foods and e-commerce, the outcome over the next twelve months would have been painful. Holding B&G Foods over the past year would have meant a 35.6% loss, including dividends. If that decision date was 10 November 2025, what did the original thesis miss about shrinking revenue, still-lossmaking net income, and reliance on continued margin repair?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind B&G Foods. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On B&G Foods
The shares cost US$4.58 at the start of the period, which put B&G Foods between two sharply different stories about what might come next.
On the optimistic side, the bullish August 2025 Narrative set Fair Value at US$5 and leaned on profit margins climbing from a loss to 5.4% over three years, even while revenue was expected to decline 1.3% a year.
The bearish August 2025 view pointed to Fair Value of US$4.1 and accepted revenue falling 1.5% annually, while assuming margin repair to 6.5% could still happen in spite of high debt and input cost risks.
What The Results Changed For B&G Foods
The clearest fresh fact was B&G Foods’ Q2 2026 report. Revenue fell from US$424.425m to US$383.275m compared with Q2 2025, which challenged both cases that assumed only modest top line decline. The loss narrowed from US$9.772m to US$3.981m and net margin improved from -2.3% to -1.0%, so the profitability repair story remained unproven but not broken. Overall, the evidence pointed in both directions.
The lesson is simple. When a thesis leans on margin repair, track net income and net margin each quarter and treat any revenue contraction as a separate test, not an afterthought.
What Today’s Lower B&G Foods Price Is Asking You To Believe
Today B&G Foods trades at US$2.66, and the analyst consensus Narrative on Simply Wall St places its Fair Value above that level based on its own framework rather than objective fact.
The Narrative leans on portfolio mix changes, margin repair and debt reduction. A buyer today would need to believe that margin improvement and cash generation can support meaningful deleveraging from here.
"The continued reshaping of B&G Foods toward higher-margin, lower-working-capital brands, supported by divestitures of products like Green Giant U.S. frozen and additions such as College Inn and Kitchen Basics broth, is expected to keep shifting the mix toward categories that support adjusted EBITDA margins and more stable cash flow."
One Narrative disagrees with today's price. → See where this Narrative says B&G Foods should trade
Which Company Could Surprise You Next?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 33% below our estimate - sells cloud and AI infrastructure where subscription and usage based pricing now converge.
- Company 2 - 38% below our estimate - captures AI related airfreight and customs work as automated workflows reshape complex trade compliance.
- Company 3 - 40% below our estimate - secures subsea equipment orders as faster brownfield tiebacks shorten project timelines for energy producers.
Those are three of them. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com