
Bodycote (LSE:BOY) Draws Hedge Fund Attention, Is The Stock Now Too Pricey?
Why recent hedge fund disclosures put Bodycote on watchlists
Bodycote (LSE:BOY) has been in the spotlight after several hedge funds, including Millennium, Balyasny, Sand Grove and Qube, reported sizeable cash settled derivative positions in the stock under UK takeover disclosure rules.
Recent filings have landed on top of a share price that has already moved sharply over a longer stretch. Bodycote is trading at £9.175 after a strong year to date share price return of 29.23% and a 1 year total shareholder return of 52.38%, while multi year total shareholder returns of 68.46% over three years and 29.30% over five years point to momentum that has been building rather than fading as the market reassesses both the growth potential and the risks around the business.
Scan how hedge fund attention around Bodycote compares with other potential movers by reviewing a curated set of 5 high quality undiscovered gems in similar industrial and niche service niches.
After a run like Bodycote has had and fresh hedge fund interest on the register, the puzzle is simple. Does paying £9.175 now still stack up on valuation, or is patience the better trade?
Most Popular Narrative: 1% Undervalued
On the analyst consensus Narrative on Simply Wall St, Bodycote screens as only modestly undervalued, with a fair value estimate of £9.25 against the latest £9.18 close. As a result, the debate shifts from cheap versus expensive to whether the business can actually deliver the cash flows that have been pencilled in using a 9.11% discount rate.
The expanded Optimise program, which has already delivered about £4 million of annualised savings and is expected to reach at least £15 million of recurring cost benefits by the middle of 2027 as 29 of 31 footprint actions complete and further automotive rationalisation is assessed, is reducing overheads and low margin noncore revenues, supporting higher group EBIT margins and cash flow.
What is behind 11 investors see Bodycote as 1% undervalued.
Result: Fair Value of £9.25 (UNDERVALUED)
Still, Bodycote’s reliance on structurally weak Western Europe automotive work, along with the risk of slower aerospace and industrial gas turbine orders, could easily challenge that tidy fair value story.
Find out about the key risks to this Bodycote narrative.
Another View: Bodycote on earnings multiples
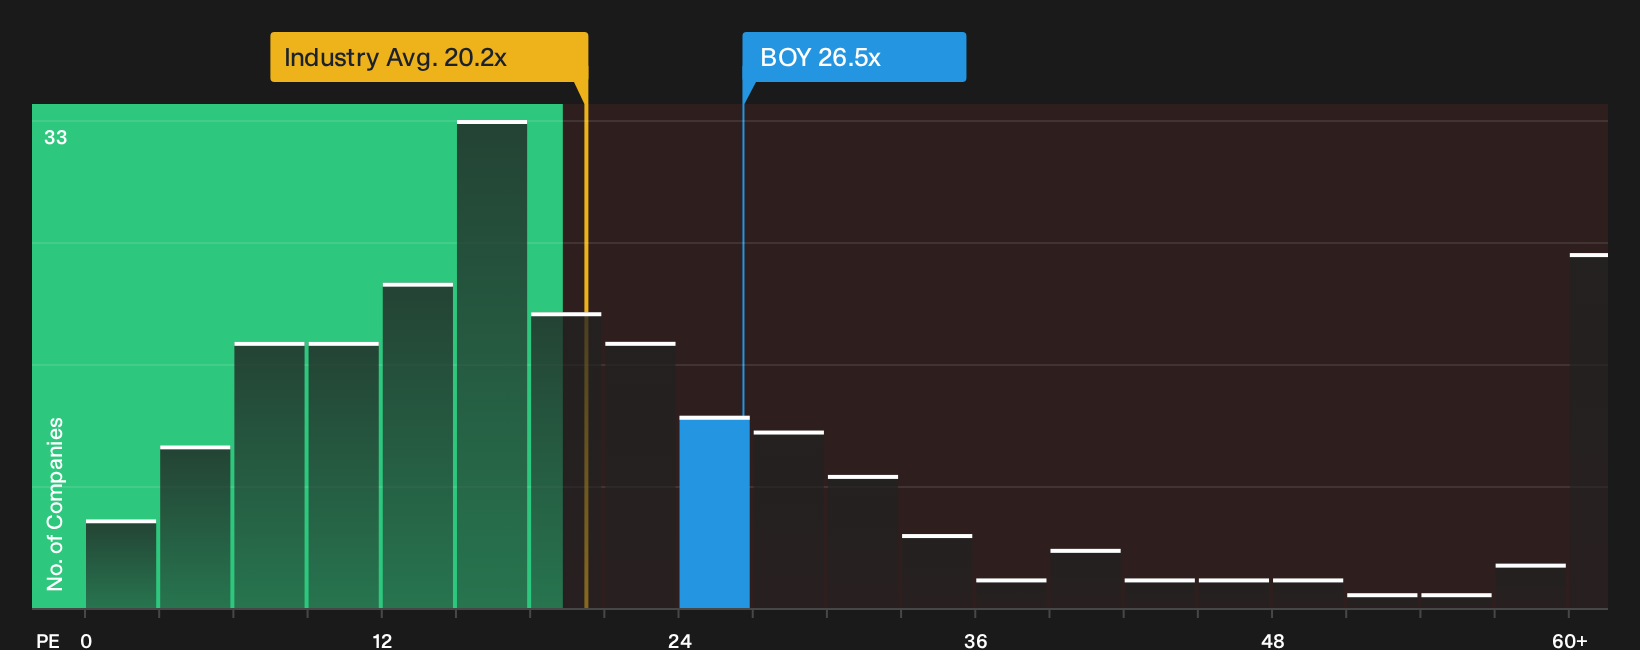
On a simple earnings lens, Bodycote does not look cheap. The shares trade on a 26.5x P/E, which is richer than the European Machinery average of 20.2x and slightly above a fair ratio of 25.1x that the market could gravitate toward, even though the multiple is far lower than peers at 73.1x. For an investor weighing upside against the risk of a P/E squeeze, how comfortable does that trade off feel?
For a closer look at how those valuation gaps compare with the peer group and that fair ratio anchor, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Bodycote’s valuation, hedge fund interest and operating risks make this a stock where your own homework matters. To see both sides of the story in one place, weigh up the 3 key rewards and 2 important warning signs
Looking for more Bodycote sized investment ideas?
If Bodycote has sharpened your focus on valuation, risk and momentum, do not stop here. Fresh opportunities rarely wait for investors who stay on the sidelines.
- Target quality at a discount by scanning a focused set of 16 high quality undervalued stocks that combine stronger fundamentals with more appealing prices.
- Prioritise resilience and sleep better at night by reviewing a 4 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier risk profiles.
- Get ahead of the crowd by zeroing in on a 15 elite penny stocks with strong financials that highlights smaller companies with the financials to back up their potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com