
Meta Stock: Midterm Election Results Raise Concerns Over AI Data Center Expansion
Growing political friction around local power consumption, water usage, and community environmental impacts is creating unexpected headwinds for physical computing deployments. As newly elected officials push for stricter local regulations and moratoriums, tech hyperscalers face rising hurdles when securing the land, permits, and utility access needed for large-scale digital power builds.
Warning of regulatory hurdles following recent U.S. midterm election outcomes, Meta Platforms (META) cautioned that political shifts would complicate its data center expansion plans.
About Meta Platforms
Meta Platforms is a global technology company operating Facebook, Instagram, WhatsApp and Messenger. Its business is primarily driven by digital advertising, while its growing investments in artificial intelligence (AI), generative AI models, smart glasses, and virtual reality are shaping its next phase of expansion.
Meta Stock Surges After Weeks of Weakness
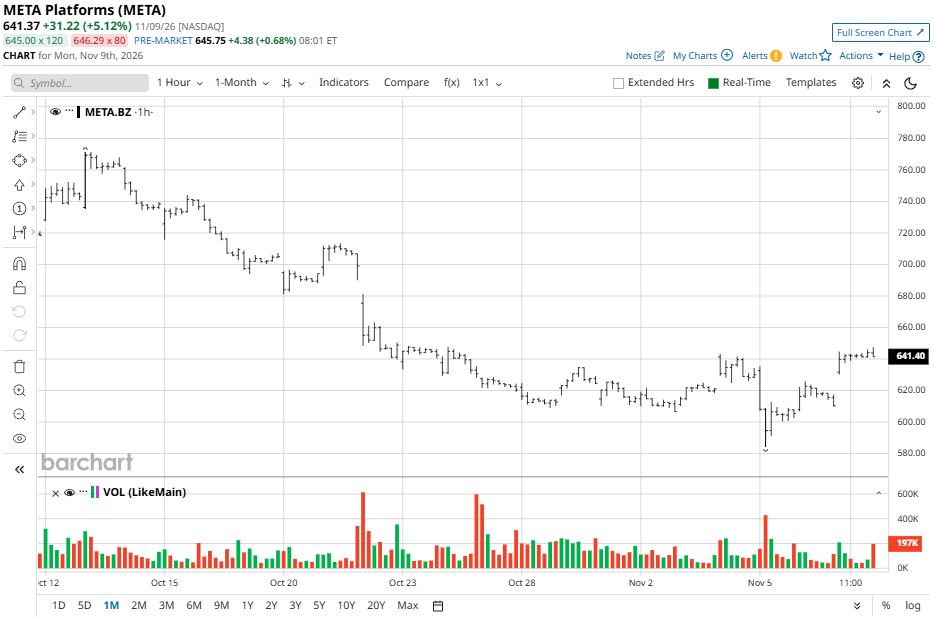
Meta stock has experienced considerable volatility in 2026 as investors balance strong digital advertising growth against rising AI infrastructure costs and regulatory uncertainty. Shares closed at $641.37 on November 9, gaining 5.12% during the session following a sharp decline in the preceding weeks. The stock remained below its 52-week high of $779.82, while its one-month performance was down approximately 13.7%.
Meta Results Outperforms Analysts
Meta reported Q3 2026 revenue of $64.60 billion, representing 26% year-over-year growth and exceeding analysts' expectations of approximately $63.34 billion. Reported diluted earnings per share came in at $3.83, below the consensus estimate of $6.54. However, the headline figure included a one-time $9.89 billion legal charge related to an agreement with 52 U.S. state attorneys general. Excluding this expense, Meta's diluted EPS would have reached $7.40, surpassing analyst expectations and reflecting stronger underlying earnings performance.
The company's operating metrics demonstrated continued momentum across its advertising business. Advertising revenue increased 26% to $63.06 billion, while ad impressions grew 10% year over year and the average price per advertisement climbed 14%. Family daily active people reached 3.64 billion, up 3% from the previous year. However, total costs and expenses surged 68% to $51.61 billion, reducing operating margin to 20% from 40%. Capital expenditures reached $34.91 billion, while free cash flow turned negative at $2.12 billion. Meta ended the quarter with $82.45 billion in cash, cash equivalents, and marketable securities.
Looking ahead, management expects Q4 2026 revenue of $73 billion to $76 billion, supported by continued advertising growth and AI-driven improvements across its platforms. Meta raised its full-year expense outlook to $175 billion-$179 billion and projects capital expenditures of $135 billion-$145 billion as it expands AI infrastructure and data center capacity. The company also expects Reality Labs operating losses to decline to $18 billion-$19 billion in 2026, with further improvement to approximately $15 billion in 2027.
Midterm Election Results Could Complicate AI Data Center Expansion
Meta Platforms may face growing challenges in expanding its U.S. data center network following the latest midterm election results. President Dina Powell McCormick warned at the WSJ Tech Conference that political opposition and increased regulatory scrutiny could make new data center construction more difficult, potentially slowing the infrastructure buildout needed to support Meta's ambitious artificial intelligence (AI) strategy.
The company is investing heavily in computing capacity to develop its Muse AI agents for billions of users, with planned 2026 capital expenditures reaching as much as $145 billion. Powell McCormick indicated that expanding existing facilities may be easier than securing approval for entirely new projects. Meta is also exploring international locations to diversify its infrastructure investments, highlighting the growing regulatory and political risks surrounding AI data center development.
Should You Buy META?
Meta's AI growth ambitions face potential infrastructure challenges as midterm election results could bring tighter scrutiny and delays for new U.S. data center projects. However, its plans to expand existing facilities and explore international locations may help sustain its long-term AI investments.
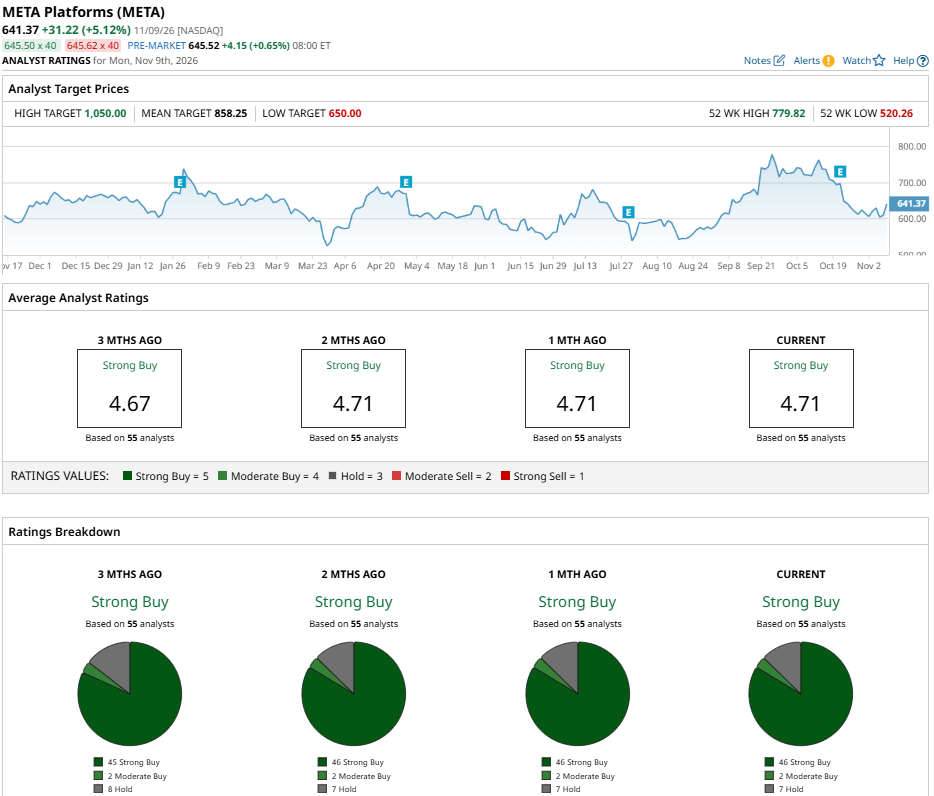
Wall Street remains optimistic, assigning META a “Strong Buy” consensus rating and a mean price target of $858.25, implying approximately 33% upside from its current market price. Of 55 analyst ratings, 46 are “Strong Buy,” two are “Moderate Buy,” and seven are “ Hold,” reflecting strong confidence in Meta's long-term growth prospects.
On the date of publication, Ruchi Gupta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.