
Is Emerson Electric (EMR) Stock Rich Or Reasonable On Cash Flow?
Emerson Electric has delivered strong shareholder returns in recent years, and the latest cash flow figures keep investors focused on whether the current share price is fully supported by what the business can generate in hard dollars. With the stock recently closing at US$167.54, the issue on the table is how those cash flows stack up against that price tag.
- Emerson Electric has returned about 99.5% over the past 3 years, which puts real pressure on the cash flow story to justify how far the stock has already run.
- Recent results, including higher free cash flow, a larger backlog and a higher regular dividend, can support a case that the company’s cash generation has become more robust and more visible.
- What if you looked at Emerson Electric through its earnings instead? See what Emerson Electric's 34.7x P/E says about the price.
The issue now is whether Emerson Electric's current valuation is fully explained by the cash flows implied in its Discounted Cash Flow (DCF) intrinsic value estimate.
If you want to test whether questions like Emerson Electric's cash flow valuation line up across a broader watchlist, scan the market using the 35 high quality undervalued stocks
Does Emerson Electric Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Emerson Electric’s future free cash generation and discounts it back to today in dollar terms. On the latest figures, the business produced about $3.53b of free cash flow over the last twelve months, and the long range forecast assumes that cash figure grows rather than shrinks over time, then settles into more modest expansion in the 2030s.
On those inputs, the DCF estimate comes out substantially below the current share price of US$167.54. This implies the market is assigning a richer tag to Emerson Electric than its modeled cash flows alone support. The 2026 update, which includes higher free cash flow, a larger backlog and a raised dividend, helps explain why investors are willing to pay up even though the discounted cash flow output points lower. Find out what Emerson Electric could be worth using our Discounted Cash Flow (DCF) estimate.
The Emerson Electric Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up exactly where Emerson Electric's valuation puzzle leaves you. They spell out which paths for future growth, margins and earnings would need to unfold for the stock to be worth meaningfully more or less than today. Each scenario links its implied number to a clear view on how Emerson Electric's expansion prospects, profitability and risk profile might shift, giving you a reference point you can revisit on the Community page as new information arrives.
Bulls and bears are looking at the same Emerson Electric order book and software push yet reach very different conclusions on value.
Bull case: 5% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which blends mainstream forecasts into a single storyline.
"The accelerating adoption of digital automation and artificial intelligence solutions in global industrial markets is fueling strong demand for Emerson Electric's advanced software platforms and AI-enabled products, such as Ovation 4.0 and Nigel AI adviser…"
Discover why this Narrative puts Emerson Electric at 5% undervalued.
Bear case: 21% overvalued
This angle reflects the bearish analyst Narrative on Simply Wall St, which builds on the most pessimistic published forecasts.
"The numbers indicate that Emerson Electric’s current share price already reflects optimistic outcomes on long cycle power, LNG, and software growth, so the valuation leaves limited room for disappointment on execution or macro shocks…"
Explore why this Narrative puts Emerson Electric at 21% overvalued.
Emerson Electric's price is only one piece of the decision
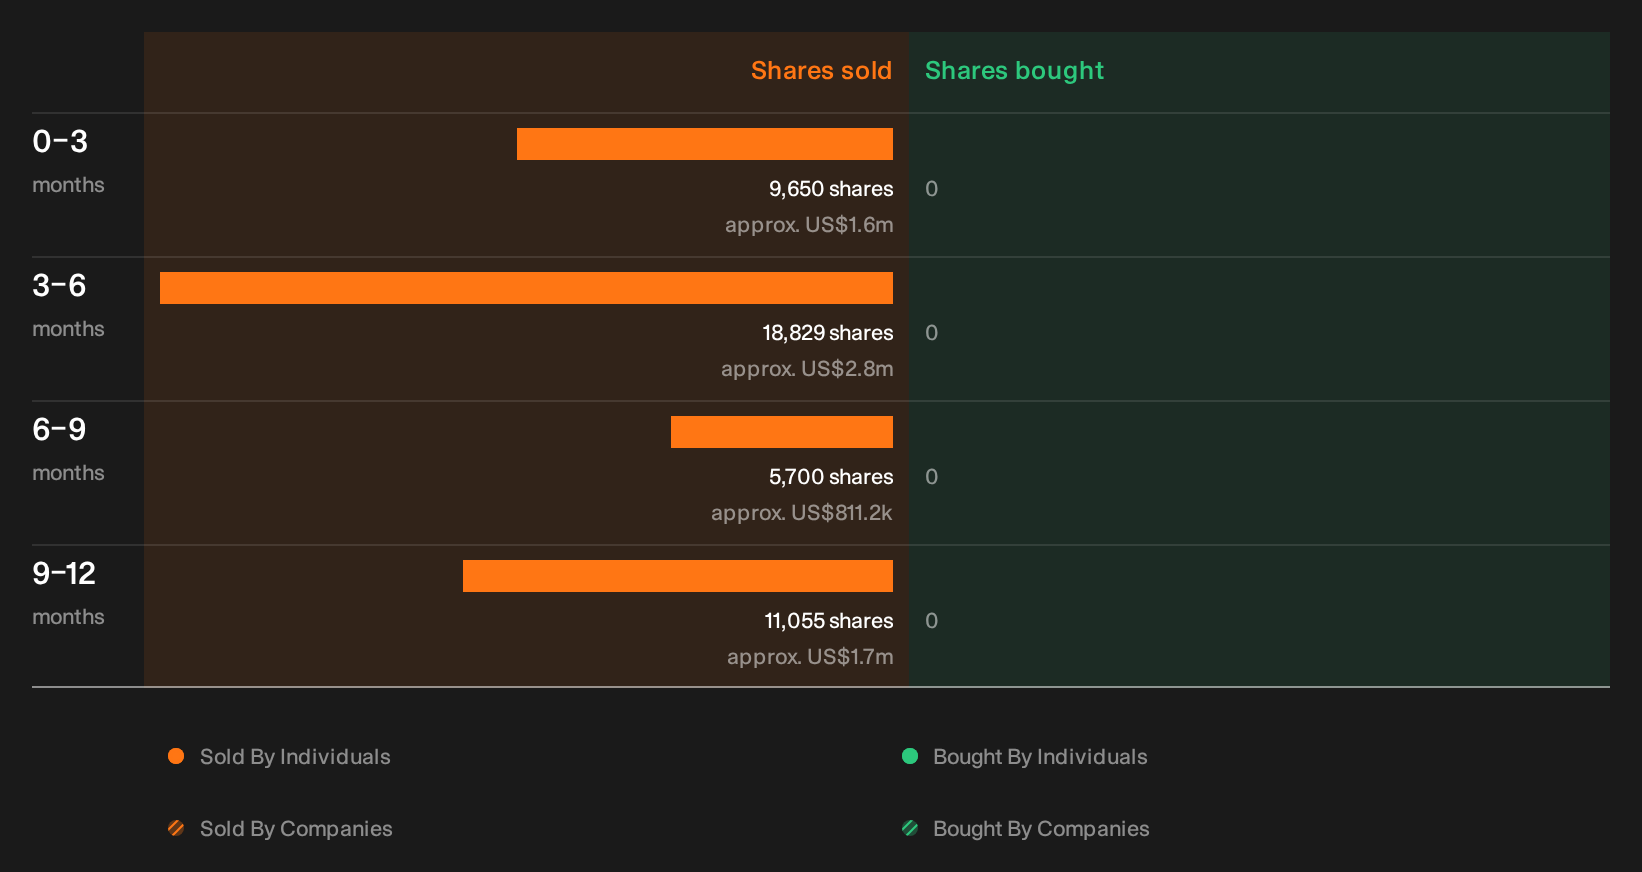
Beyond models and market debate, recent trades by Emerson Electric's own leadership can offer a different kind of signal. The individuals involved, the volumes, and what they might hint at are still for you to review. See the recent insider selling flagged for Emerson Electric.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com