
Learn Why The Bull Case For XP Stock Could Change Following Quarterly Earnings Results
- XP Inc. is set to report September 2026 quarterly results that analysts expect will show year over year changes in earnings and revenue, with a positive Earnings ESP and a Zacks Rank #3 cited as supporting signals.
- The key question for XP is whether any earnings surprise reflects deeper progress in shifting clients toward fee based advisory and broadening revenue beyond pure brokerage.
- Next, the focus will be on how XP's earnings results could influence the longer term investment narrative.
Scan other financial platforms aiming to achieve similar earnings momentum as XP by exploring our curated list of 35 high quality undervalued stocks.
XP Investment Narrative Recap
To own XP, you need to believe the business can keep compounding its R$18.6b revenue base by deepening fee based advisory and scaling beyond pure brokerage, as framed in the analyst consensus Narrative on Simply Wall St. The short term hinge is whether the September 2026 results confirm that client assets and transaction activity are healthy enough to support this shift.
The biggest near term risk remains fee pressure, especially in fixed income where lower take rate, high liquidity products already dominate new sales. If the earnings release shows mix moving faster into lower margin areas without enough offset from cards, FX, insurance or advisory, that would raise tougher questions about XP’s medium term profitability.
The most relevant context for this earnings event is XP’s own guidance around efficiency and capital use. Management has talked about keeping the efficiency ratio around 34.3% in 2026 while still investing in technology, AI tools and sales force expansion, and has already flagged around R$2.5b in share repurchases and dividends for the year.
Those commitments set a high execution bar. You will likely want to see whether the September quarter shows revenue and net income, currently R$18.6b and R$5.3b respectively, tracking in a way that supports both ongoing investment and that capital return plan. If costs are running hot without clear revenue traction, XP’s near term risk profile widens.
XP's narrative projects R$25.8b revenue and R$7.3b earnings by 2029. That profile rests on analysts assuming 11.4% yearly revenue growth and an earnings increase of R$2b from R$5.3b today.
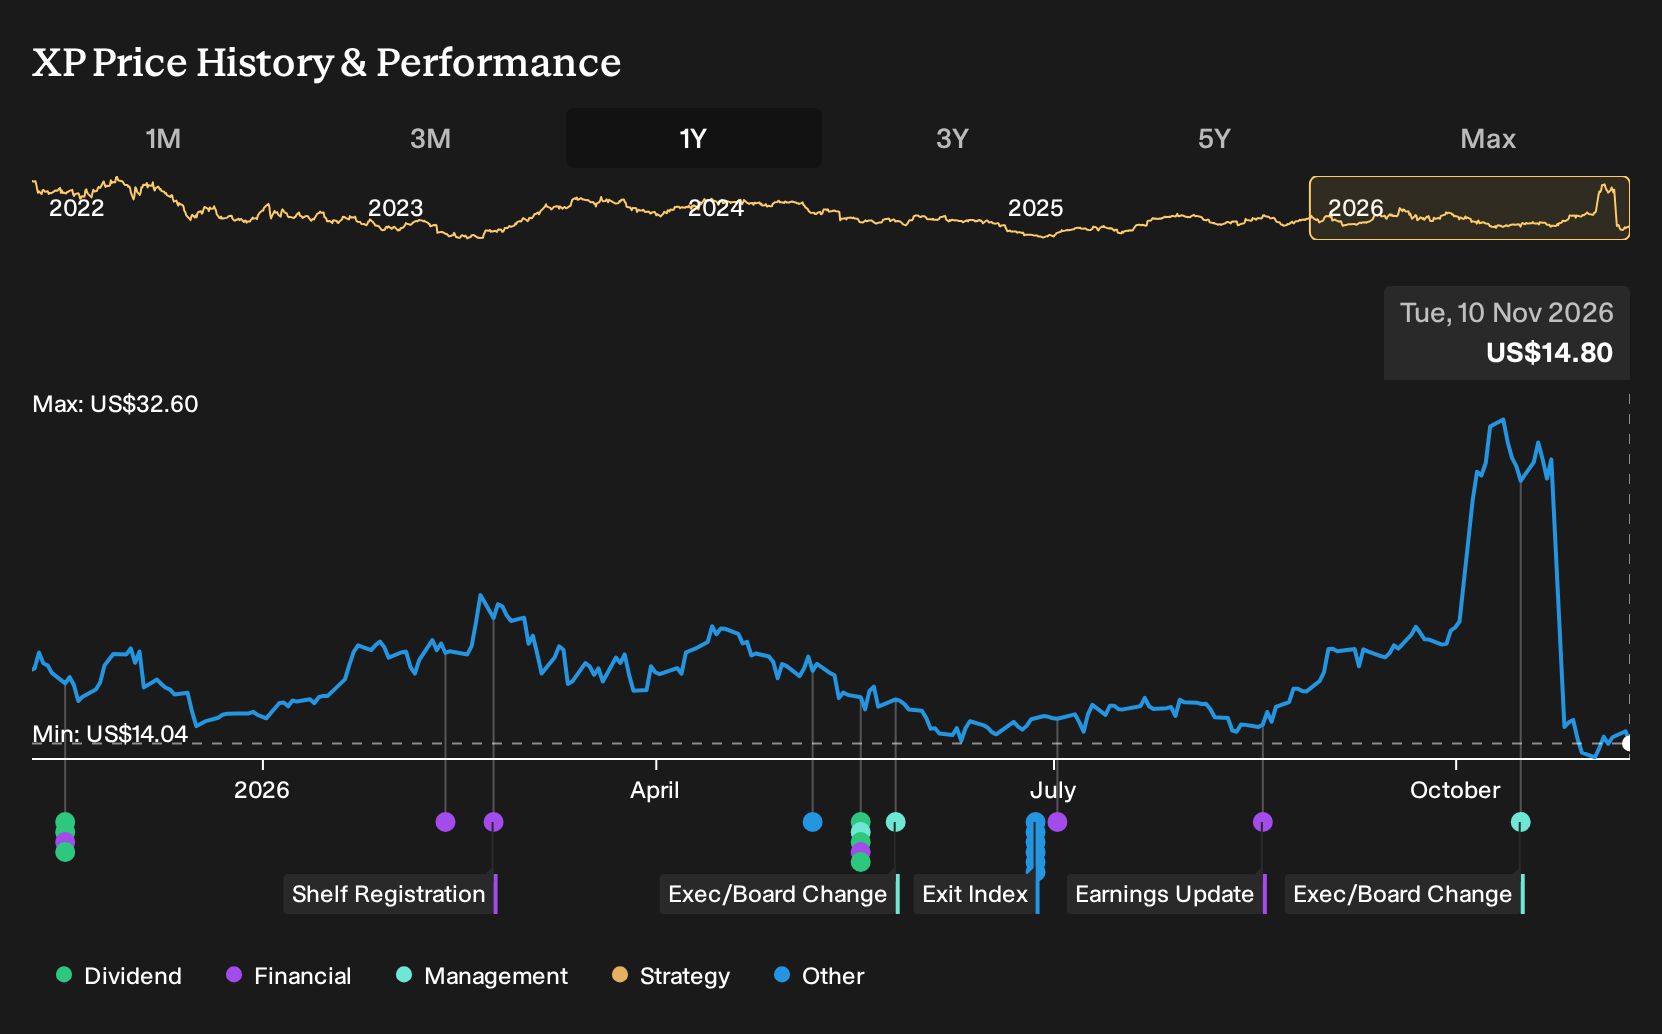
Uncover why XP's fair value indicates a 69% potential upside to its current price before that discount gap starts to close.
Exploring Other Perspectives
For XP, the alternate view fixates on product mix risk. The most cautious analysts think heavier use of low fee fixed income could keep revenue nearer R$24.5b and earnings around R$7.0b by 2029. That is below consensus. Use the September 2026 report to decide which narrative feels closer to your own read.
Explore 2 other XP fair value estimates, including one that suggests it could be worth just $21.30!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your XP research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for XP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate XP's overall financial health at a glance.
Looking For More Ideas Beyond XP?
If XP has sharpened your thinking about what you want from a business, use that same lens across the wider market with the Simply Wall St Screener. Line up other opportunities against the same criteria you are applying here and see which ones actually fit your approach instead of just catching your eye.
- For investors hunting quality at a reasonable price, start with companies that combine strong fundamentals with what looks like a discount through our 35 high quality undervalued stocks.
- If capital protection sits high on your list, focus on steadier businesses screened for resilience and lower risk profiles by using the 30 resilient stocks with low risk scores.
- When you want durable balance sheets as your foundation, concentrate on financially sound companies highlighted in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com