
Does Rigetti Computing (RGTI) Need More Than Book Value Support?
Rigetti Computing has seen its share price move sharply in recent years, and with fresh headlines around quantum milestones and new funding, investors are increasingly asking how well the current market value lines up with the company’s book value. The issue is whether the balance sheet can support today’s US$12.15 share price in a sector where expectations often move faster than fundamentals.
- Rigetti’s very large 3 year return of roughly 9x puts a lot of past optimism into the share price. That makes the link between that move and the firm’s underlying net assets an important question.
- Recent progress on higher fidelity quantum systems and a US$100 million public funding agreement can influence future capital needs and asset intensity. This in turn feeds directly into how investors think about book value support.
- The analysts covering Rigetti Computing have run their own numbers. See what analysts think Rigetti Computing's shares could be worth.
The stock’s next move may depend on whether Rigetti’s current price still lines up sensibly with the value of equity already recorded on its balance sheet compared with the industry average.
To see how Rigetti Computing compares with other quantum-focused plays on book value and balance sheet support, line it up against 25 quantum computing stocks.
Does Rigetti Computing Look Pricey on Book Value?
P/B is a useful yardstick for Rigetti Computing because the business is still loss making and investors are leaning more on the balance sheet than on current earnings.
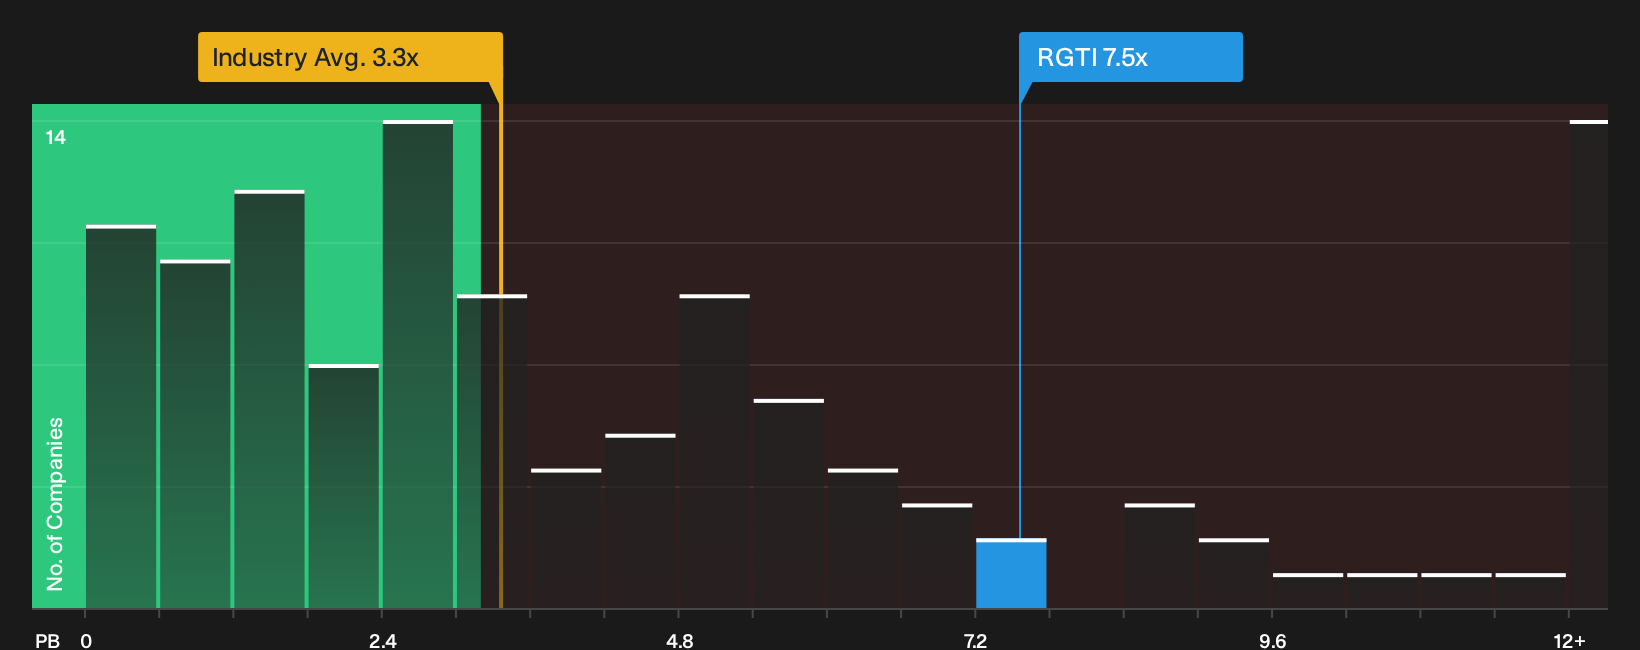
Rigetti trades on a P/B of about 7.5x, compared with a semiconductor industry average near 3.3x and a peer group around 4.8x. That is a clear premium to both the wider sector and closer quantum computing rivals. This suggests investors are willing to pay significantly more per dollar of equity than is typical for this corner of the market.
The recent US$100 million funding agreement with the U.S. Department of Commerce helps explain some of that optimism. However, the current P/B still points to Rigetti Computing being overvalued relative to industry book based markers. Anyone looking at the shares needs to judge whether the current technology roadmap and future deal pipeline justify paying that much over the sector norm for the existing asset base. Explore the numbers behind Rigetti Computing's P/B valuation.
The Rigetti Computing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Rigetti Computing valuation puzzle leaves off. They spell out which assumptions on future growth, profitability and earnings power would need to hold for Rigetti Computing's shares to be worth materially more or less than today’s level. Rather than relying on a single ratio or model point, each one lays out its own fair value framework so you can compare those assumptions with the numbers the company reports over time.
Bulls and bears looking at Rigetti Computing are focused on the same quantum roadmap but draw very different conclusions about how much risk you are being paid for.
Bull case: 54% undervalued
The analyst consensus Narrative on Simply Wall St highlights why some see Rigetti’s contract pipeline and hardware roadmap as underappreciated.
"On premises Novera system sales, which are designed to be upgradable from 9 qubits to higher counts, create a hardware footprint inside research and industrial labs…"
Discover why this Narrative puts Rigetti Computing at 54% undervalued.
Bear case: 10% overvalued
According to DanielOliveira, an investor in the Simply Wall St Community, short term delivery timing and revenue recognition could easily upset expectations.
"A slip into January leaves Q4 near $1.8 million and the full year near $13 million, against a $23.26 million consensus…"
Explore why this Narrative puts Rigetti Computing at 10% overvalued.
One more Rigetti Computing signal that could change how you see the story
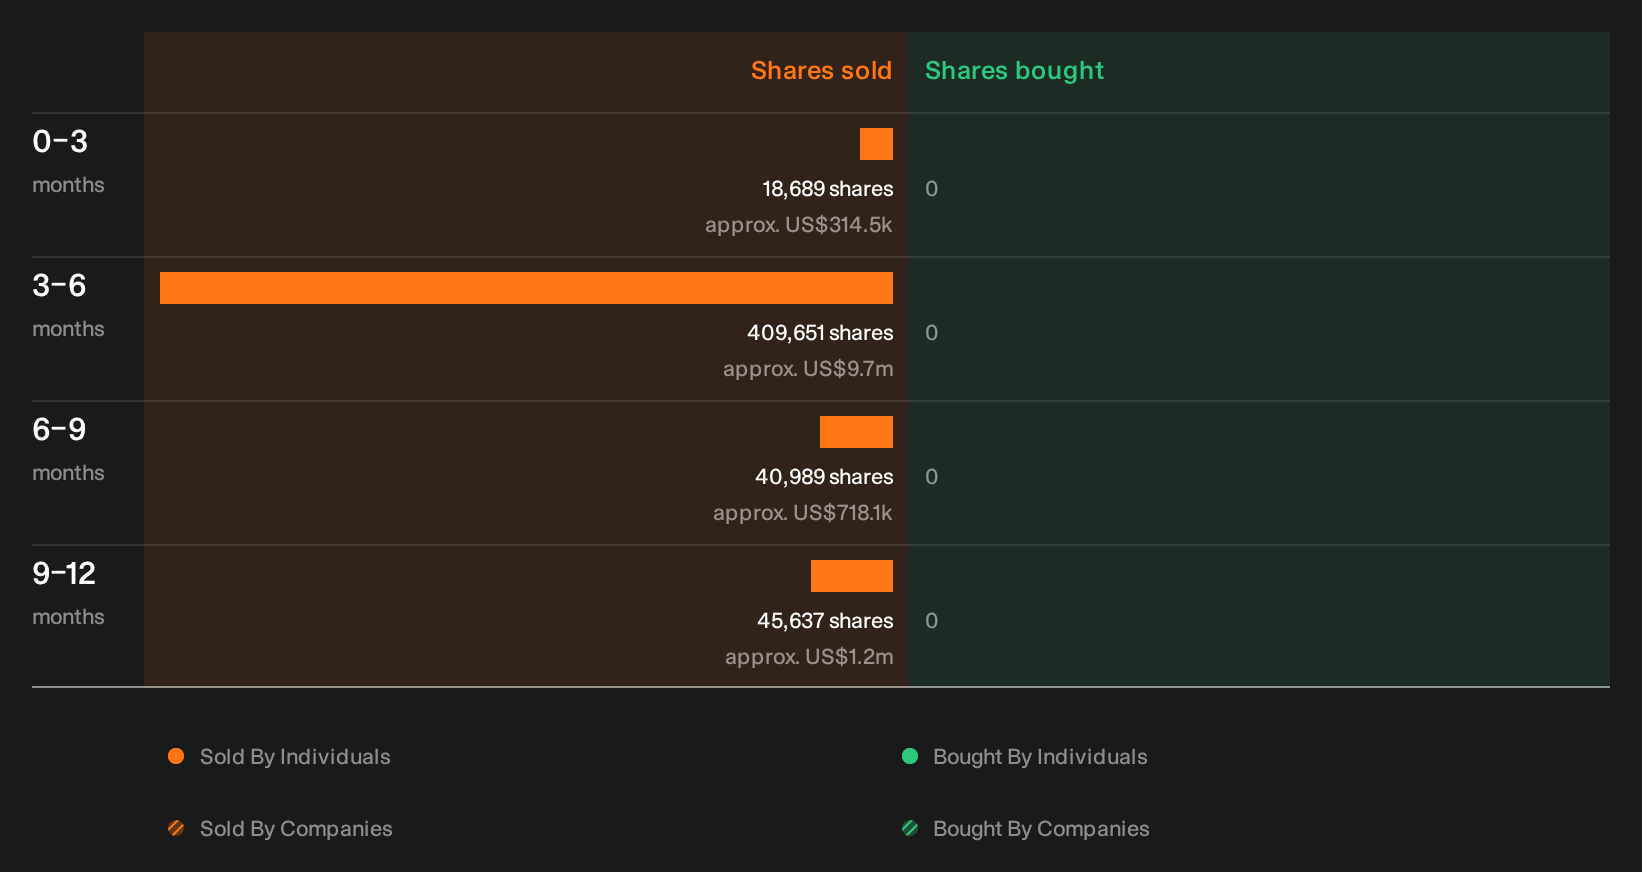
There is one loose thread that the numbers here do not touch. Recent transactions by people inside Rigetti Computing have been flagged by our checks, and the who, how much and why now are for you to explore. See the recent insider selling flagged for Rigetti Computing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com