
Learn Why The Bull Case For TD SYNNEX Stock Could Change Following AI Strategy Progress
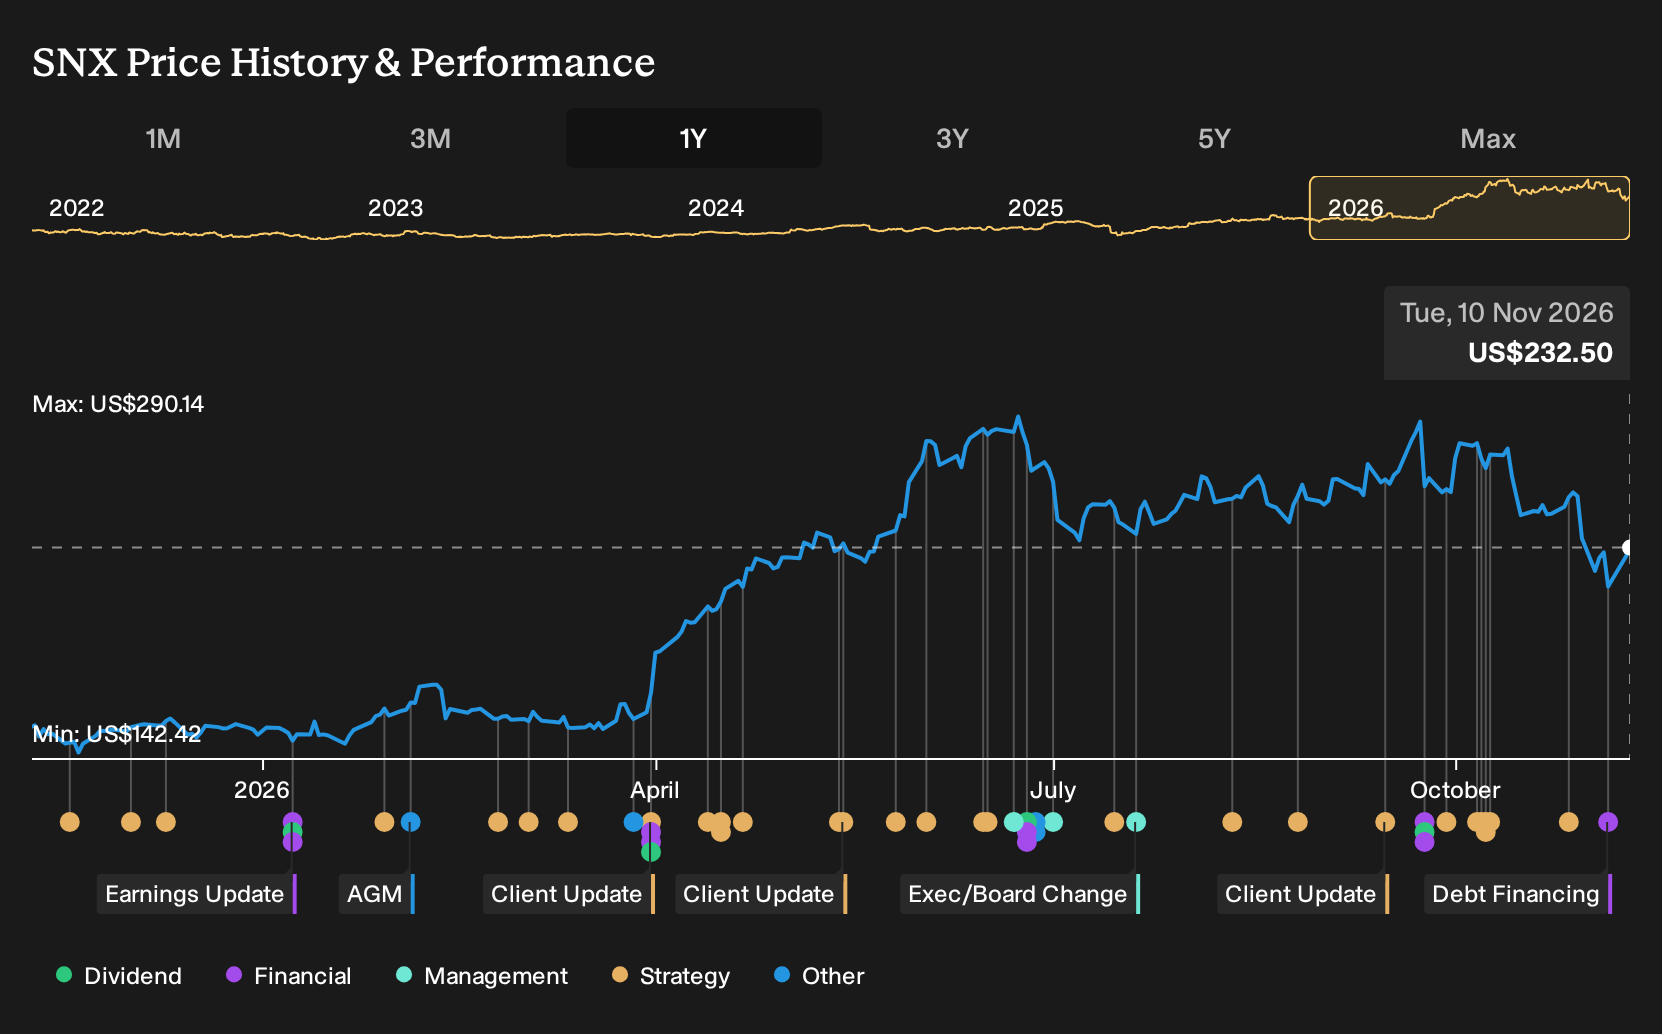
- TD SYNNEX entered a new US$1.75b senior unsecured term loan in November 2026, refinancing a US$750m facility and extending debt maturity to November 2029. The transaction also adds capital for general corporate uses, including acquisitions.
- The term loan's covenant package links interest costs and leverage limits to TD SYNNEX's public debt rating and EBITDA-based ratios. This underlines how balance sheet discipline is tied to its growth and acquisition plans.
- This analysis will examine how TD SYNNEX's new term loan, and its role in funding acquisitions, fits into the broader investment narrative.
Compare TD SYNNEX's refinancing move with other balance-sheet-focused opportunities by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) for potential ideas beyond this stock.
TD SYNNEX Investment Narrative Recap
Owning TD SYNNEX means believing its scale in IT distribution and Hyve hyperscale projects can convert strong non GAAP billings into healthy, cash backed earnings. The analyst consensus narrative on Simply Wall St leans on digital transformation, AI infrastructure and an AI PC refresh cycle as the key drivers that could keep revenue and profit expanding.
The biggest near term swing factor is whether Hyve’s heavy working capital needs and thinner AI server margins ease. The new US$1.75b term loan extends maturities and adds flexibility, but does not on its own solve free cash flow pressure, so the core risk around cash conversion and margins remains very much in focus.
The fresh term loan is most relevant when set against TD SYNNEX’s current working capital strain at Hyve and the comment that debt is not well covered by operating cash flow. Longer dated, unsecured funding can reduce refinancing questions while management works on tightening the cash conversion cycle and improving program level profitability.
There is a clear link to the key catalysts in AI infrastructure and data center build outs. The facility earmarks capacity for acquisitions and broader corporate needs, which can support execution on AI, cloud and endpoint opportunities if deployed carefully. For shareholders, the real test now is disciplined use of this balance sheet headroom without letting leverage drift too high relative to EBITDA.
TD SYNNEX's narrative projects US$105.4b revenue and US$2.2b earnings by 2029. This projection is based on analyst assumptions of 11.7% yearly revenue growth and implies an earnings increase of about US$0.9b from US$1.3b today.
Uncover why TD SYNNEX's fair value indicates a 46% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus on customer concentration at Hyve instead of AI upside. They model TD SYNNEX reaching about US$87.2b revenue and US$1.6b earnings by 2029, which is well below the consensus path. Those forecasts were set before this new US$1.75b term loan, so views could shift as the balance sheet evolves.
Explore 2 other TD SYNNEX fair value estimates, including one that suggests it could be worth just $339.64!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your TD SYNNEX research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TD SYNNEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TD SYNNEX's overall financial health at a glance.
Looking for more TD SYNNEX sized opportunities?
If the TD SYNNEX story has sharpened your thinking on balance sheets, cash flow and growth, use that same lens across a wider watchlist with the Simply Wall St Screener.
- Prefer quality on sale and solid fundamentals? Scan a curated set of companies through 35 high quality undervalued stocks that might line up with that mindset.
- Want income to do more of the heavy lifting in your portfolio? Zero in on resilient payers using the 5 dividend fortresses as a starting universe.
- Care most about durability and capital strength? Filter for businesses with sturdy finances using the 30 resilient stocks with low risk scores to build a watchlist that fits that profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com