
SoFi Technologies (SOFI) Raised Guidance On Strong Results, Is It Still Below Fair Value?
SoFi Technologies (SOFI) is back in focus after reporting strong quarterly results that lifted adjusted net revenue to a record US$1.4b and beat earnings expectations, followed by higher guidance and fresh ARK Invest buying.
Recent trading tells a mixed story for SoFi Technologies. The share price is down about 40% year to date and the 1 year total shareholder return is lower at about 47%. However, the 3 year total shareholder return is up about 119%, which points to long term investors still sitting on very large gains while shorter term momentum has cooled, even after the latest earnings beat, raised guidance and fresh ARK Invest inflows.
Scan how SoFi Technologies compares with other fintechs shifting after earnings shocks and fresh institutional interest by reviewing our curated list of 35 high quality undervalued stocks.
SoFi Technologies now trades about 21% below the average analyst target even after the post earnings jump, while intrinsic value estimates point to a premium. Is the market’s caution on this rebound story misplaced, or is it a case of prudent restraint?
Most Popular Narrative: 7% Undervalued
On the most followed narrative, SoFi Technologies screens as slightly undervalued, with a fair value of about $17.60 versus the last close at $16.37, and that view comes from an investor focused on short term trading setups rather than long term holding.
The supports are wide and conservative because the stock is volatile. Over the last two years the chart has swung roughly from about $6 to a peak near $33, and it now trades around $16.40. Current levels: S1 $15.15 · S2 $11.45 · S3 $9.50 · S4 $6.62. The first entry sits relatively close to fair value; lower levels sit much further down.
See why 1 investors see SoFi Technologies as 7% undervalued.
The fair value in this narrative comes from a discounted cash flow style framework with an 8.17% discount rate. This approach places more weight on SoFi Technologies turning its current $737.861m of net income and $4.686b of revenue into future cash flows than on today’s share price moves. Under this lens, the recent drawdown in the stock and the 7% discount to the $17.60 estimate are treated as a pricing gap that matters more to traders watching levels like $15.15 and $11.45 than to investors who simply track the 3 year total shareholder return of about 119%.
Result: Fair Value of $17.60 (UNDERVALUED)
Still, if US rates or credit trends weaken, or if regulation tightens around SoFi Technologies’ banking activities, this pricing gap could close quickly.
Find out about the key risks to this SoFi Technologies narrative.
Another View: SoFi Technologies Looks Expensive On P/E
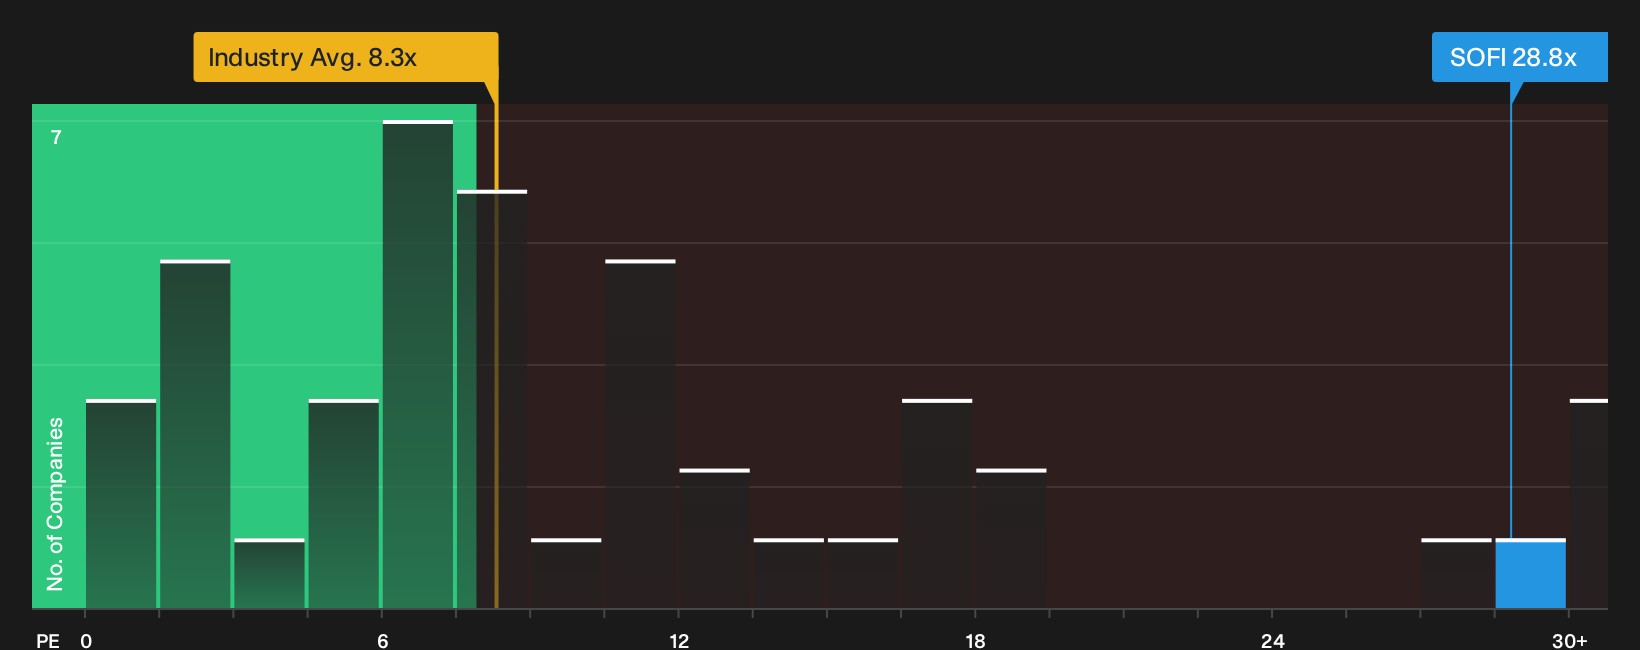
Through a simple earnings lens, SoFi Technologies tells a different story. The stock trades on a P/E of 28.8x, compared with about 10.4x for peers and a fair ratio of 20.5x. That leaves a rich premium and raises a blunt question for investors: How much optimism is already priced in?
Our valuation tools track this earnings-based view in detail for SoFi Technologies, breaking out where the market ratio currently sits versus that fair ratio level that prices could drift toward over time, so you can weigh whether the premium looks like risk or opportunity before making any move. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or fresh setup? If you want a clear read on SoFi Technologies instead of relying on headlines or targets, compare the competing risk and reward signals for yourself and see how they stack up against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SoFi Technologies?
If SoFi Technologies has sharpened your thinking, do not stop here. Broaden your watchlist with other targeted ideas that fit different goals and risk levels.
- Chase potential mispricings by scanning a focused group of 35 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect them yet.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can help anchor your holdings when conditions turn choppy.
- Get ahead of the crowd by tracking 20 high quality undiscovered gems before wider attention and liquidity start to reshape their pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com