
Quarterly Earnings Dip Could Be A Key Test For AutoNation Stock (AN)
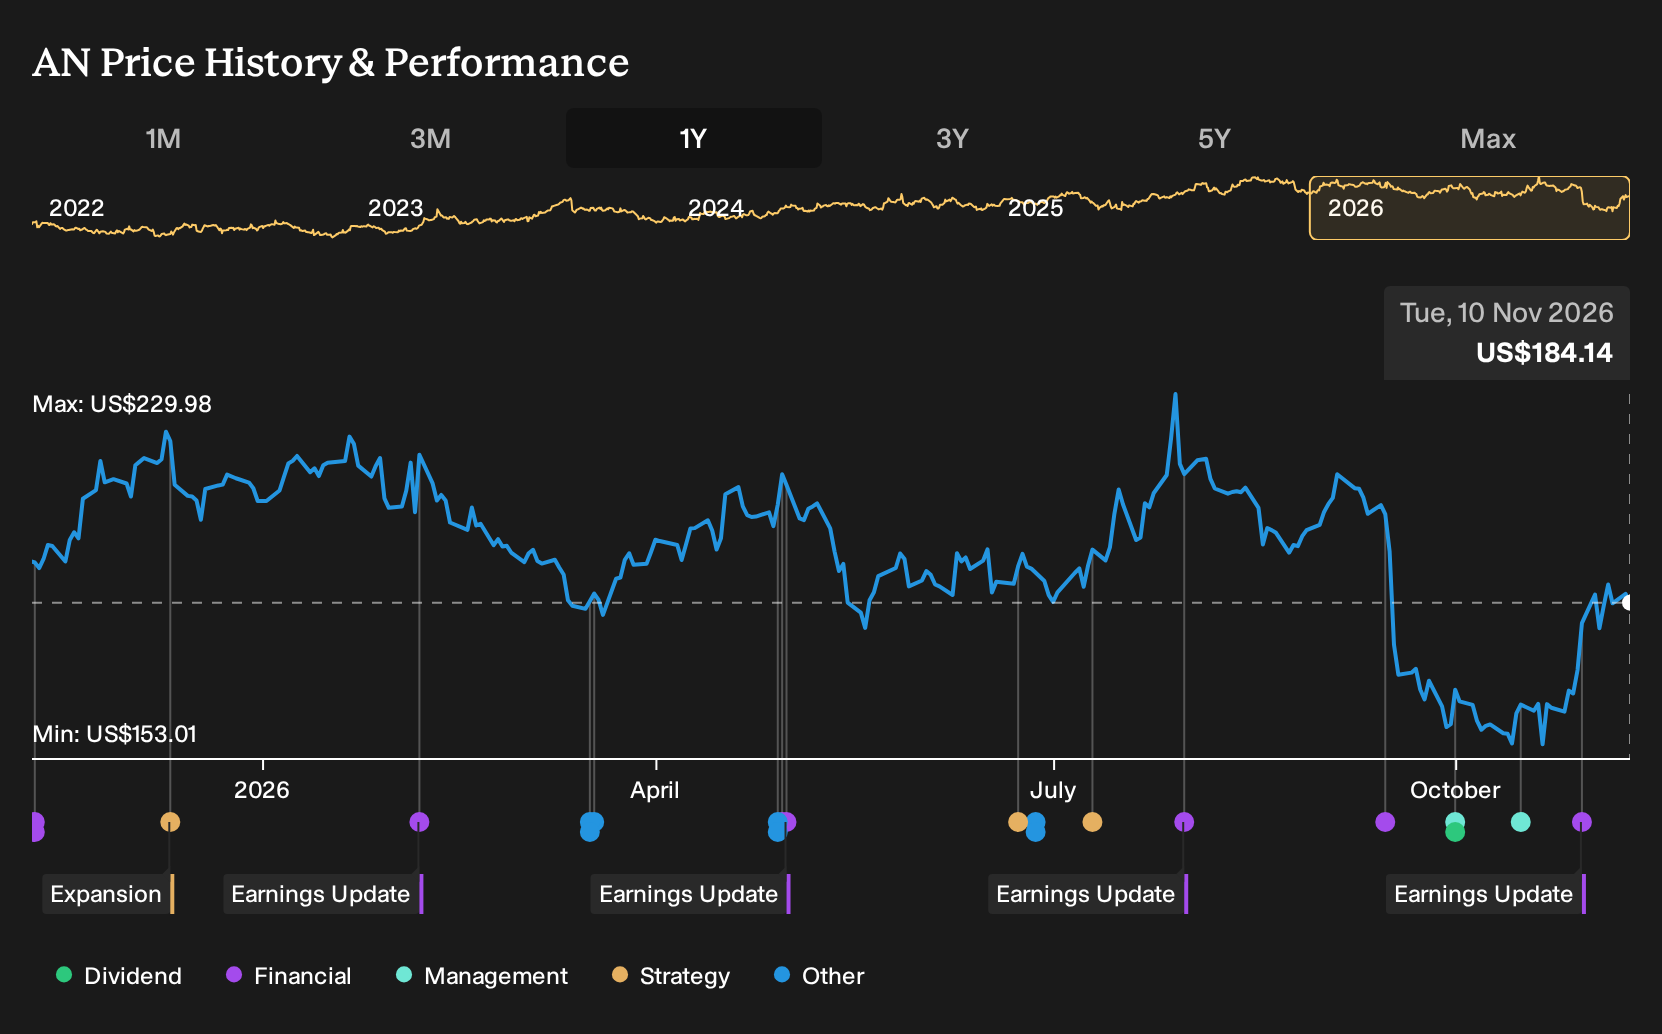
- AutoNation reported third quarter 2026 revenue of US$7,010.3 million and net income of US$162.3 million, with basic EPS from continuing operations of US$4.92.
- Across the first nine months of 2026, AutoNation recorded US$20,492.2 million in revenue and US$549.8 million in net income, while continuing to return cash through share repurchases.
- We will now assess how AutoNation's third quarter earnings mix, particularly nine-month profit trends, could influence the investment narrative.
Scan how AutoNation's latest earnings and ongoing buybacks compare with other operators returning cash to shareholders across our hand picked 5 dividend fortresses.
AutoNation Investment Narrative Recap
Owning AutoNation usually means you believe in the shift toward higher margin service, parts and finance rather than relying on selling more new cars. The analyst consensus Narrative on Simply Wall St focuses on that mix. This quarter’s softer quarterly profit and flat revenue suggest that the near term catalyst is execution in aftersales and AutoNation Finance, not volume growth.
The biggest swing factor right now is how resilient service and parts demand remains if customers continue to defer maintenance or use software fixes. Pressure on premium luxury demand and ongoing regulatory scrutiny around dealer practices are close behind as risks that could affect earnings quality and investor confidence.
The most relevant update here is AutoNation’s buyback activity. Between July 1 and October 28, 2026, the retailer retired 1,121,543 shares for US$210.96 million, which represented 3.39% of the business. That is in addition to a long running program that has taken out 175,308,722 shares for US$10,953.28 million since 2007.
This shrinking share count means the nine month earnings picture, with US$549.8 million of profit and US$16.31 basic EPS from continuing operations, flows through to higher earnings per remaining share. For you, the key question is whether AutoNation can continue to fund repurchases while managing debt coverage, softer quarterly profit and the operational risks around service growth, EV mix and compliance.
AutoNation's narrative projects US$30.2b revenue and US$829.7 million earnings by 2029. This projection assumes 3.3% yearly revenue growth and an earnings increase of about US$107.8 million from the current US$721.9 million.
Uncover why AutoNation's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on AutoNation’s credit risk rather than service momentum. The most bearish analysts already assumed slower revenue growth of 1.6% a year and 2029 earnings of about US$787.8 million before this quarter’s softer EPS. That group effectively sees the stock as fairly valued, which shows how far opinions can differ. Use this earnings and buyback update as a prompt to compare those cautious expectations with the more optimistic consensus before deciding which story you find more convincing.
Explore another AutoNation fair value estimate, including one that suggests it could be worth just $213.42.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your own analysis.
- A great starting point for your AutoNation research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AutoNation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoNation's overall financial health at a glance.
Looking for more AutoNation sized ideas?
If this AutoNation update has sharpened your thinking and you want to stress test that framework on other businesses, the Simply Wall St Screener lets you scan for stocks that fit very specific risk and quality filters in minutes rather than hours.
- If capital preservation sits high on your priority list, start with companies that score well on resilience and risk by reviewing the 30 resilient stocks with low risk scores.
- For readers hunting for quality at a reasonable price, focus on businesses that pair solid fundamentals with valuations flagged as potentially attractive across our 35 high quality undervalued stocks.
- Those who care most about balance sheet strength can zero in on companies with robust financial footing through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com