
Do Wall Street Analysts Like American Tower Stock?
Boston, Massachusetts-based American Tower Corporation (AMT) is a leading independent REIT that owns, operates, and develops multitenant communications real estate with a portfolio of nearly 149,000 communications sites and a highly interconnected footprint of U.S. data center facilities. With a market cap of $88.3 billion, the company leases antennae sites on multi-tenant towers for a diverse range of wireless communications industries, including personal communications services, paging, and cellular.
Shares of this leading REIT have underperformed the broader market over the past year. AMT has gained 5.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.1%. In 2026, AMT stock is up 8.4%, compared to the SPX’s 9.9% rise on a YTD basis.
Narrowing the focus, AMT’s outperformance is apparent compared to the Pacer Data & Infrastructure Real Estate ETF (SRVR). The exchange-traded fund has declined about 6.6% over the past year. Moreover, the stock’s single-digit returns on a YTD basis outshine the ETF’s marginal dip over the same time frame.
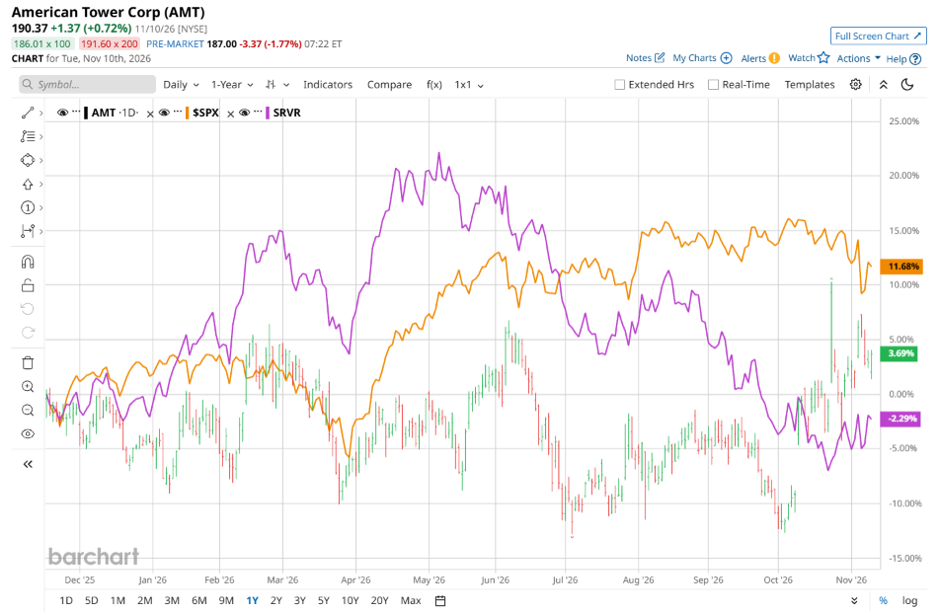
AMT’s mixed performance reflects a tug-of-war between steady foundational growth and persistent macroeconomic headwinds. While the company's data center segment has delivered exceptional growth and core property operations continue to benefit from steady long-term wireless carrier demand, overall momentum has been constrained. Softer domestic tower leasing activity, sluggish services revenue, and foreign exchange headwinds from its extensive international portfolio have kept gains modest, leaving the stock lagging behind broader equity benchmarks even as it maintains a resilient operational core.
On Oct. 27, AMT shares closed down more than 2% after reporting its Q3 results. Its FFO of $2.87 per share surpassed Wall Street expectations of $2.84 per share. The company’s revenue was $2.79 billion, topping Wall Street forecasts of $2.77 billion. AMT expects full-year FFO in the range of $11.04 to $11.16 per share.
For the current fiscal year, ending in December, analysts expect AMT’s FFO per share to grow marginally to $10.80 on a diluted basis. The company’s FFO surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 24 analysts covering AMT stock, the consensus is a “Strong Buy.” That’s based on 19 “Strong Buy” ratings, two “Moderate Buys,” and three “Holds.”
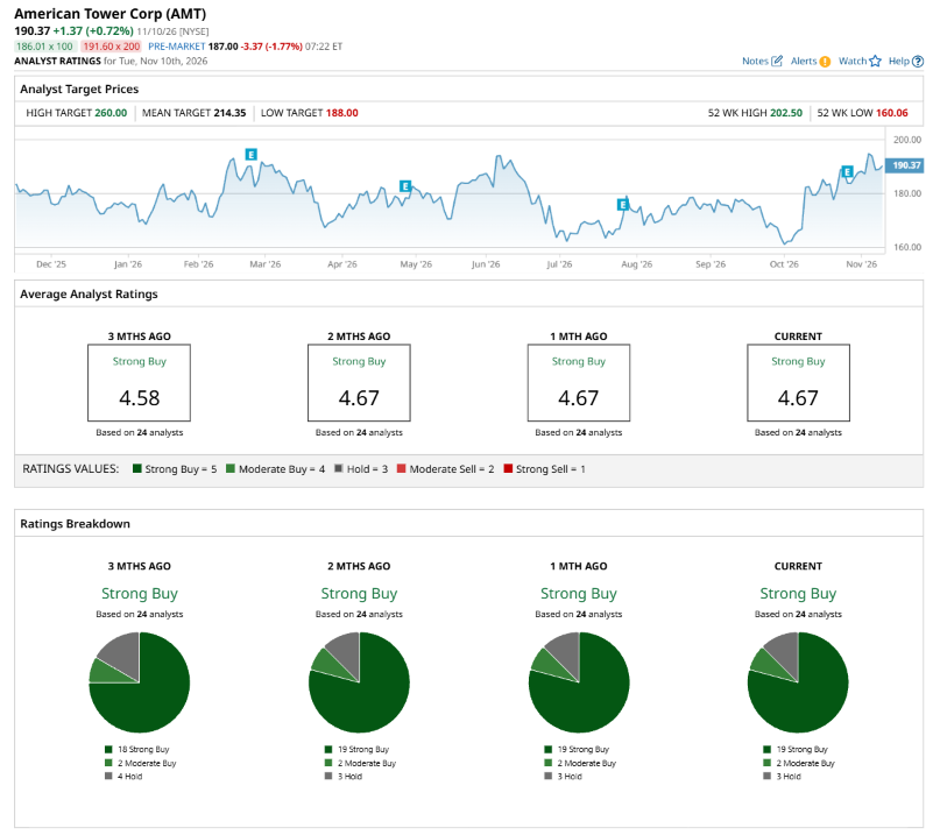
This configuration is more bullish than three months ago, with 18 analysts suggesting a “Strong Buy.”
On Nov. 4, Argus Research analyst Marie Ferguson reiterated a “Buy” rating on AMT and set a price target of $210, implying a potential upside of 10.3% from current levels.
The mean price target of $214.35 represents a 12.6% premium to AMT’s current price levels. The Street-high price target of $260 suggests a notable upside potential of 36.6%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.