
How Investors May Respond To Zimmer Biomet Stock Surgeon Guided Autonomy Launch
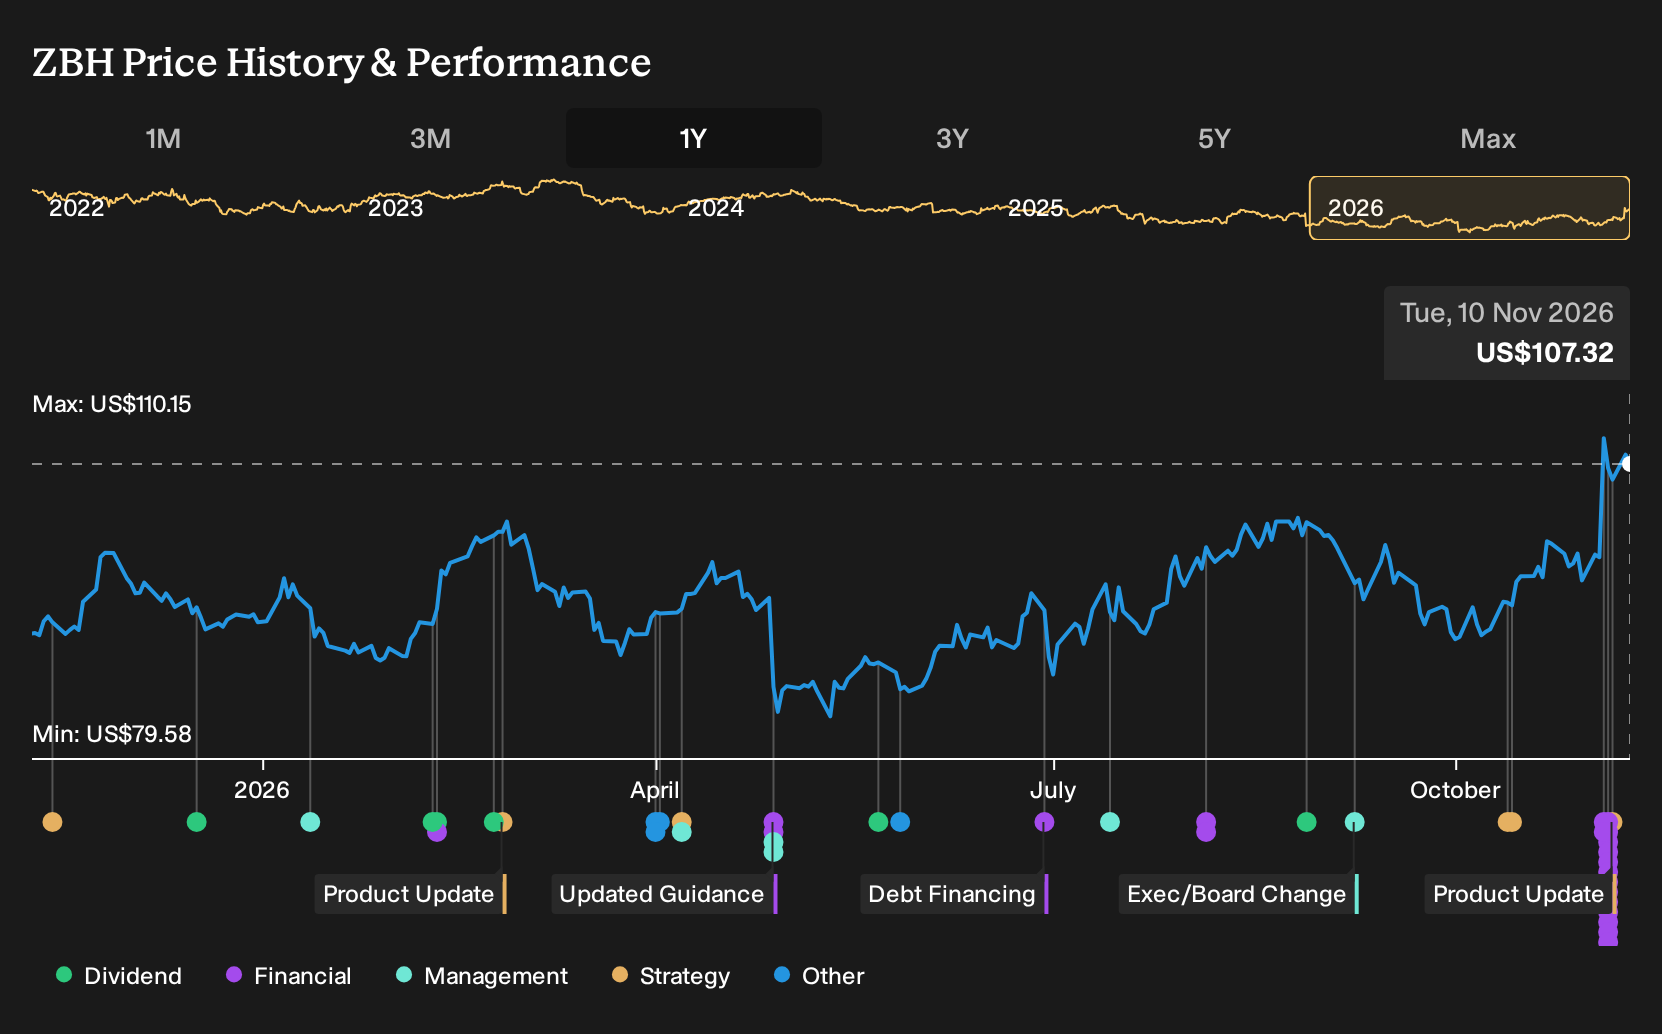
- Zimmer Biomet Holdings introduced its Surgeon-Guided Autonomy vision for intelligent orthopedic surgery and reported Q3 2026 results with US$2,062.9 million in sales and US$191.6 million in net income, alongside higher full year 2026 reported revenue guidance of 4.4% to 4.9%.
- The push into Surgeon-Guided Autonomy, framed around the Predict, Perform, Recover loop and tied to the Technology & Data portfolio, reinforces Zimmer Biomet’s effort to link higher value digital platforms with its core joint replacement hardware.
- We will examine how Zimmer Biomet's updated investment narrative is influenced by the Surgeon-Guided Autonomy launch in orthopedic surgery.
Scan Zimmer Biomet Holdings alongside other orthopedic and medtech players that combine robotics, data and hardware in our curated 36 healthcare AI stocks for this space.
Zimmer Biomet Holdings Investment Narrative Recap
To own Zimmer Biomet Holdings, you need to believe the shift toward robotics, data and Surgeon-Guided Autonomy can offset pricing pressure and near-term margin strain. Q3 2026 showed US$2,062.9 million in sales and US$191.6 million in net income, plus slightly higher full-year revenue guidance, which supports that technology-led mix shift thesis.
The near-term catalyst remains execution on Project Optima and the broader cost reset, while maintaining procedure volumes and technology adoption. The biggest risk is that pricing and reimbursement headwinds, together with higher manufacturing and commercial costs, continue to pressure margins so earnings lag revenue even as Surgeon-Guided Autonomy rolls out.
The most relevant announcement alongside Surgeon-Guided Autonomy is the pair of new fixed-rate note offerings totaling roughly US$1.5 billion equivalent. This includes US$499.965 million of 5.850% notes due 2036 and €499.97 million of 4.375% notes due 2033. These instruments are senior, unsecured and unsubordinated, with callable features disclosed.
For you as an investor, these bonds matter because Zimmer Biomet is already flagged in the analyst consensus Narrative on Simply Wall St as having a high level of debt and relying on higher-risk funding. Fresh fixed income issuance can support ongoing investments in technology, manufacturing and Project Optima, but it keeps balance sheet discipline and interest expense squarely in focus as you weigh the Surgeon-Guided Autonomy catalyst against financial risk.
Zimmer Biomet Holdings' narrative projects US$9.5b revenue and US$1.4b earnings by 2029. This aligns with analysts assuming 3.4% yearly revenue growth and an earnings increase of about US$632.6m from US$767.4m today.
Uncover why Zimmer Biomet Holdings' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$115.6 to US$200.5, which shows how far apart retail views on Zimmer Biomet Holdings can be. Set that against pricing pressure, margin strain and fresh bond issuance, and you are weighing Surgeon-Guided Autonomy and Project Optima against balance sheet and execution risk.
Explore 3 other Zimmer Biomet Holdings fair value estimates, including one that suggests as much as 87% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zimmer Biomet Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Zimmer Biomet Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zimmer Biomet Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Zimmer Biomet Holdings?
Once you have a view on Zimmer Biomet Holdings, it can help to compare that thesis with other companies that share similar quality, income or risk characteristics using the Simply Wall St Screener.
- For investors willing to take on higher risk in search of bigger potential swings, review our curated set of 10 elite penny stocks with strong financials that meet strict financial filters.
- If capital preservation and steady fundamentals matter most to you, focus on companies with stronger balance sheets using this targeted list of solid balance sheet and fundamentals (24 results).
- For those hunting for underappreciated opportunities, scan a broader pool of quality businesses that our filters flag as potentially mispriced through the 35 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com