
WPP (LSE:WPP) Why Is It Getting Fresh Attention Now?
Recent recognition of WPP (LSE:WPP) in Forrester’s media services report, together with its Elevate28 restructuring and AI investment plan, has put fresh attention on how the advertising group’s strategy lines up with the current share price.
At a share price of £4.152, WPP has logged a 30-day share price return of 7.59% and a year to date share price gain of 23.02%, while the 1-year total shareholder return of 43.84% contrasts with a 3-year total shareholder return that is down 31.69% and a 5-year total shareholder return that is down 51.57%. This points to improving momentum recently after a much tougher stretch for longer term holders, as Elevate28, AI investment plans and industry debate with rivals keep the story in focus.
Surf 16 high quality undervalued stocks that, like WPP, are wrestling with AI adoption and restructuring, yet could be setting up for the next leg of momentum.Recent gains have pushed WPP close to the average analyst target, yet its own intrinsic value estimate remains at a much lower level. Where does fair value really land in that gap?
Most Popular Narrative: 3% Overvalued
Against a last close of £4.15 for WPP, the analyst consensus Narrative on Simply Wall St anchors fair value at £4.02 using a 13.49% discount rate. This implies the market is paying a small premium for that outlook.
The main thing that has to go right is that WPP’s Elevate28 restructuring and WPP Production model turn integrated wins, AI-infused high-velocity content and cost savings into sustained improvements in net sales mix and profitability, despite recent declines in like for like net sales.
See why 44 investors see WPP as 3% overvalued.
Result: Fair Value of £4.02 (OVERVALUED)
Still, prolonged declines in like-for-like net sales and pressure from weaker consumer packaged goods and technology client spending could quickly undermine the current WPP fair value story.
Find out about the key risks to this WPP narrative.
Another View: What Multiples Say About WPP
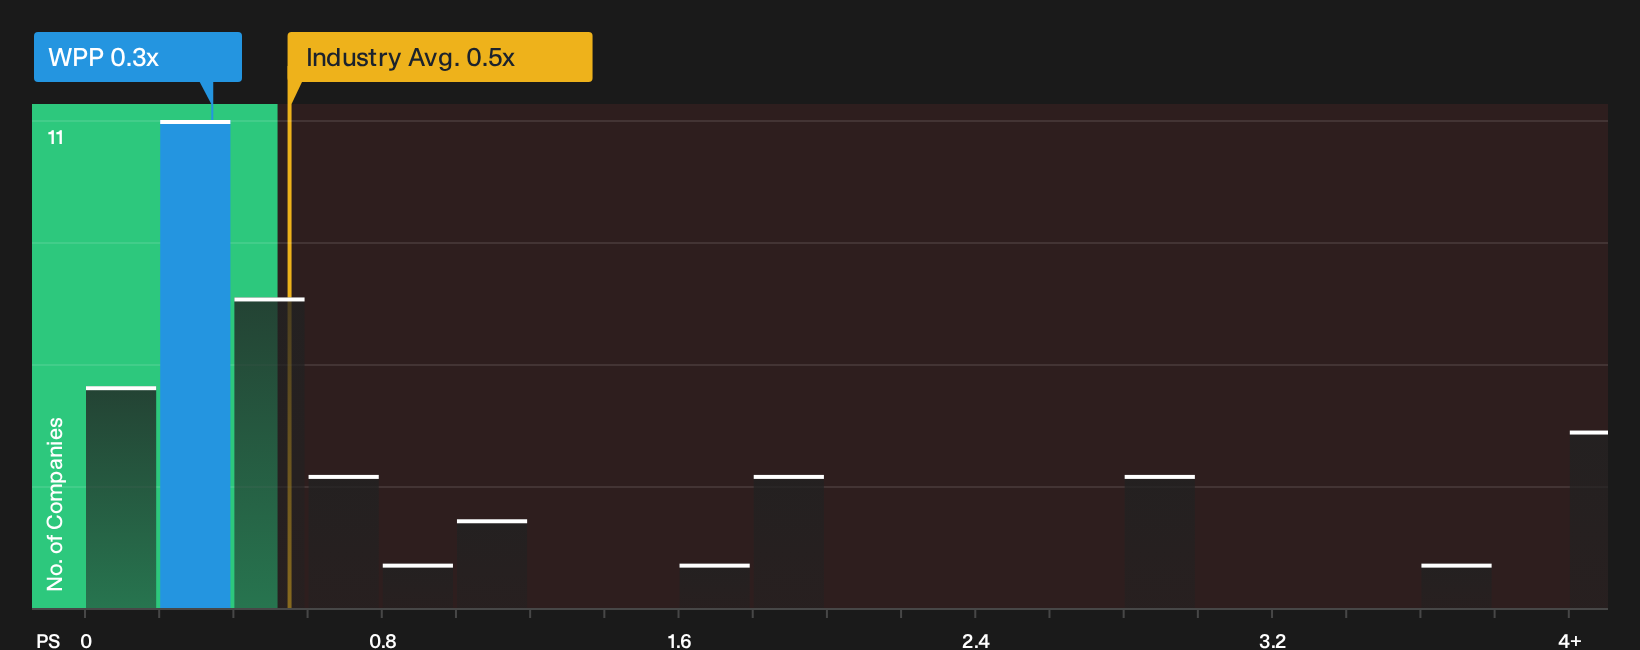
While the Simply Wall St fair value of £4.02 suggests WPP is slightly overvalued, the market is pricing the shares at only 0.3x P/S against a fair ratio of 1.1x and a UK media sector level of 0.5x. This points to a very different signal on valuation risk and potential upside.
Put simply, the P/S gap indicates that the market is paying a much lower price for each pound of WPP revenue than both peers and the fair ratio imply. The key question for investors is whether that discount reflects temporary worry or a deeper concern about future sales and margins.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on WPP and its valuation can cut both ways, so move quickly, test the numbers yourself and weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WPP?
If WPP has sharpened your focus on valuation, do not stop here. Use targeted screeners to spot other setups before they move without you.
- Target potential value with stronger fundamentals by running a focused search through the 16 high quality undervalued stocks.
- Strengthen your watchlist with companies that aim for resilience and cleaner balance sheets by filtering through the list of solid balance sheet and fundamentals (9 results).
- Hunt for lesser known opportunities with quality metrics on your side by scanning the 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com