
Dear Cisco Stock Fans, Mark Your Calendars for November 12
Cisco Systems (CSCO) is heading into a closely watched earnings event on Thursday, Nov. 12, when the networking giant is scheduled to report its first-quarter fiscal 2027 results after the market close. Investors will be looking beyond the headline numbers for signs that the company’s AI-driven networking opportunity remains on track, particularly after Cisco reported strong AI infrastructure demand and raised its full-year outlook in August.
Cisco currently expects Q1 FY2027 revenue of $18.0 billion to $18.2 billion and non-GAAP EPS of $1.32 to $1.34, while full-year revenue is projected at $72.2 billion to $73.4 billion.
The earnings report also comes at a pivotal moment for CSCO stock. Shares have recently faced pressure after Morgan Stanley downgraded Cisco to “Equal-weight” from “Overweight” and cut its price target to $120 from $135, citing pull-forward risks from planned price increases and potential gross-margin pressure from a growing mix of lower-margin hyperscaler hardware.
With Wall Street still broadly bullish but expectations elevated, Cisco’s latest results and management commentary could provide an important catalyst for the stock.
About Cisco Stock
Cisco Systems is a global technology company headquartered in San Jose, California, that develops networking hardware, cybersecurity, collaboration, observability, and AI-driven infrastructure solutions for enterprises, governments, and service providers. The company has evolved from its networking roots into a leading provider of secure connectivity and AI-era digital infrastructure, with a growing focus on software and subscription-based services. Cisco has a market cap of $388.9 billion, making it one of the world’s largest technology companies.
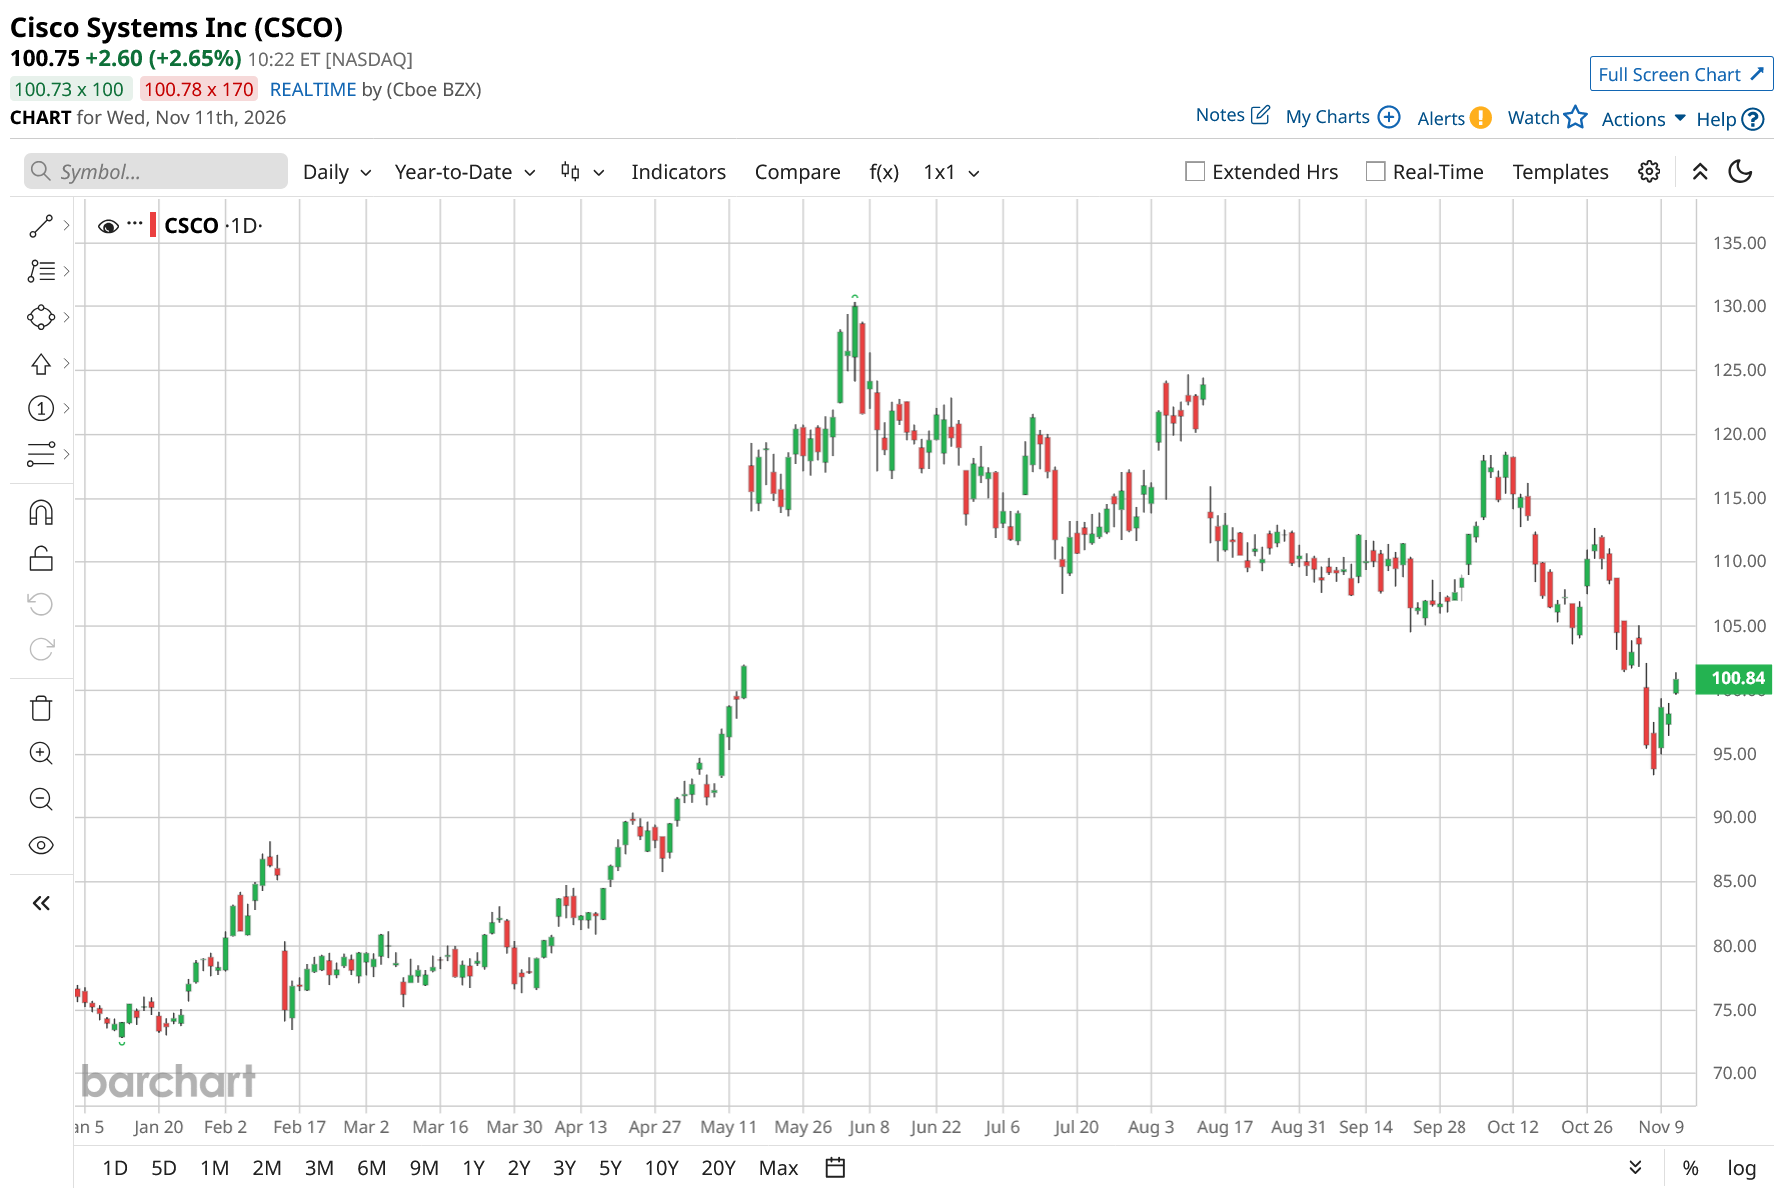
Cisco Systems has delivered strong gains over the longer term, but the stock has come under significant pressure ahead of its fiscal first-quarter earnings report on Nov. 12. CSCO has returned 40% over the past year and gained 30% year-to-date (YTD), reflecting investor optimism around the company’s growing exposure to AI infrastructure, hyperscale customers, and data center networking. However, the recent trend has been much weaker, with the stock down 15% over the past month as investors have become increasingly concerned about valuation, AI-related gross-margin pressure, and whether strong expectations are already reflected in the share price.
Moreover, the selling intensified last week. Cisco shares slumped 7.6% on Nov. 5 after Morgan Stanley downgraded the stock and reduced its price target to $120 from $135. The firm argued that Cisco’s strong rally had reduced the room for further upside and highlighted the risk that customers could pull forward orders ahead of planned price increases. Morgan Stanley also warned that Cisco’s growing mix of lower-margin hardware sold to hyperscalers could weigh on gross margins as the company expands its AI infrastructure business. The stock then fell another 2% on Nov. 6, closing at $93.85, before staging a sharp 5.1% rebound on Nov. 9 to $98.65. As of this morning's trading, CSCO has risen almost 3% and is now above the $100 mark.
The rebound suggests that investors may be viewing the recent weakness as an opportunity to reassess Cisco ahead of earnings rather than abandoning the AI-networking story altogether. With the stock still substantially higher over the past year despite its recent pullback, the Nov. 12 earnings report could be critical in determining whether CSCO can resume its upward trend or remains under pressure.
The stock is currently trading at 21.65 times forward earnings, which is a modest discount to industry peers, while in terms of price-to-sales (P/S) of 5.96, the stock seems to be trading at a premium.
Q4 and FY2026 Results Set a High Bar for November Earnings
Cisco delivered a strong finish to fiscal 2026, reporting its fourth-quarter and full-year results on Aug. 12. The networking giant posted record quarterly revenue and earnings, with results exceeding the high end of its previous guidance. Q4 revenue rose 18% year-over-year (YoY) to $17.3 billion, while on a non-GAAP basis, net income increased 23% to $4.9 billion, while adjusted EPS rose 23% to $1.22 from $0.99. Its operating income climbed 38% to $4.3 billion, and the operating margin expanded to 24.7% from 21%. Operating cash flow also increased 27% YoY to $5.4 billion.
The strength was led by Cisco’s product business, with product revenue increasing 24%, while services revenue was essentially flat. Networking revenue jumped 28%, Security revenue increased 14%, Collaboration rose 12%, and Observability grew 6%.
Meanwhile, Cisco’s Q4 total product orders increased 35% YoY, while networking product orders surged 40%, marking the eighth consecutive quarter of double-digit growth. The company also recorded $4 billion of AI infrastructure orders during Q4, bringing full-year AI infrastructure orders to $9.3 billion.
For fiscal 2026, Cisco’s revenue increased 12% to $63.3 billion, while non-GAAP net income rose 13% to $17.2 billion, and adjusted EPS increased to $4.33 from $3.81. Full-year networking revenue was particularly impressive, rising 22% to $34.7 billion, while Security grew 2% to $8.2 billion, Collaboration increased 4% to $4.3 billion, and Observability rose 4% to $1.1 billion.
Furthermore, for the first quarter of fiscal 2027, management guided for revenue of $18 billion to $18.2 billion and non-GAAP EPS of $1.32 to $1.34. For the full fiscal year, Cisco expects revenue of $72.2 billion to $73.4 billion and non-GAAP EPS of $5.05 to $5.11. The company also expects $7.5 billion of AI infrastructure revenue in fiscal 2027, nearly double the roughly $4 billion delivered in fiscal 2026.
In addition, analysts are forecasting EPS of around $4.42 for fiscal 2027, a 21.4% YoY jump, and a 8.6% rise to $4.80 in 2028. The consensus EPS estimate of $1.15 for the first quarter of 2027 indicates a 42% rise YoY.
What Do Analysts Expect for CSCO Stock?
In addition to Morgan Stanley taking a neutral stance, Bernstein analyst Peter Weed also recently reiterated a “Hold” rating on CSCO stock with a $110 price target. This reflects Bernstein’s cautious stance on CSCO despite the firm’s recognition that networking companies stand to benefit from sustained AI infrastructure spending.
On the other hand, on Nov. 3, Bank of America Securities analyst Tal Liani maintained a “Buy” rating on Cisco Systems and a $150 price target ahead of the company’s fiscal first-quarter earnings report. The unchanged target reflected the firm’s continued bullish view of Cisco’s AI-driven networking opportunity and long-term growth prospects.
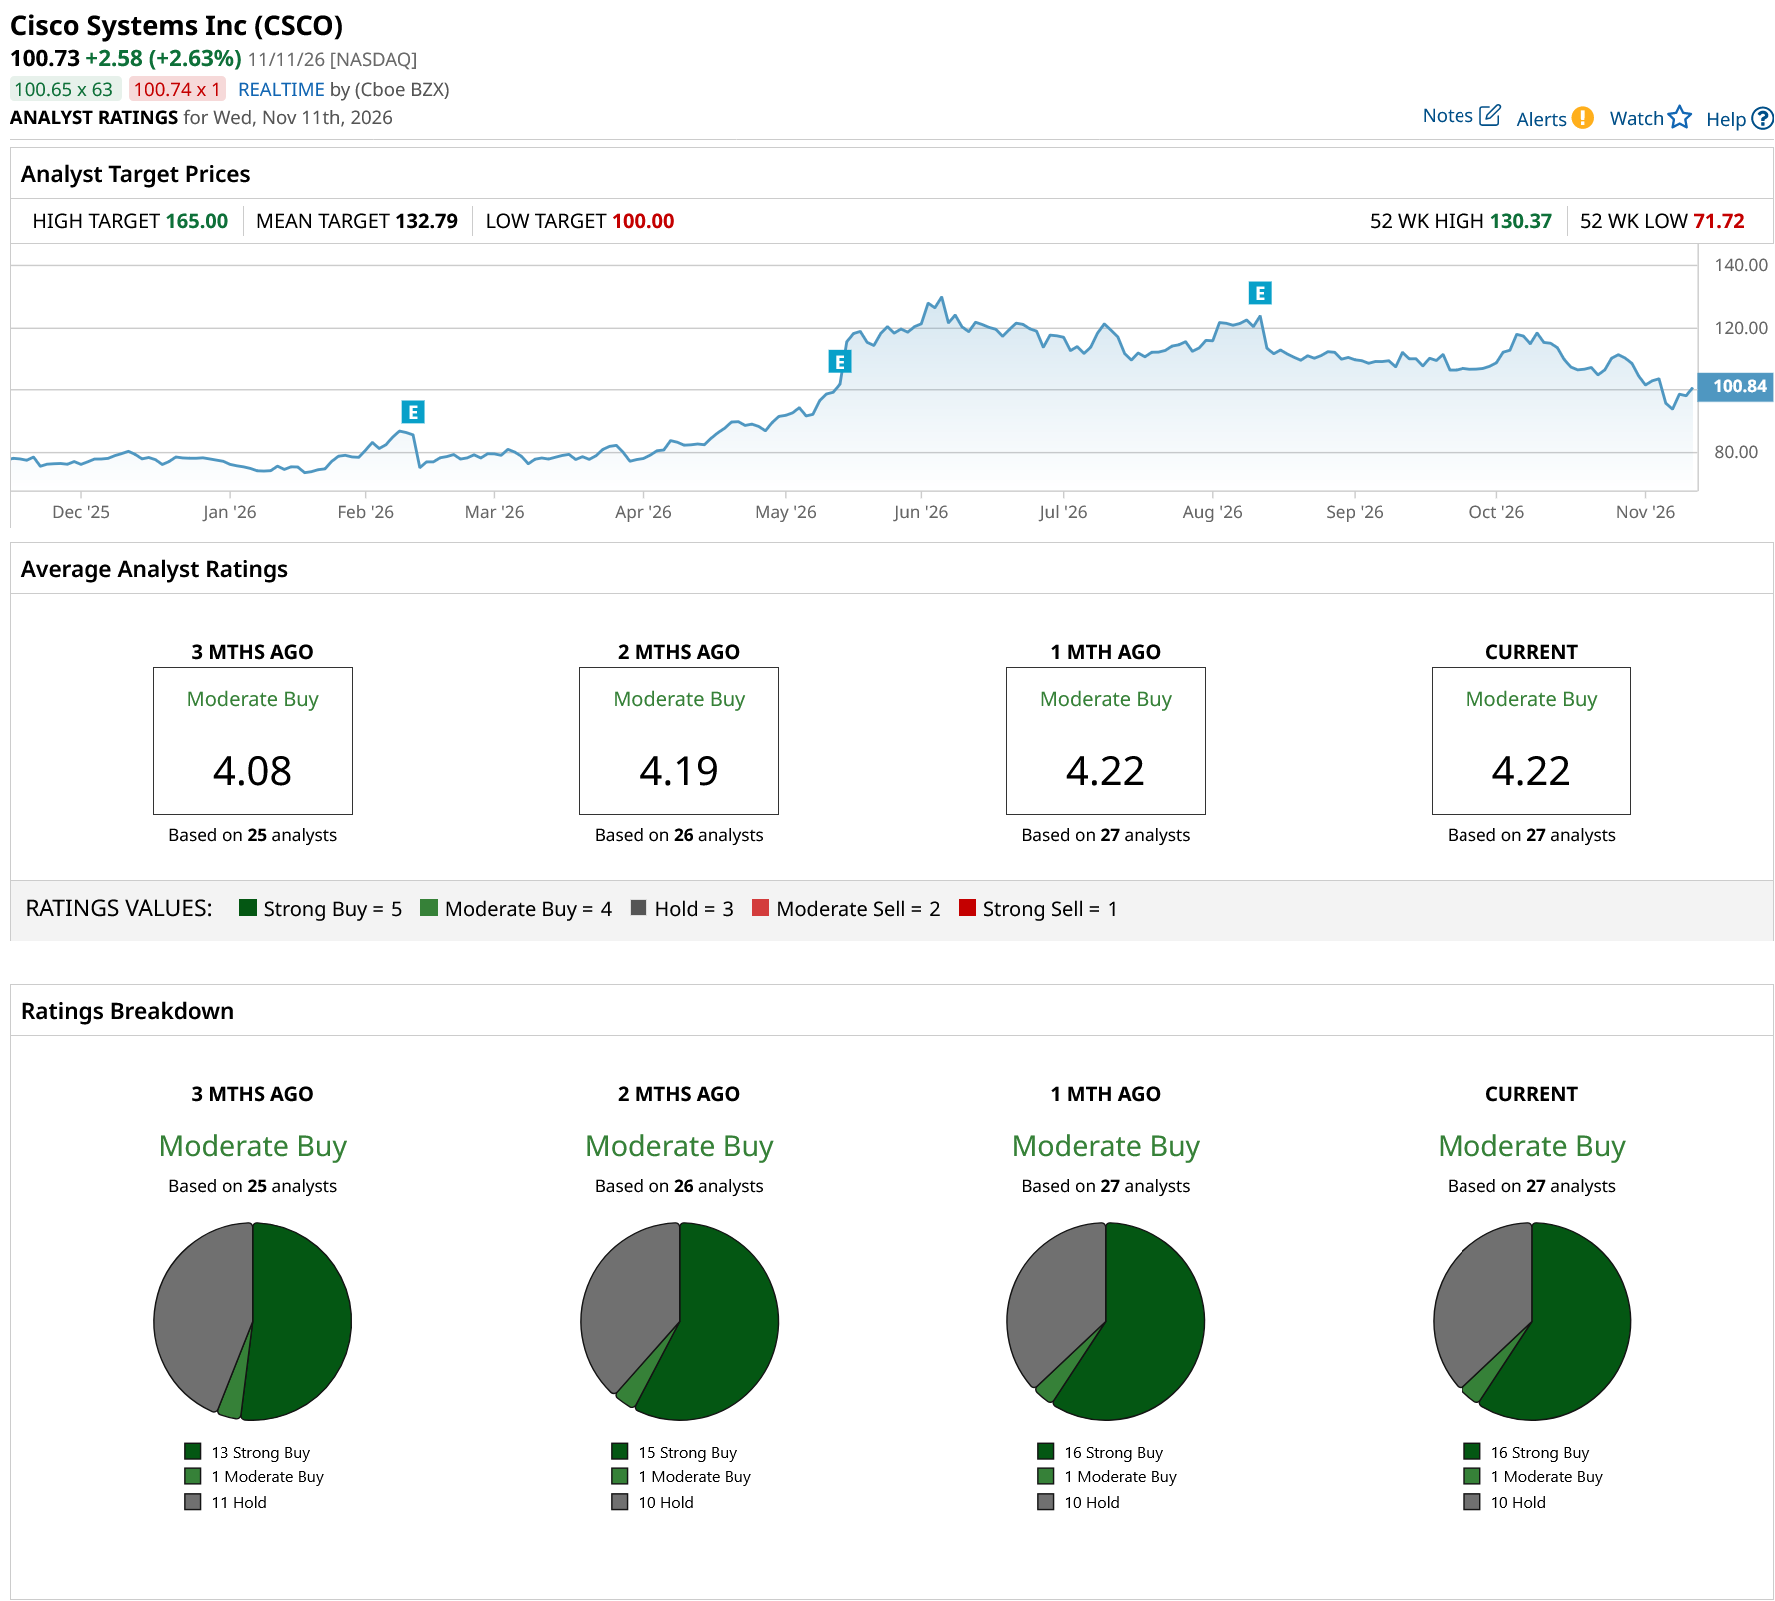
Overall, CSCO stock has a consensus “Moderate Buy” rating. Of the 27 analysts covering the stock, 16 advise a “Strong Buy,” one suggests a “Moderate Buy,” and the remaining 10 analysts are on the sidelines, giving it a “Hold” rating.
CSCO’s average analyst price target of $132.79 indicates an upside of 32%, while the Street-high target price of $165 suggests that the stock could rally as much as 64%.
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.