
Ensign Group (ENSG) Faces Lawsuit Scrutiny, Is It Still Below Fair Value?
Ensign Group (ENSG) is back under the microscope after a securities class action lawsuit accused the operator and certain executives of misleading investors, following reports of patient neglect, understaffing and manipulated quality and billing data.
At a share price of US$185.09, Ensign Group has seen short term pressure around the lawsuit headlines, with a 7 day share price return of a 1.71% decline. At the same time, a 6.42% share price gain year to date and a 127.8% total shareholder return over five years point to strong longer run momentum that investors now have to weigh against rising legal and regulatory risk.
Stress test your thesis on Ensign Group by comparing it with other healthcare operators that screen well on balance sheet strength and fundamentals using our curated list of solid balance sheet and fundamentals (24 results).
Ensign Group has a long record of shareholder gains, yet the latest legal overhang and recent wobble in the share price raise a sharper question: Does US$185 already fully reflect both the strength and the new risks, or not?
Most Popular Narrative: 18% Undervalued
At a last close of $185.09 versus an analyst consensus fair value of $225.80, the analyst consensus Narrative on Simply Wall St frames Ensign Group as materially undervalued, using detailed assumptions about future growth, margins and risk. That framework leans on specific operational drivers rather than sentiment alone, which matters when headlines are dominated by legal claims.
A sizeable pipeline of low occupancy, clinically challenged acquisitions, particularly in Texas, creates room for operational turnaround using the existing cluster and ONE CLINICAL model, which can affect occupancy driven revenue and EBIT over multi year periods.
See why 1 investors see Ensign Group as 18% undervalued.
Result: Fair Value of $225.80 (UNDERVALUED)
Still, the narrative around Ensign Group hinges on two pressure points: heavier legal scrutiny after the class actions and the risk that Medicare or Medicaid funding terms become less favorable.
Find out about the key risks to this Ensign Group narrative.
Another View on Ensign Group’s Valuation
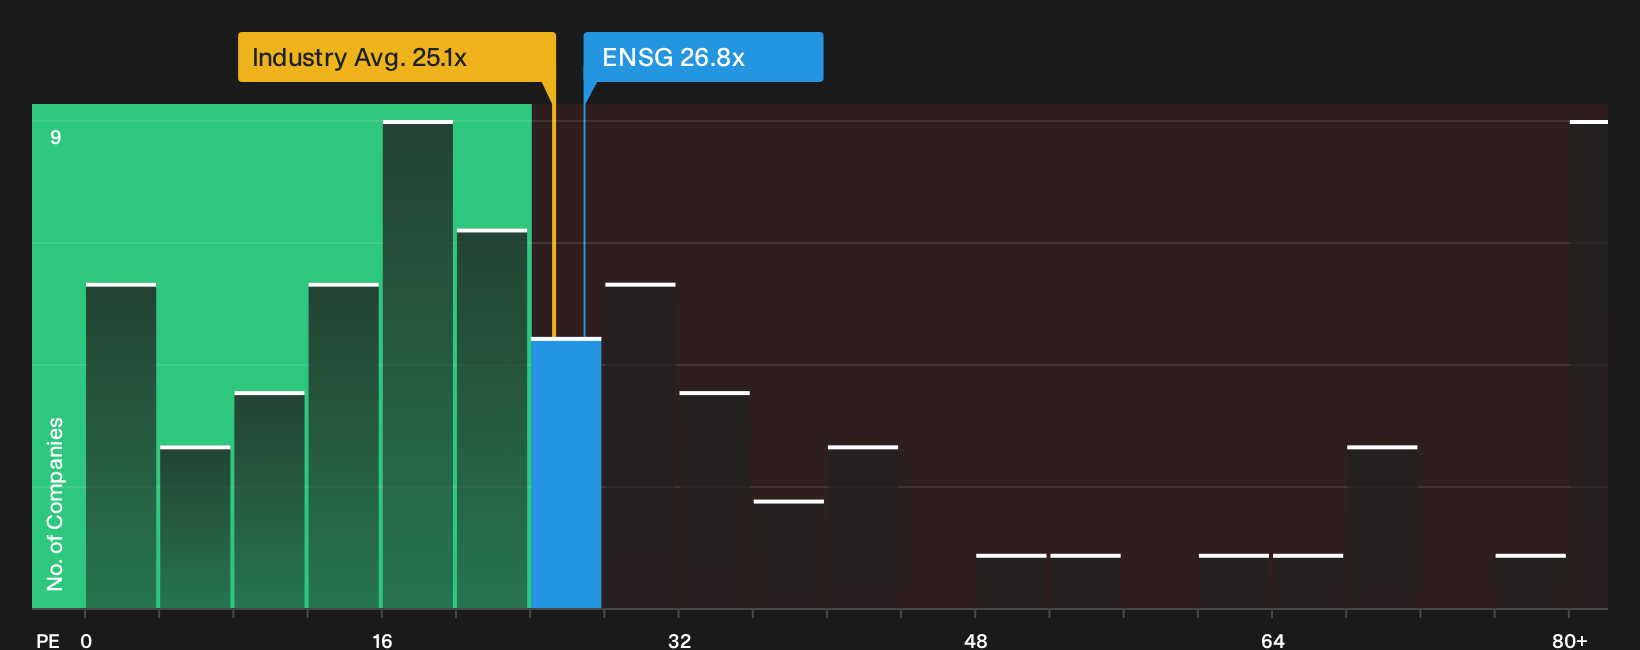
On the simple earnings yardstick, Ensign Group looks less generous. The stock trades on a P/E of 26.8x compared with 20.9x for peers and 25.3x for the broader US Healthcare group, even though its fair ratio is estimated at 27.4x. This keeps valuation risk very real if sentiment turns.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece on Ensign Group may feel mixed, so act quickly and pressure test the positives and negatives against your own judgment. To see what is currently driving optimism in the story, start by reviewing the 3 key rewards.
Looking for more investment ideas beyond Ensign Group?
Do not stop at Ensign Group. Broaden your watchlist now with fresh ideas filtered by quality, resilience and income so you are not chasing the crowd later.
- Target potential upside by focusing on businesses that combine quality fundamentals with attractive prices through our carefully built 35 high quality undervalued stocks.
- Strengthen your downside protection by scanning for companies that score well on financial resilience using the focused 30 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking under followed opportunities with solid fundamentals in the hand picked 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com