
What Jacobs Solutions Shares Major Contract Wins Mean For Shareholders
- Jacobs Solutions recently announced a series of large contract awards, including design and delivery roles on New Zealand’s Northland Corridor highway, American Electric Power’s US$37b transmission investment program across seven US states, and a US$1b nutrient reduction upgrade at San Francisco’s Southeast Treatment Plant.
- These wins expand Jacobs Solutions’ exposure to long duration transportation, power grid and wastewater projects, tying the consulting and engineering portfolio more tightly to critical infrastructure spending and complex, multi year execution work.
- We will now look at how Jacobs Solutions’ investment narrative could be shaped by its expanded role in American Electric Power’s transmission program.
Scan a curated set of infrastructure focused engineering and utilities contractors by checking out the 42 power grid technology and infrastructure stocks. These companies could also benefit from long duration grid and project delivery spending alongside Jacobs Solutions.
Jacobs Solutions Investment Narrative Recap
To own Jacobs Solutions, you need to believe the record US$29b backlog and the growth areas described in the analyst consensus Narrative on Simply Wall St can translate into higher quality earnings, not just more projects. The recent wins in highways, transmission and wastewater point to more long duration work that could support that story.
The near term swing factor still sits in execution and margins. Management is running programs aimed at lifting EBITDA margins toward 17% by fiscal 2029. Current profit margins are 2.5%, below last year’s 4.1%. Heavy exposure to public infrastructure budgets remains the clearest operational risk if priorities or funding change.
The American Electric Power collaboration looks most relevant for today’s catalyst mix. Jacobs Solutions is embedded across project management, engineering, siting and environmental work for a US$37b transmission program, giving it a broad role across seven states rather than a single asset or one off mandate.
That breadth ties directly into the thesis that critical infrastructure can support multi year revenue and margin improvement, alongside AI data centers and advanced facilities. The scale and duration of the American Electric Power portfolio also highlight the key risk. Any pause in utility or regulatory approvals could slow backlog conversion even if headline awards look strong.
Jacobs Solutions' narrative projects US$17.5b revenue and US$1.2b earnings by 2029, which rests on analysts' assumptions of 7.1% yearly revenue growth and an earnings increase of about US$840.7m from US$359.3m today.
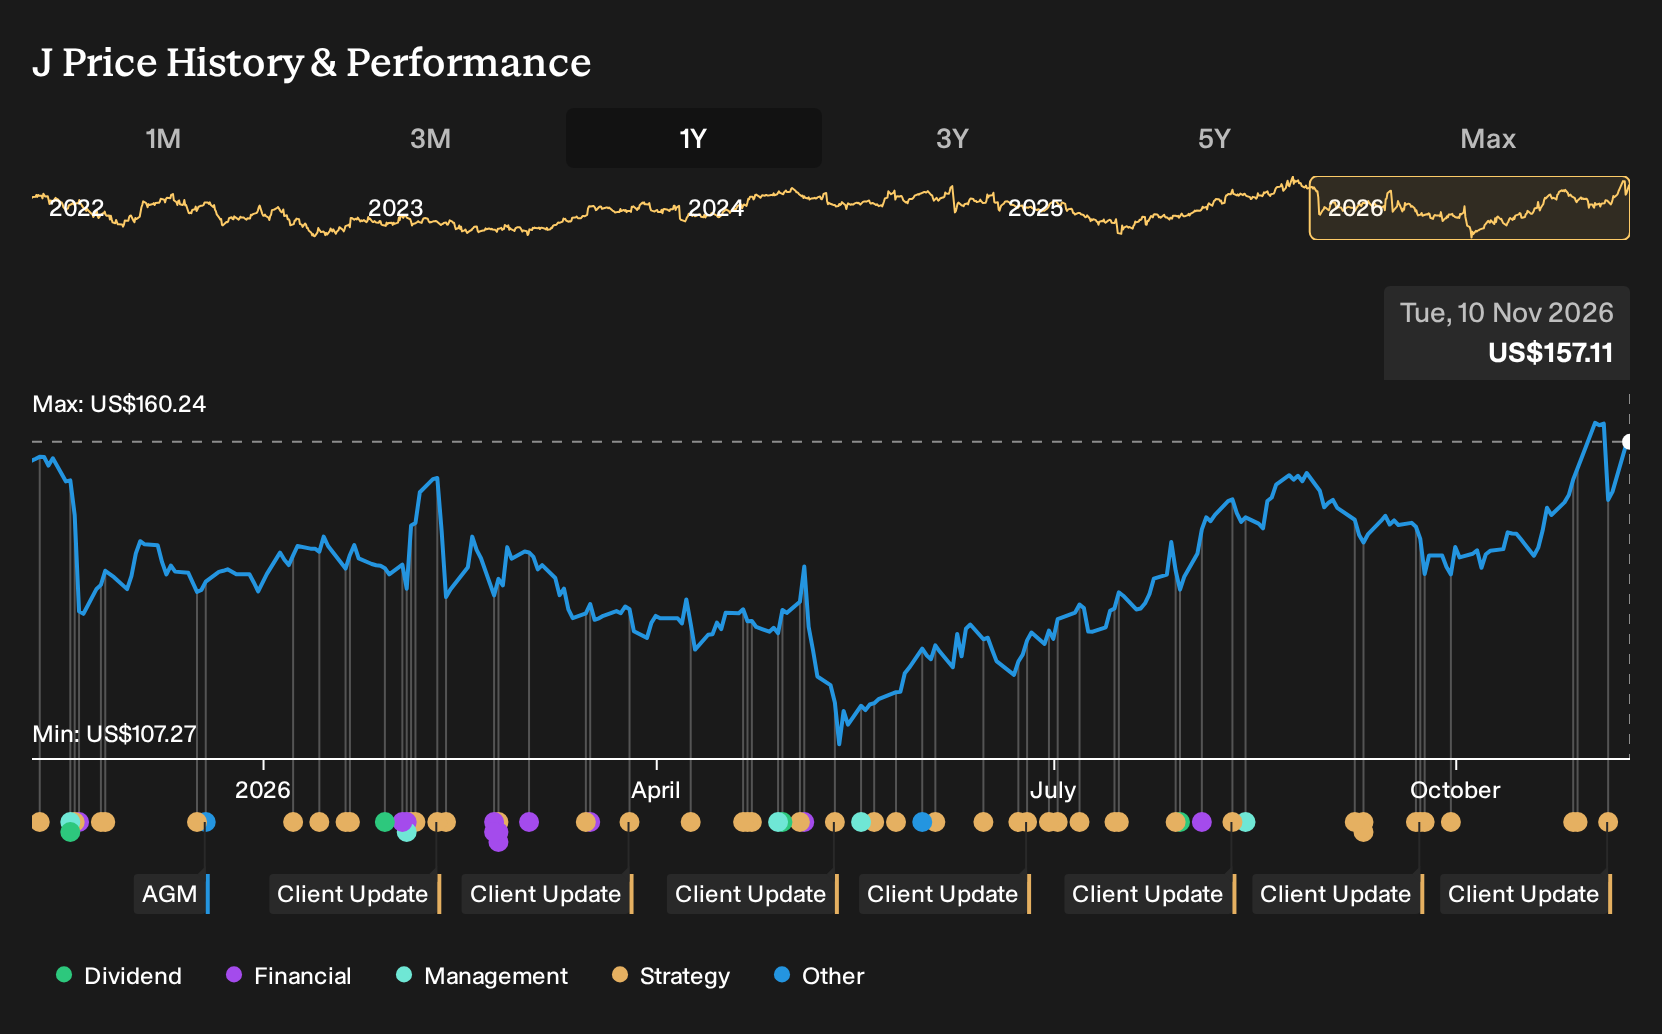
Uncover how Jacobs Solutions' fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$110 to about US$300.76 per share, so private investors are clearly split on Jacobs Solutions. Set that diverging range against fresh multi year contracts in highways, wastewater and power transmission, and you see why opinions differ so sharply. Explore those other viewpoints.
Explore 2 other Jacobs Solutions fair value estimates, including one that suggests as much as 30% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jacobs Solutions research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Jacobs Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jacobs Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Jacobs Solutions?
If Jacobs Solutions has sharpened your focus on infrastructure and quality execution, it can help to compare it with other businesses that fit clear, disciplined criteria using the Simply Wall St Screener.
- For investors who care most about financial resilience and balance sheet strength, scan a list of solid balance sheet and fundamentals (24 results) that meet strict debt and liquidity checks.
- If you want potential value opportunities on your radar, review a 35 high quality undervalued stocks that match tighter fundamental filters instead of relying on headlines alone.
- Income focused investors can zero in on cash return potential by reviewing a 5 dividend fortresses that combine higher yields with underlying business quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com