
MP Materials (MP) Stock Could Be Overvalued On Magnet Qualification News
MP Materials has seen its share price fall 41.1% over the past year even after a gain of 125.8% over three years, which puts a sharper spotlight on whether the current US$36.46 level can be supported by its sales. With fresh headlines around rare earth supply chains and magnet production in the United States, the question now is how much of that story is already reflected in what investors are paying for each dollar of revenue.
- The share price is up 125.8% over three years, so anyone looking at MP Materials today is effectively judging whether that entire rerating is backed by the scale and quality of its current and potential sales base.
- Recent progress on rare earth magnet production for General Motors and the broader US supply chain can influence how investors think about future revenue mix, pricing power and the timing of cash flows that might justify a richer sales multiple.
- The analysts covering MP Materials have run their own numbers. See what analysts think MP Materials's shares could be worth.
The stock's next move may depend on whether MP Materials' present share price is adequately explained by the level and trajectory of its sales.
If you want more context around MP Materials and rare earth supply chains, it can help to compare it with other companies in the same theme using the 32 best rare earth metal stocks.
Does MP Materials Look Pricey on Sales?
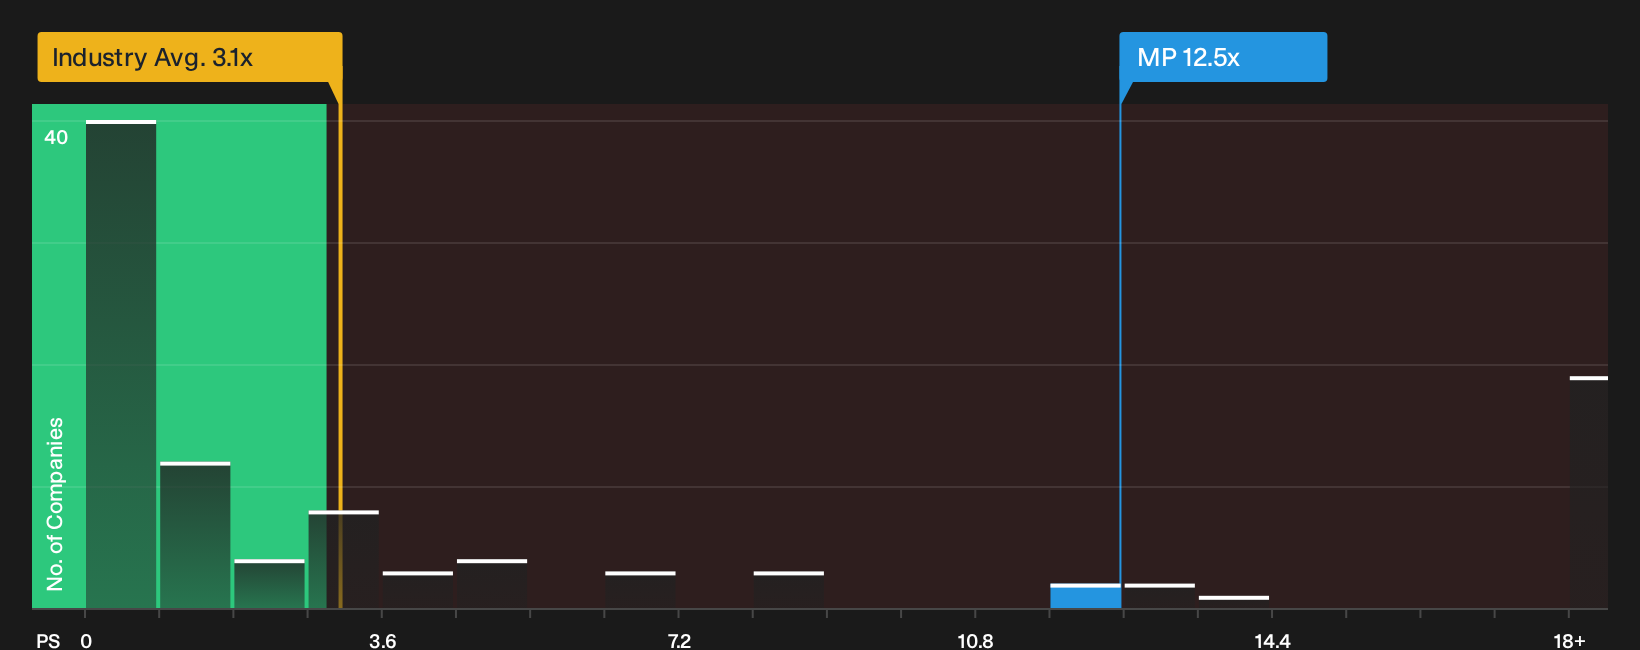
P/S is a useful lens for MP Materials because investors are currently focused on how much revenue the rare earth and magnet platform can generate rather than on steady profits. MP trades on a P/S of 12.5x, which is well above the broader Metals and Mining sector average of 3.1x and also higher than the 11.0x peer average for this niche. That tells you the market is paying a premium per dollar of sales compared with both the wider industry and closer rare earth comparables.
Based on the tailored fair multiple that blends MP Materials' growth profile, margin structure, size and risk, the present 12.5x P/S screens as overvalued. The recent Q3 2026 milestone, with GM magnet qualification and a sharp uplift in reported revenue, helps explain why sentiment is strong. However, the sales multiple already embeds a generous view of what that pipeline might deliver. Before you lean on this ratio, you would want to weigh how durable those new revenue streams look, how volatile rare earth pricing could be, and how quickly magnet volumes might ramp to support the current premium. Explore the numbers behind MP Materials's P/S valuation.
The MP Materials Narrative: What Would Justify Today's Price?
Narratives on MP Materials sit between the rich P/S multiple and your own expectations, because they spell out which paths for future growth, margins and earnings would need to play out for the current share price to look materially higher or lower over time on Simply Wall St's Community page. Each idea links its number to a clear view of where expansion, profitability and key risks might head next so you can revisit those assumptions as fresh information comes through.
One of the top narratives on MP Materials: 49% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation and this narrative’s bullish stance imply that the share price does not fully reflect MP Materials’ contracted cash flow potential..."
Discover why this Narrative puts MP Materials at 49% undervalued.
Before you act on MP Materials' valuation, there is one more piece to check
Price and sales only tell part of the MP Materials story, because the people making capital decisions and the way they are rewarded can pull the business toward very different outcomes. See who runs MP Materials and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com