
Missed Columbia Sportswear's Run? What Holders Had To Believe
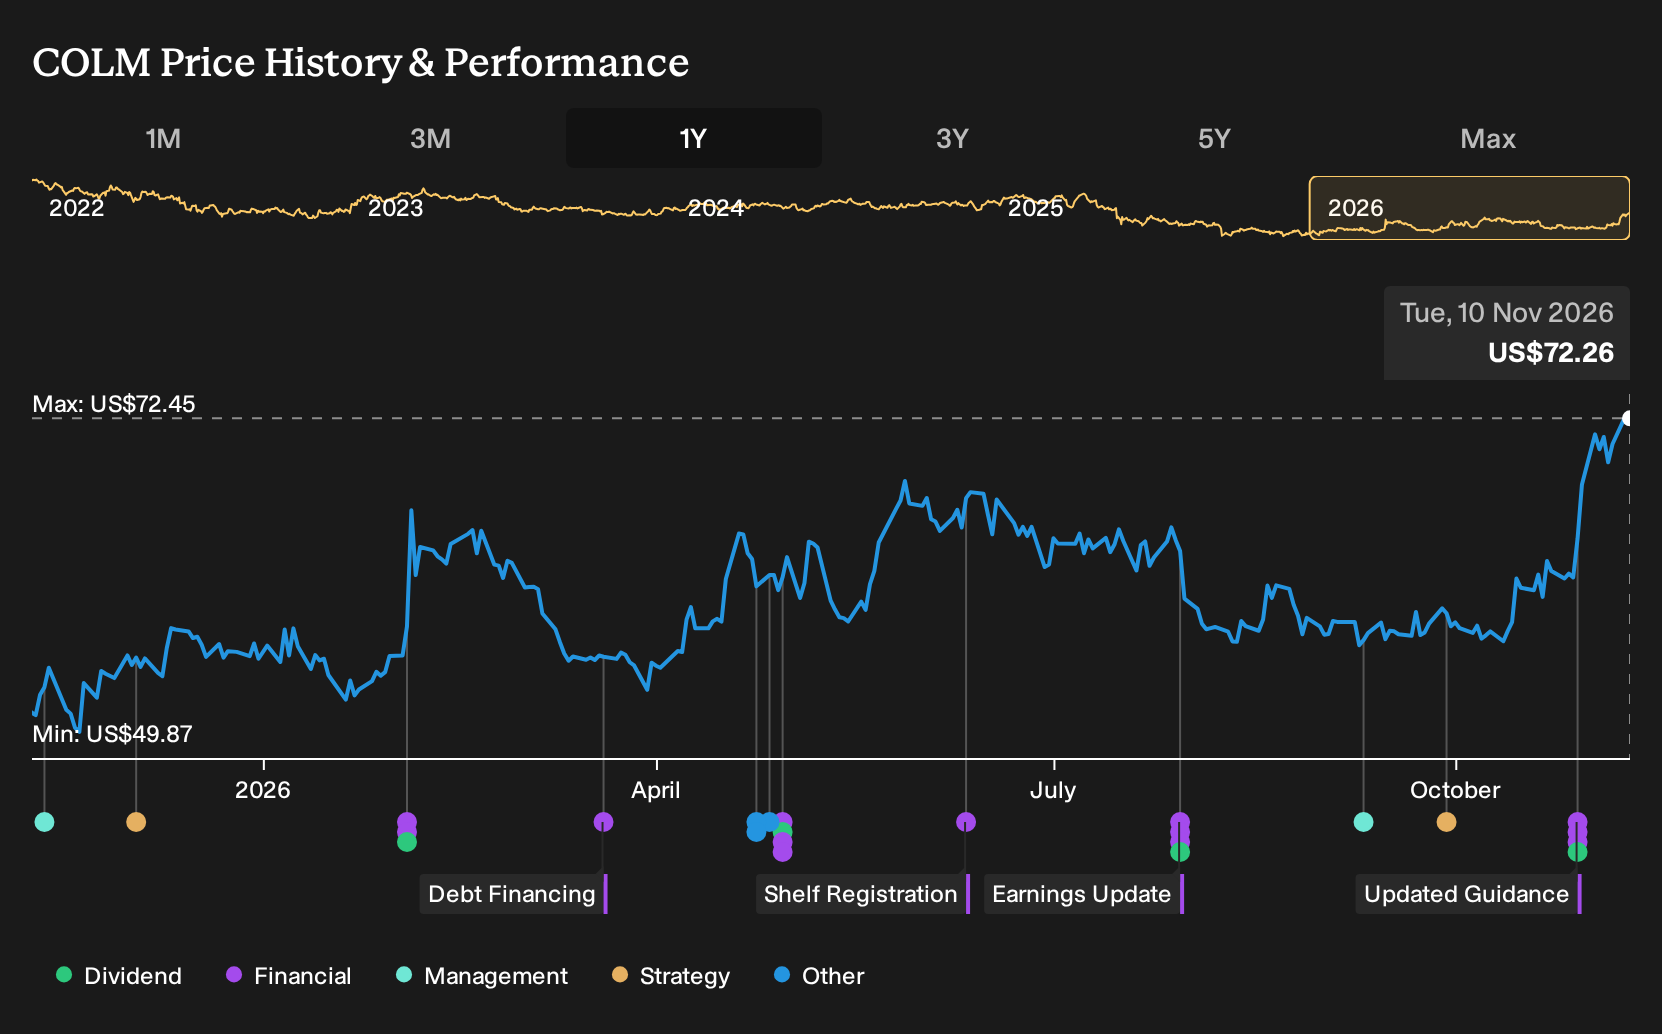
If you had bought Columbia Sportswear on 10 November 2025 and simply held on, the outcome would probably make you check the dates twice. Holding Columbia Sportswear over the past year would have returned 40.5%, including dividends. That gain arrived while headlines pulled in different directions, from tariff worries and weaker U.S. demand to upbeat reports on cost savings, overseas growth, and e-commerce. If you were weighing that purchase then, which of those competing signals would have mattered most?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Columbia Sportswear. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Two Columbia Sportswear Stories Investors Were Arguing About
The shares cost US$51.06 at the start of the period, and Columbia Sportswear sat between two sharply different stories about where the business might go next.
The bullish Columbia Sportswear narrative pointed to a Fair Value of US$79, based on expectations of 3.2% annual revenue growth and a 2028 P/E of 22.1x, supported by e-commerce upgrades and a full digital overhaul.
The bearish view put Fair Value at US$40, based on 1.3% annual revenue growth and profit margins declining from 6.6% to 4.4% as higher tariffs and trade policy pressures increased costs.
What The Results Changed For The Columbia Sportswear Debate
Columbia Sportswear’s Q3 2026 report showed revenue of US$962.6 million and net income of US$84.7 million, with net margin rising from 5.5% to 8.8%. That combination of higher sales and fatter margins leaned toward the optimistic case that focused on cost discipline and better profitability. Softer U.S. demand and tariff costs in the news still meant the evidence cut both ways.
The real hinge in this episode was profitability. If you are weighing a similar story elsewhere, track whether net margin moves toward or away from the scenario that justified the Fair Value narrative you are testing.
What Columbia Sportswear’s Price Now Asks You To Believe
Columbia Sportswear trades at US$72.26 after a 40.5% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, based on concerns about how much future profit resilience is already implied.
The Narrative highlights tariff costs, concentrated seasonal shipping, and heavier discounting as key pressure points. Anyone buying today effectively assumes Columbia Sportswear can turn international demand and franchises like footwear and PFG into steadier, higher quality earnings despite those specific risks.
"The numbers imply the share price already reflects a meaningful improvement in margins and earnings from current guidance ranges, so there is limited room for disappointment if tariff costs, geopolitical risks, or U.S. demand trends worsen."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 46% below our estimate - sells full-stack accelerated computing systems that power large scale AI buildouts and infrastructure.
- Company 2 - 38% below our estimate - supports complex technical analysis workflows as clients respond to heightened oversight requirements.
- Company 3 - 40% below our estimate - secures subsea projects by pairing quicker tieback execution with extended services arrangements.
Those are three of them. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com