
Organic Revenue Growth Could Be A Game Changer For Elementis Stock (LSE:ELM)
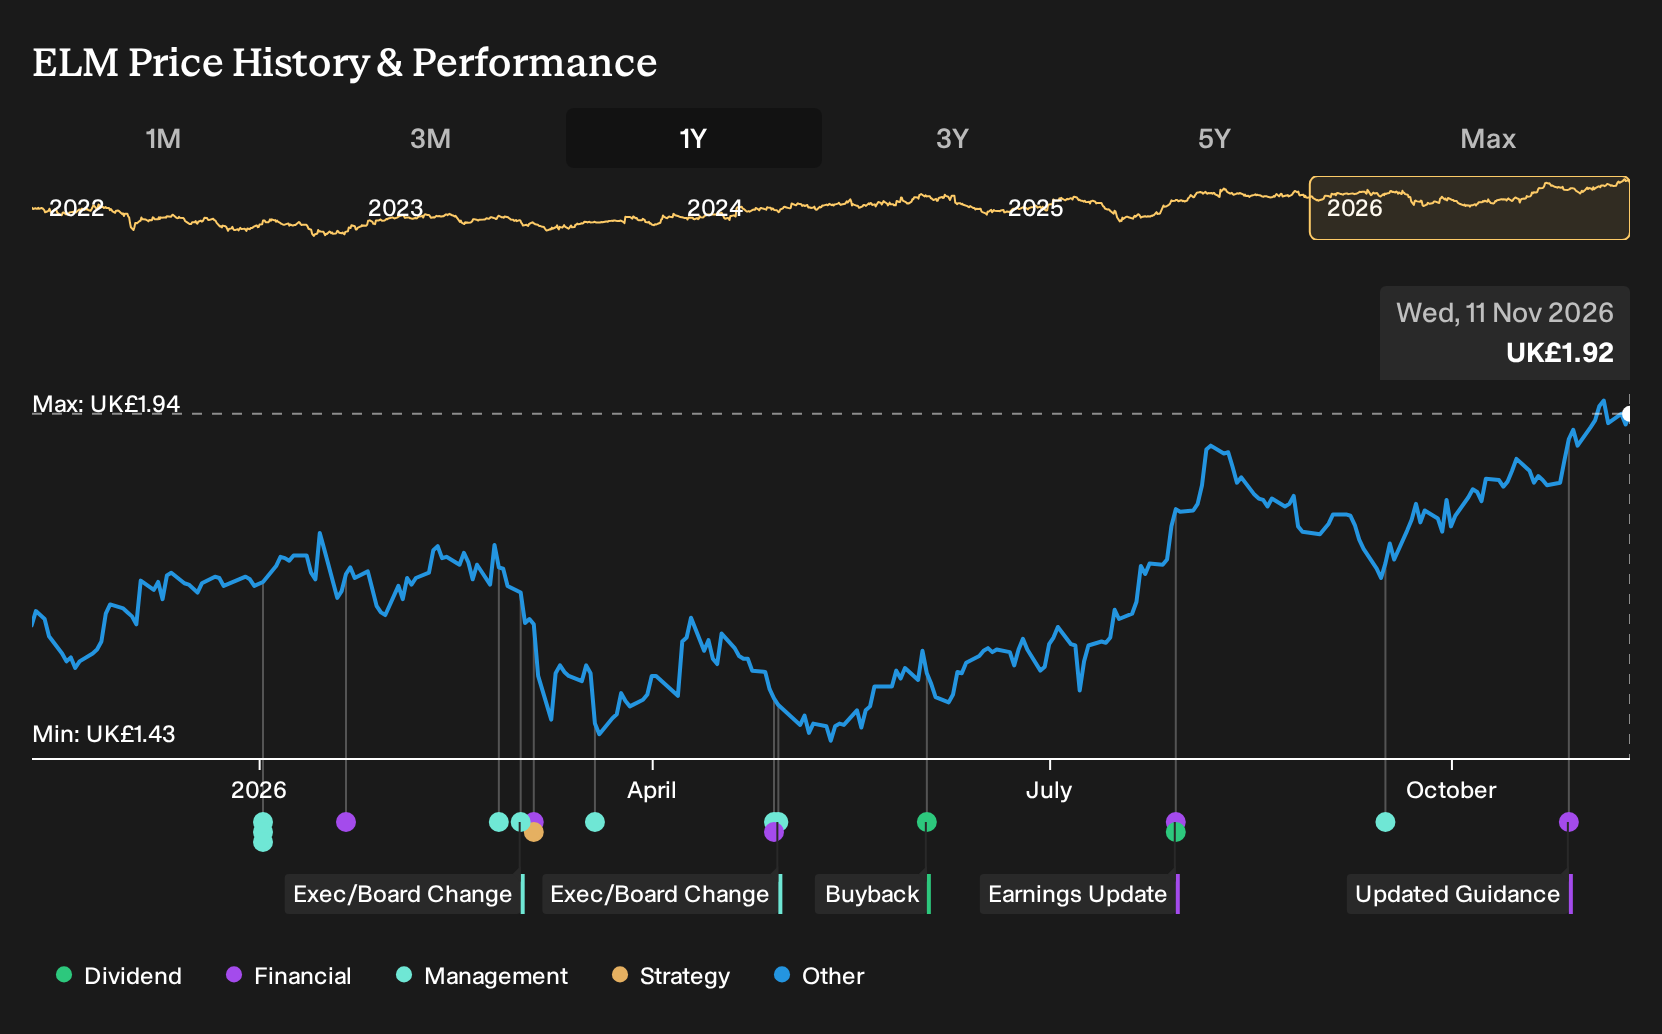
- Elementis reported that revenue for the nine months to 30 September 2026 reached $479 million, up 7% on an organic constant currency basis. This performance was supported by strong Personal Care demand, better conditions in the Americas, and ongoing momentum in Asia, and was later discussed on a shareholder and analyst call.
- The explicit guidance that fourth quarter sales are expected to be lower than the unusually strong third quarter, due to typical seasonality and earlier order fulfilment, gives investors a clearer view of Elementis’ order timing and volume visibility. It does this by clarifying expected sales patterns rather than suggesting a change in underlying demand.
- We will look at how Elementis' investment narrative around specialty additives and efficiency is influenced by this 7% organic revenue increase.
Elementis Investment Narrative Recap
To own Elementis, you need to believe in a focused specialty additives business that can keep turning niche chemistry in Personal Care and Coatings into resilient cash flows. The analyst consensus Narrative on Simply Wall St frames the key near term catalyst as execution on this higher margin mix, especially in Asia and Personal Care. The 7% organic constant currency revenue growth to US$479 million supports that story, while the softer seasonal fourth quarter guidance appears more related to timing than to a change in direction.
The biggest risk right now is concentration. After exiting Talc and Chromium, Elementis is more exposed if demand for its rheology modifiers or hectorite technology stalls or if competitors push alternative chemistries. Shorter customer order lead times and emerging market exposure also keep earnings more sensitive to trade or macro shocks, so any wobble in volumes would show up quickly.
The trading statement for the nine months to 30 September 2026 is the clearest reference point for this catalyst and risk mix. Management flagged US$479 million of revenue, up 7% on an organic constant currency basis, supported by strong Personal Care demand, better trends in the Americas, and continued momentum in Asia. That is the operational backdrop the analyst consensus Narrative on Simply Wall St is built on.
Guidance that fourth quarter sales should come in lower than the unusually strong third quarter is important mainly because it clarifies seasonality and order pull forward. It helps separate normal volume phasing from any structural change in demand. For a business leaning on cost savings, increased R&D investment, and geographic expansion, that transparency on order timing matters for how investors think about execution risk rather than altering the core thesis.
Elementis' analyst narrative points to revenues of US$652.3 million and earnings of US$101.4 million by 2029. These figures are built on an assumed 1.4% yearly revenue growth rate and an earnings increase of about US$29.7 million from US$71.7 million today.
Uncover why Elementis' fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight band between 2.13 and 2.38, showing how even a small group of retail perspectives can bunch together. There is still material disagreement on risks, ranging from concentration in specialty additives to potential upside from Elementis’ cost savings and Asia expansion. Consider how your own expectations fit across that spread.
Explore another Elementis fair value estimate, including one that suggests it could be worth just £2.13.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Elementis research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Elementis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Elementis' overall financial health at a glance.
Looking For More Ideas Beyond Elementis?
If the Elementis story has sharpened how you think about quality and valuation, use that same lens to hunt for other opportunities with the Simply Wall St Screener. You can filter for strength, income or stability and quickly narrow a wide market into a workable watchlist.
- If resilience and downside protection are high on your list, start with a set of companies that already screen well on risk and balance sheet strength through 5 resilient stocks with low risk scores.
- For investors who care about getting paid while they wait, focus on income opportunities that combine yield with fundamental support by checking out 4 dividend fortresses.
- If you want potential mispricing as your primary edge, concentrate on businesses where quality metrics and valuation support line up through 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com