
How Investors May Respond To BP (LSE:BP.) Stronger Quarterly Earnings
- BP reported third quarter 2026 sales of US$67,857 million and net income of US$4,696 million, with higher earnings per share across both the quarter and the first nine months of the year versus 2025.
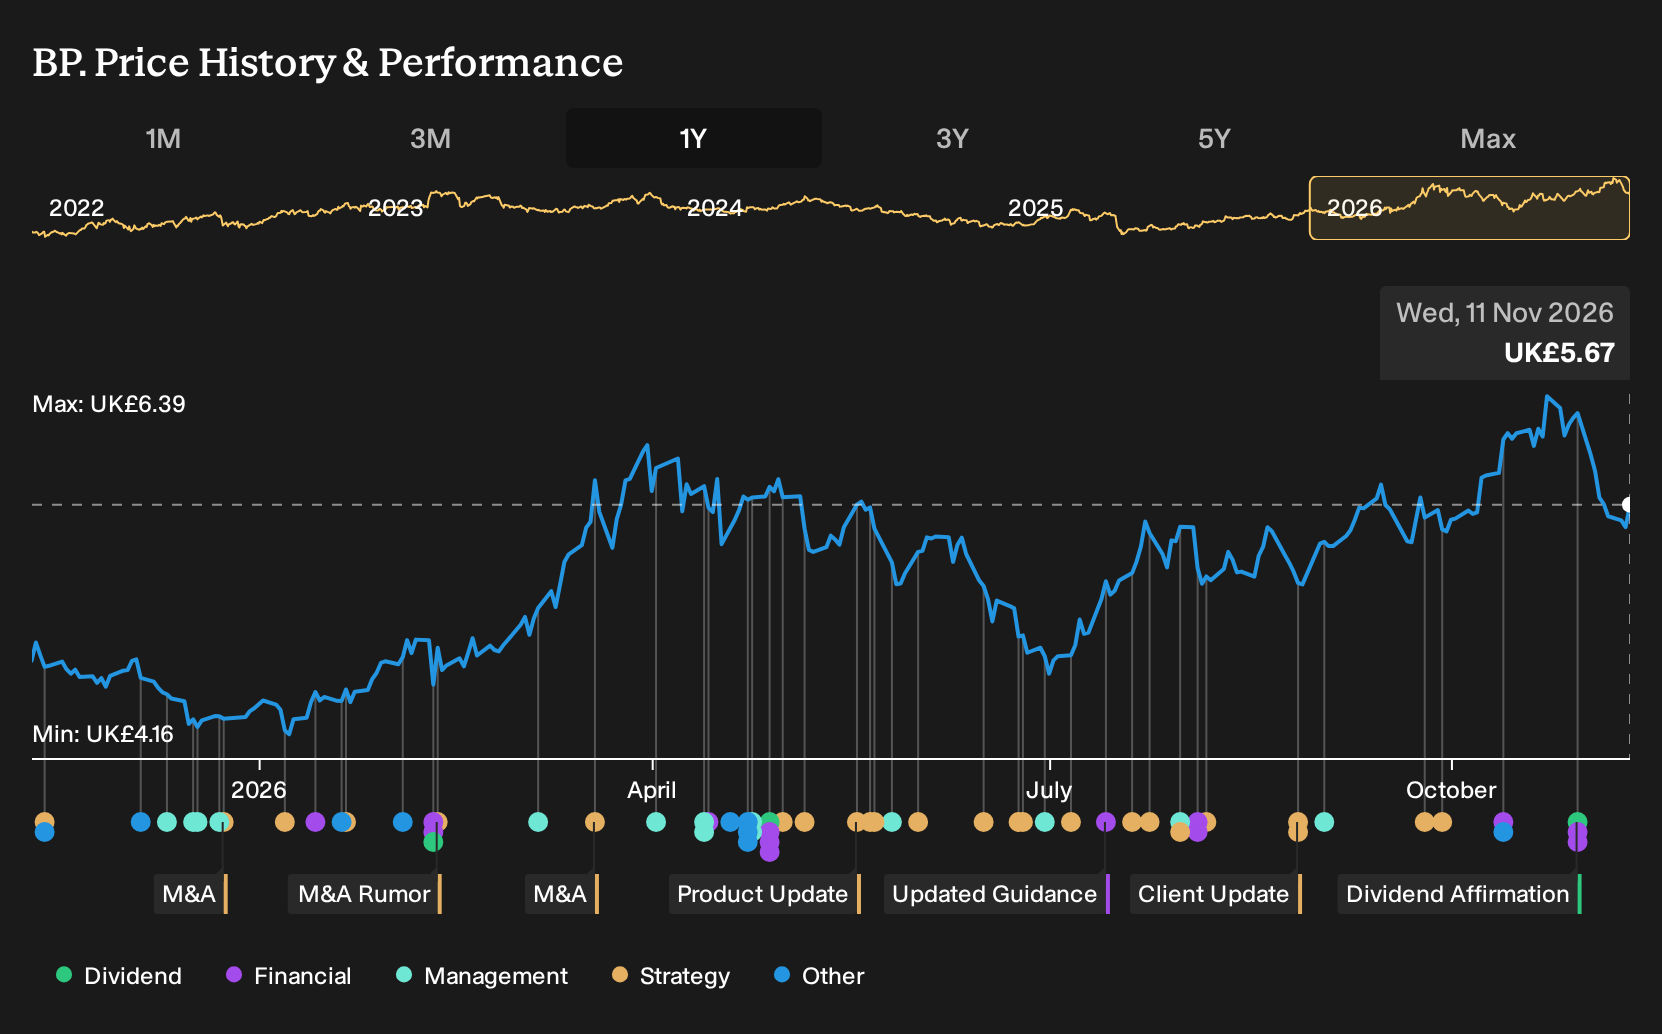
- The board affirmed an interim dividend of 8.660 cents per ordinary share for payment in December 2026, and secured a larger operated position in Namibian offshore exploration through the Eco Atlantic farm down. This development tightens the link between near term cash generation and longer term resource access.
- We will look at how BP's investment narrative is shaped by this stronger earnings profile and higher third quarter 2026 net income.
Scan beyond BP and line up other income focused names in energy and beyond using our hand picked screener of 4 dividend fortresses.
BP Investment Narrative Recap
To own BP for the long haul, you need to trust that its integrated model can turn large upstream resources and trading strength into steady cash while keeping capital discipline tight. The analyst consensus Narrative on Simply Wall St leans on project execution and cost reduction. The latest earnings show higher sales and net income for the quarter and nine months, which supports that story but does not remove execution risk.
In the short term, the key swing factor is BP's ability to keep production and refining running safely while holding costs in check, given management has flagged operating expenditure pressure. The biggest risk remains capital tied up in lower returning transition projects and further write downs in gas and low carbon assets, which could drag on returns if impairments continue.
The most directly relevant update for you is the third quarter 2026 earnings release. BP reported US$67,857 million of sales and US$4,696 million of net income for the quarter, alongside much higher basic and diluted earnings per share than the same period in 2025. For the first nine months, both revenue and profit were also higher than a year earlier.
Those figures matter because they sit alongside guidance that upstream production for full year 2026 is expected to be slightly below 2025 levels, and because earnings quality is influenced by large one off items. The stronger reported profitability gives BP more room to fund dividends, buybacks or debt reduction. At the same time, any future impairments in biogas and renewables or operational setbacks could quickly change how supportive these earnings feel for the current catalyst path.
BP's narrative projects US$195.4b revenue and US$10.2b earnings by 2029. That assumes revenue declines by 6.0% per year and earnings rise by about US$1.2b from US$9.0b today.
Uncover why BP's fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame BP’s reset of low carbon projects as a catalyst rather than a drag. Before this dividend affirmation and earnings release, that bullish group was pencilling in revenue of about US$244.6b and earnings of roughly US$12.4b by 2029. You can compare those expectations with your own and decide which story feels closer to your view.
Explore 4 other BP fair value estimates, including one that suggests there could be as much as 77% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BP research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for BP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BP's overall financial health at a glance.
Looking for more investment ideas beyond BP?
If BP is just one building block in your portfolio, it can help to set it alongside other stocks with clear income, quality, or risk profiles. The Simply Wall St Screener lets you do that quickly by filtering for the traits that matter most to you.
- For investors who want potential value with income support, you can line up companies offering strong yields and balance sheets through our 4 dividend fortresses.
- If capital protection and resilience sit at the top of your checklist, you can focus on businesses that score well on stability and financial risk using the 5 resilient stocks with low risk scores.
- When you are hunting for quality that is not yet widely followed, you can broaden your watchlist with our hand picked set of 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com