
Earnings Upgrade Change The Bull Case For Mitsui O.S.K. Lines Stock (TSE:9104)?
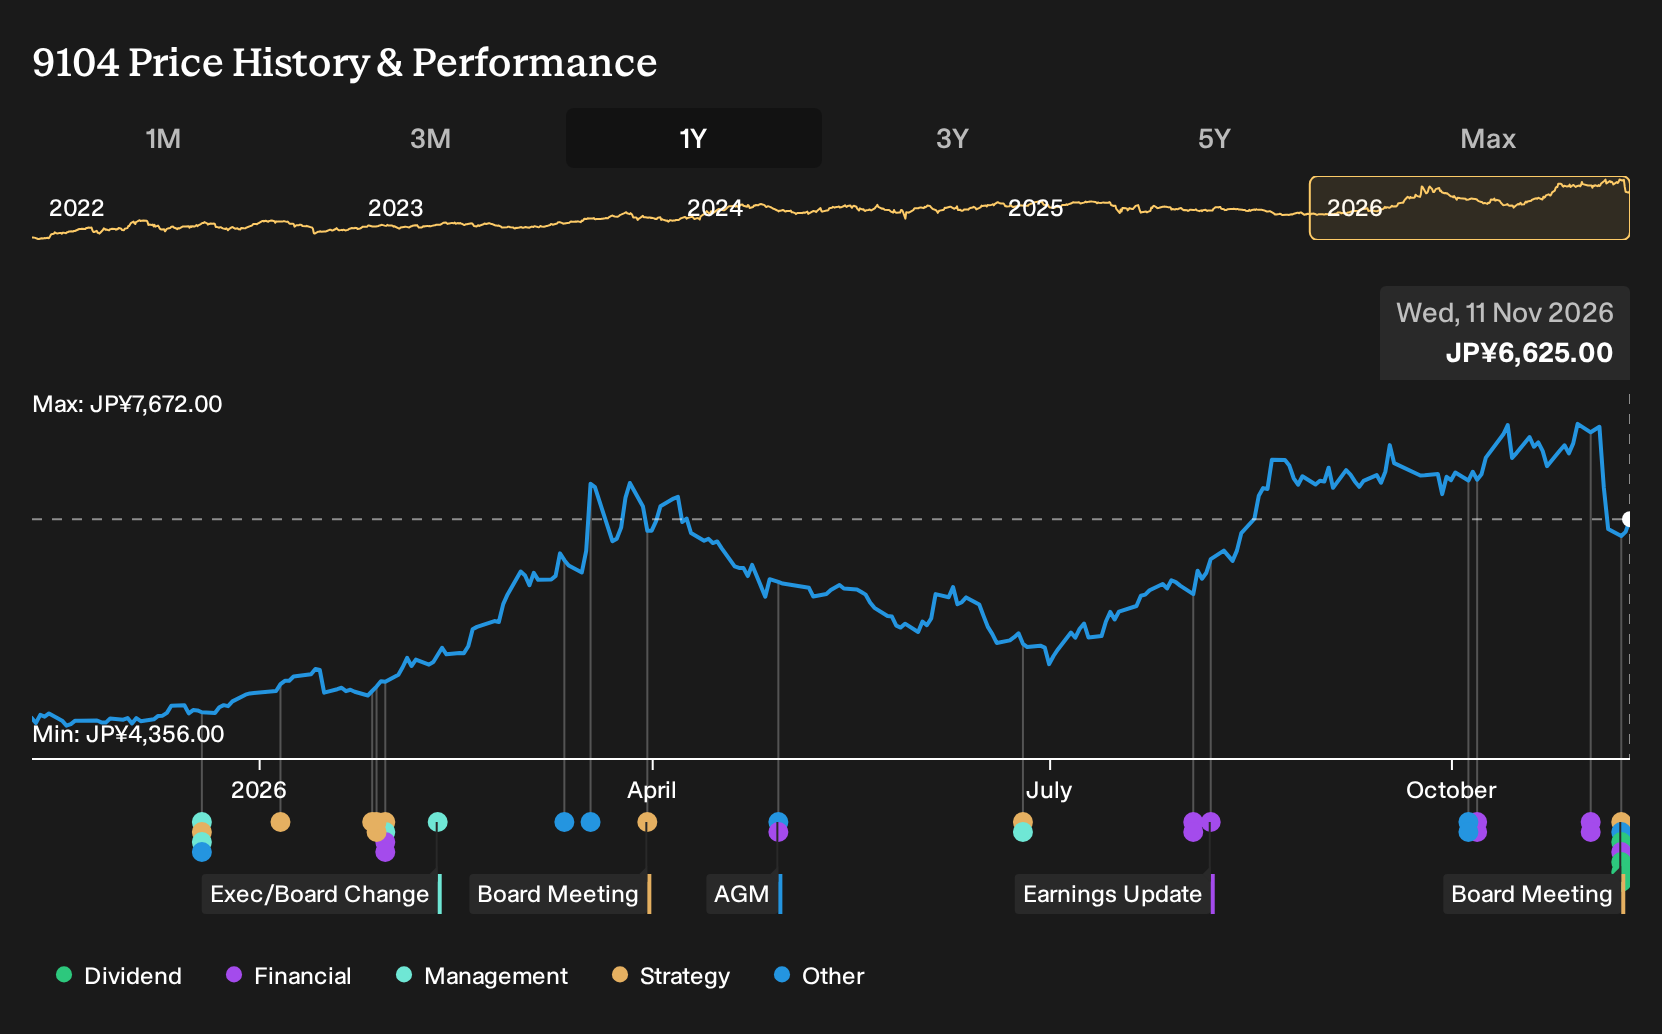
- Mitsui O.S.K. Lines reported half year net income of ¥179,313 million and higher earnings per share guidance, supported by stronger market conditions and an improved outlook for its equity method container shipping affiliate.
- The company paired those earnings upgrades with a new share repurchase program of up to 9,000,000 shares and refined dividend plans around a 3-for-1 stock split, indicating an active approach to capital allocation and shareholder returns.
- We will now look at how Mitsui O.S.K. Lines' upgraded earnings guidance and profit trajectory could influence the existing investment narrative.
Scan how Mitsui O.S.K. Lines’ buyback and dividend reset compare with other companies reshaping capital returns across our curated 29 dividend fortresses.
Mitsui O.S.K. Lines Investment Narrative Recap
To own Mitsui O.S.K. Lines, an investor needs to believe that energy logistics, vehicle transport and longer term contracts can offset a cyclical and often volatile shipping cycle. The analyst consensus narrative on Simply Wall St leans on those segments to support earnings quality over time, even as group revenue growth forecasts remain modest and recent years show pressured margins.
Right now, the key short term swing factor is freight pricing and volume in dry bulk, tankers and containers. The biggest risk is that weaker trade or vessel oversupply keeps rates soft just as Mitsui O.S.K. Lines faces high capex and earnings that analysts currently expect to decline over the next few years.
The clearest near term signal in this news flow is the upgraded earnings guidance on November 2, 2026. Management now projects full year consolidated revenue of ¥2,370,000 million and profit attributable to owners of parent of ¥300,000 million. This raises the bar for execution against what is already a cyclical backdrop.
For investors, that guidance update sits alongside a 9,000,000 share buyback cap and a rebased dividend around the 3 for 1 split. Together, these moves focus attention on whether Mitsui O.S.K. Lines can convert currently firm dry bulk and energy markets, plus its equity affiliate contribution, into consistent cash generation while handling debt coverage and large investment needs.
Mitsui O.S.K. Lines' analyst narrative points to ¥2,389.2b in revenue and ¥250.6b in earnings by 2029, based on 4.0% yearly revenue growth and an earnings increase of about ¥29.1b from current earnings of ¥221.5b.
Uncover why Mitsui O.S.K. Lines' fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The most optimistic analysts were already leaning on Mitsui O.S.K. Lines’ Phase 2 BLUE ACTION 2035 plan as a catalyst. They were pencilling in revenue of about ¥3,019.7b and earnings of roughly ¥408.9b by 2029, well above consensus. Those views predate the buyback and dividend reset, so this news could meaningfully shift that story depending on your own interpretation.
Explore 2 other Mitsui O.S.K. Lines fair value estimates, including one that suggests potential upside of up to 51% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Mitsui O.S.K. Lines research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Mitsui O.S.K. Lines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsui O.S.K. Lines' overall financial health at a glance.
Looking For More Ideas Beyond Mitsui O.S.K. Lines?
If this Mitsui O.S.K. Lines update has sharpened your thinking about capital returns, it could be a useful time to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- For investors who care about balance sheet strength first and share price action second, scan a list of solid balance sheet and fundamentals (23 results) that may better fit a capital preservation mindset.
- If you are hunting for quality at a measured price, compare Mitsui O.S.K. Lines with a 24 high quality undervalued stocks that already combine fundamentals with more conservative pricing.
- Income focused readers who want payouts backed by data rather than headlines can review a curated 29 dividend fortresses that prioritise higher yields with supporting financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com