
Xero (ASX:XRO) Nears Melio Era Results, Is It A Bargain Or Fully Priced?
Xero (ASX:XRO) moves into focus as traders position ahead of its H1 2027 earnings call on 12 November, the first set of results to fully include Melio.
Recent trading tells a story of short term optimism against a tougher long run backdrop. Xero’s 12.6% 7 day share price return and 15.2% 30 day gain mark a rebound after a year to date share price decline of 36.9% and a 1 year total shareholder return fall of 49.4%, as investors reset expectations around growth potential and execution risks ahead of the Melio infused H1 2027 update.
Compare how traders are positioning around Xero’s earnings reset with a curated group of software and tech platforms in our 14 high quality undiscovered gems.
Xero now trades well below both analyst targets and intrinsic value estimates after that sharp rebound. Does the latest move close the gap, or simply make the valuation puzzle more complex?
Most Popular Narrative: 36% Undervalued
Xero's last close at A$70.86 sits well below the A$110.98 fair value implied by the analyst consensus Narrative on Simply Wall St. This is built from aggregated revenue, earnings and discount rate assumptions rather than a single opinion.
The integration of the embedded bill payment solution through Xero Bill Pay powered by Melio, alongside AI capabilities such as the JAX platform and automated bank reconciliation that processes over 40 million transaction lines at more than 97% accuracy, is expected to deepen product usage and support future revenue and margin outcomes.
See why 118 investors see Xero as 36% undervalued.
Result: Fair Value of A$110.98 (UNDERVALUED)
Still, higher US brand spend and any pushback on recurring price rises, especially from small businesses under cost pressure, could quickly challenge that thesis of 36% undervaluation.
Find out about the key risks to this Xero narrative.
Another View: Market Multiple Says Xero Is Expensive
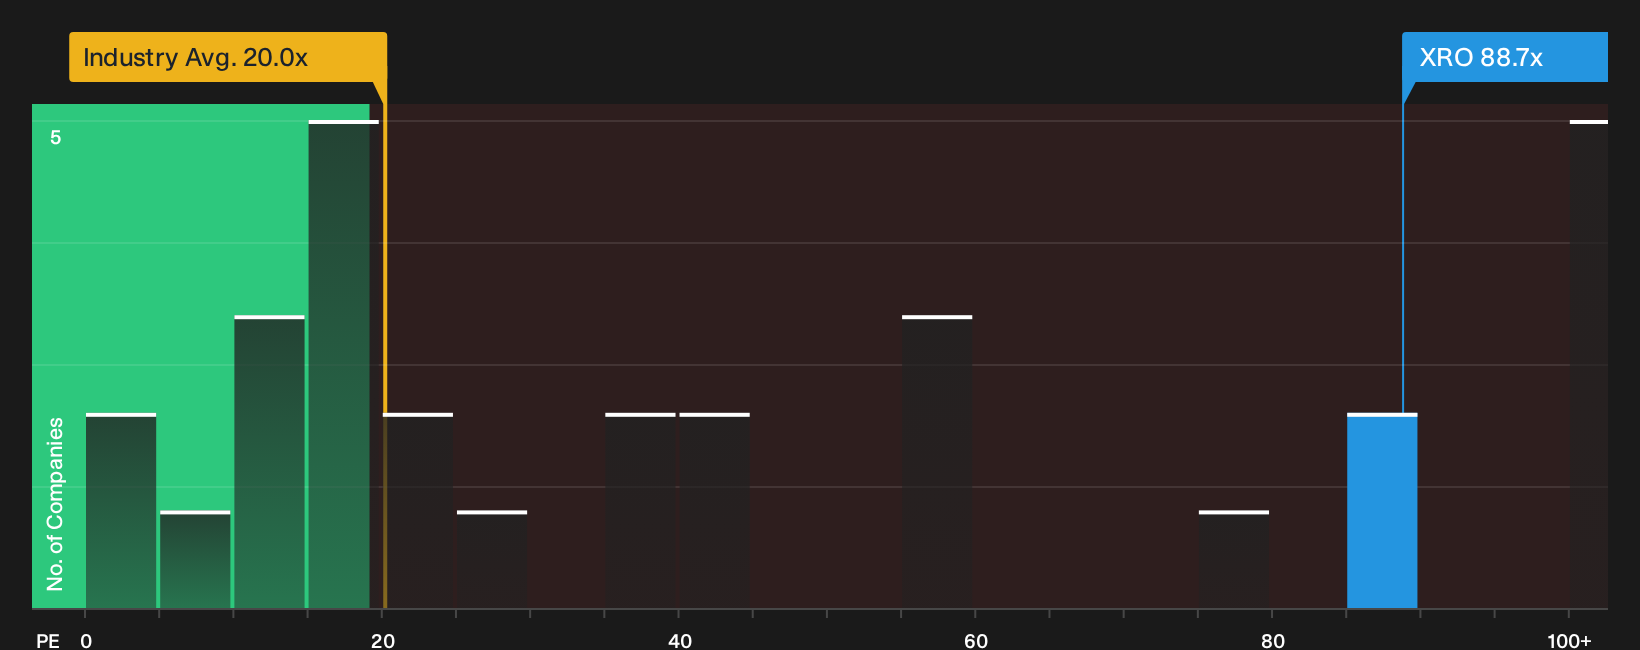
Xero might look appealing against a A$110.98 fair value from analyst narratives, yet the market’s own yardstick tells a different story. The share trades on a P/E of 88.7x, compared with 43x for close peers and 20x for the wider Australian software group.
That gap is even wider against the fair ratio of 51.2x, which is the level the P/E could move towards if sentiment cools. A valuation this far above both peers and the fair ratio can mean investors are paying up for execution that still has to be delivered. If earnings disappoint around Melio integration or US growth, how much multiple compression are you comfortable with?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If Xero really is both rich on multiples and cheap on fair value, you will want to test that tension against your own risk and reward balance. To see how that mix of concern and optimism stacks up in the data, start with the 2 key rewards and 1 important warning sign.
Looking for more Xero style investment ideas?
If Xero has you rethinking your watchlist, this is the moment to widen your scope and line up the next set of opportunities before the crowd moves.
- Target dependable compounding potential by scanning a 4 dividend fortresses that puts income and resilience at the centre of your research.
- Hunt for mispriced quality by reviewing a 3 high quality undervalued stocks that focuses on fundamentals rather than headlines.
- Protect your downside by zeroing in on a 6 resilient stocks with low risk scores tailored to investors who care as much about stability as upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com