
Time Interconnect Technology (SEHK:1729) Could Be 65% Undervalued After HK$500 Million Buyback
Time Interconnect Technology (SEHK:1729) has moved into focus after its board approved a share repurchase program of up to HK$500 million, shortly after it confirmed the termination of a Luxvisions Group supply agreement.
The buyback announcement appears to have triggered a sharp shift in sentiment, with the 1 day share price return of 7.19% reversing some of the recent pressure that left the 30 day share price return down 17.91% and the year to date share price return down 33.37% at a last close of HK$11.78.
Compare this buyback story with other potential rebound candidates by scanning our hand picked list of 201 high quality undervalued stocks that also pair earnings power with balance sheet strength.
Bulls see Time Interconnect Technology retiring shares at a steep implied discount, while bears point to contract uncertainty and recent share price pressure. Which side does the current valuation setup support next?
Preferred P/E of 20.3x: Is it justified?
On the valuation screen, Time Interconnect Technology trades on a P/E of 20.3x, while the last close sits at HK$11.78 and the SWS DCF model points to a future cash flow value of HK$34.02. That creates a split picture where earnings forecasts and cash flow estimates suggest one thing, and the headline multiple signals something else.
The P/E ratio compares what you pay per share to the earnings that Time Interconnect Technology generates per share. For a manufacturer of cable assemblies, digital cable and server products that operates across Mainland China, America and other regions, earnings-based measures often sit at the center of how investors benchmark value, because cash generation and profit resilience matter as much as growth stories.
Here the signals conflict. The stock is described as expensive on a P/E basis compared to the Hong Kong Electrical industry average of 12.5x, and also expensive relative to an estimated fair P/E of 14.7x. Yet the same dataset flags the shares as trading 65.4% below an internal future cash flow value estimate, with earnings forecast to grow 29.5% per year and revenue projected to expand 26.3% per year, which suggests the market price is not fully aligned with those growth and cash flow expectations.
The comparison with peers is blunt. Time Interconnect Technology trades on a P/E of 20.3x versus the Hong Kong Electrical sector at 12.5x, so investors are paying a much richer multiple than the wider industry. Against the estimated fair P/E of 14.7x, the current valuation also sits materially higher, which points to a level the market could revert toward if sentiment on its growth outlook or contract risk cools.
Explore the SWS fair ratio for Time Interconnect Technology.
Result: Price-to-earnings of 20.3x (OVERVALUED)
Still, the Luxvisions contract termination and any weaker demand across key regions such as Mainland China or America could pressure both the premium P/E and the buyback story.
Find out about the key risks to this Time Interconnect Technology narrative.
Another View: What The SWS DCF Says About Time Interconnect Technology
The P/E points to Time Interconnect Technology looking expensive, yet the SWS DCF model values the shares at HK$34.02 against a market price of HK$11.78. This implies the stock trades 65.4% below that cash flow estimate. Which signal should carry more weight in your playbook?
Look into how the SWS DCF model arrives at its fair value.
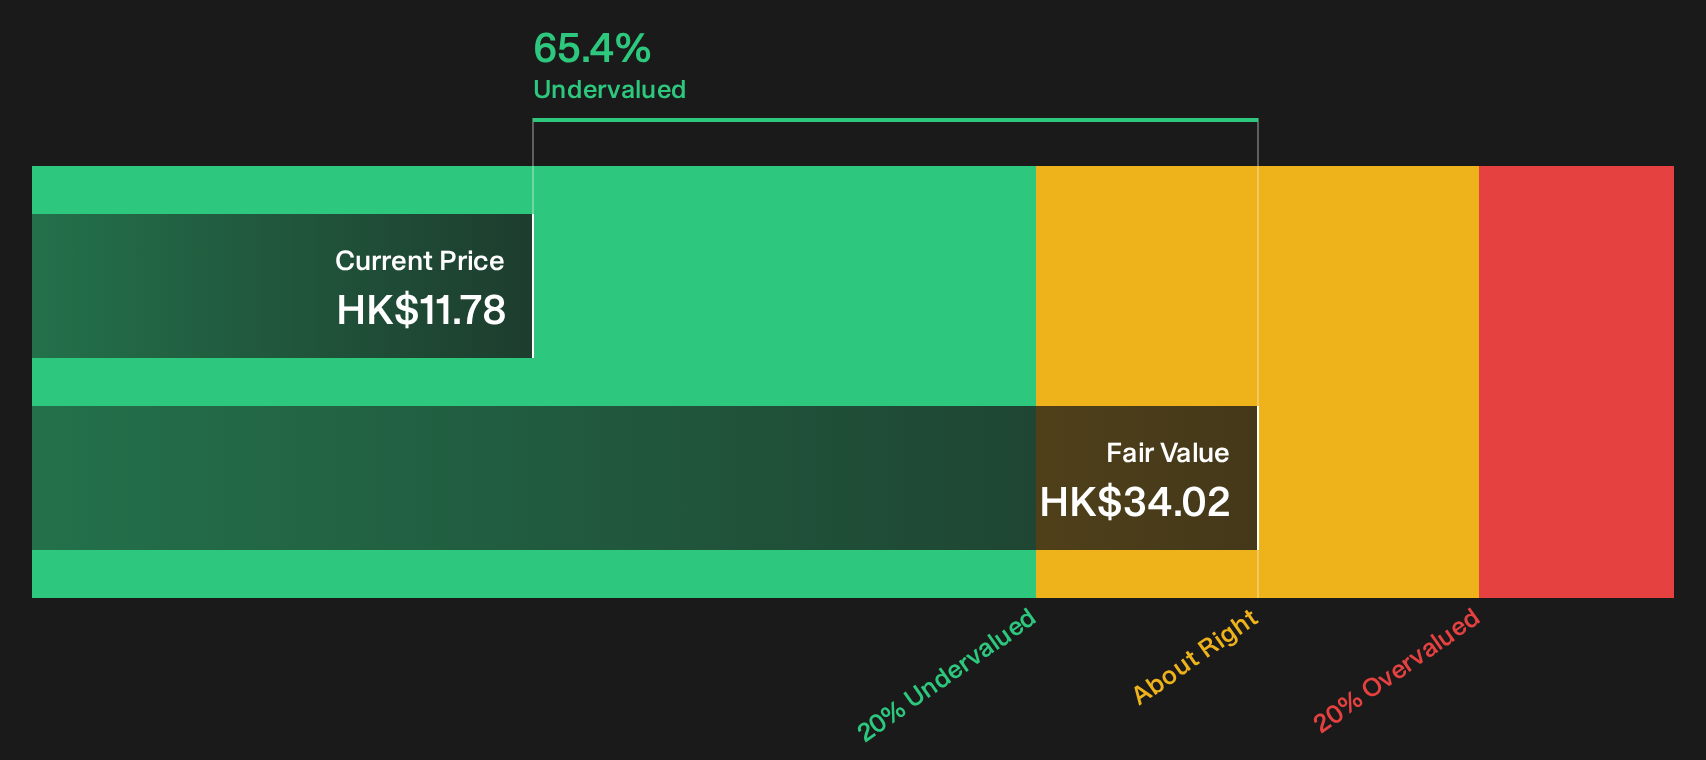
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Time Interconnect Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 201 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Time Interconnect Technology so far? Use this as a jumping-off point, move quickly through the numbers, and weigh the 3 key rewards and 2 important warning signs for yourself.
Looking for more Time Interconnect Technology investment ideas?
Do not stop your research with Time Interconnect Technology. The same tools that flagged this setup can surface other opportunities that fit your style and risk comfort.
- Scan for potential rebound plays with earnings strength by reviewing the 201 high quality undervalued stocks and compare how their valuations stack up against their fundamentals.
- Target stability and income in one move by checking companies in the 215 dividend fortresses that combine yield with resilient business profiles.
- Prioritise resilience first by filtering the 209 resilient stocks with low risk scores that score well on financial health and lower volatility traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com