
Aecon Group (TSX:ARE) Reports Record Backlog, Is It Still Undervalued?
Aecon Group (TSX:ARE) just put fresh numbers on the table, with third quarter 2026 earnings showing higher sales and net income, alongside a record backlog tied to long-term infrastructure and energy projects.
Aecon Group’s recent earnings update lands after a powerful run in the market, with a year to date share price return of 78.36% and a five year total shareholder return of 308.37%, which points to sustained momentum rather than a short spike in sentiment.
Scan a curated set of infrastructure and construction plays with similar contract momentum by running the 5 high quality undervalued stocks alongside Aecon Group on your watchlist.
Aecon Group now trades below the average analyst target despite a sharp share price move this year. Is that a genuine valuation gap, or is the market pricing in real risks?
Most Popular Narrative: 8% Undervalued
The analyst consensus Narrative on Simply Wall St views Aecon Group as modestly undervalued, with a fair value of CA$61.30 against the last close at CA$56.22. That view rests on specific assumptions about long term demand, margins and contract mix.
Accelerating investment in energy transition and decarbonization infrastructure (such as grid-scale energy storage, nuclear refurbishment, and electrification projects) is driving robust demand for Aecon's core capabilities, supported by record backlog and multi-year project pipelines, positively impacting revenue growth and order book visibility.
Increased public spending on infrastructure driven by urbanization, population growth, and the need to upgrade aging assets in Canada and the U.S. is expanding Aecon's addressable markets, supporting sustained growth in top-line revenue and reducing reliance on one-off projects.
See why 40 investors see Aecon Group as 8% undervalued.
Result: Fair Value of CA$61.30 (UNDERVALUED)
Still, Aecon Group’s reliance on government backed infrastructure and the ongoing squeeze on construction margins could quickly challenge the idea that the shares are modestly undervalued.
Find out about the key risks to this Aecon Group narrative.
Another View: SWS DCF Flags Aecon Group As Expensive
The analyst narrative sees Aecon Group as undervalued around a fair value of CA$61.30. Our DCF model paints a very different picture. On that framework, the estimated future cash flow value sits near CA$17.17 per share, which is well below the current CA$56.22 level and points to an overvalued stock on this metric.
Those two signals are very far apart, so the key question is straightforward: do you rely more on the earnings path implied by the analyst forecasts, or on the more conservative cash flow profile used in the DCF work?
Look into how the SWS DCF model arrives at its fair value.
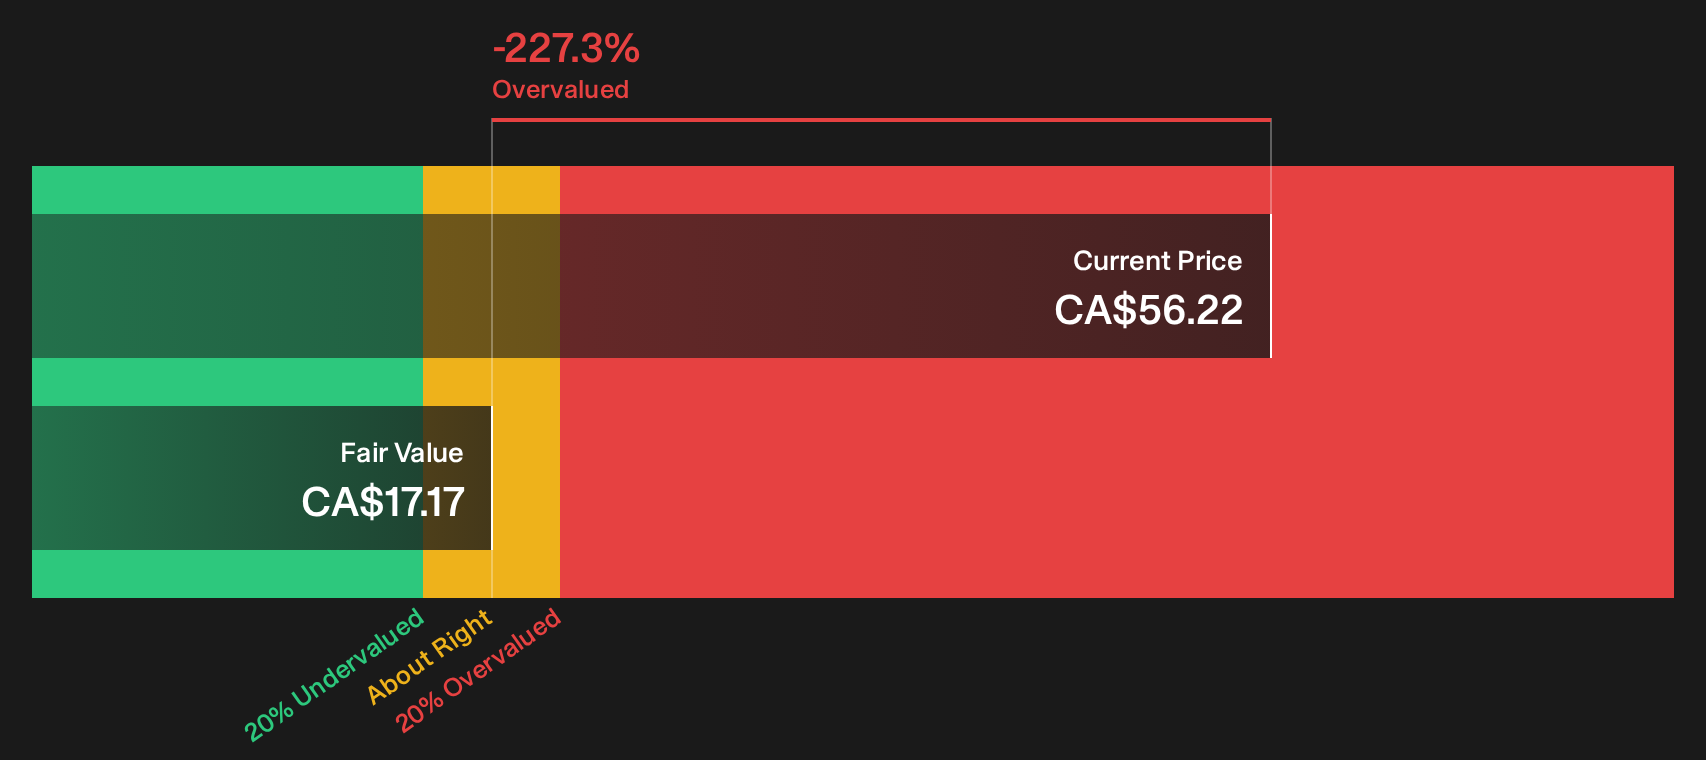
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aecon Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Aecon Group's valuation and risk reward balance are clear, so act while the data is fresh and weigh both sides using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Aecon Group?
If you only stop at Aecon Group, you miss a wider field of potential opportunities that could fit your risk profile, income needs, and growth goals.
- Target dependable cash generators by scanning a list of solid balance sheet and fundamentals (5 results) that can help anchor your portfolio when sentiment swings.
- Hunt for overlooked opportunities using the 8 high quality undiscovered gems and spot quality businesses the crowd has not fully focused on yet.
- Stack your watchlist with resilient holdings by reviewing the 9 resilient stocks with low risk scores that prioritises stability alongside fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com