
Is Exchange Income (TSX:EIF) Undervalued As Margin Pressure And Heavy Spending Weigh On Earnings?
Recent reports on Exchange Income (TSX:EIF) point to tighter margins, rising operating expenses, and elevated capital spending. These factors are pressuring earnings and cash generation across its aerospace, aviation, and manufacturing operations.
Despite those pressures, Exchange Income’s share price has climbed to CA$124.28, with a 7 day share price return of 3.9% and a 30 day gain of 6.8%. However, the 90 day share price return is down 7.2%, so momentum has cooled in the short term but remains strong when set against the 51.9% year to date share price return and a very large 3 year total shareholder return of about 21x. This hints at investors reassessing both the growth opportunity and the risks in the story.
Scan beyond Exchange Income by reviewing hand picked peers facing similar margin and cash flow pressure through the 9 resilient stocks with low risk scores, which still screens for resilience on the balance sheet and fundamentals.
Exchange Income now trades about 18% below the average analyst price target and around a 33% discount to one intrinsic estimate, yet recent margin strain is clear. Is that gap a sign of caution, or is the opportunity being mispriced?
Most Popular Narrative: 18% Undervalued
On the analyst consensus Narrative on Simply Wall St, Exchange Income screens as undervalued, with a fair value of about CA$152 against the last close at CA$124.28, which presents a clear discount for investors to assess.
The growing pipeline of long term intelligence, surveillance and reconnaissance, training and in service support work at PAL Aerospace, including the roughly C$750 million Future Aircrew Training contract expected to start contributing in fiscal 2027, is described as setting up additional high visibility revenue and EBITDA from defense related aviation.
See why 39 investors see Exchange Income as 18% undervalued.
Result: Fair Value of CA$152 (UNDERVALUED)
Still, higher maintenance capital spending and ongoing margin pressure at Multi Storey Window solutions could challenge the bullish Exchange Income narrative if these factors persist.
Find out about the key risks to this Exchange Income narrative.
Another View: Earnings Multiple Flags Valuation Risk For Exchange Income
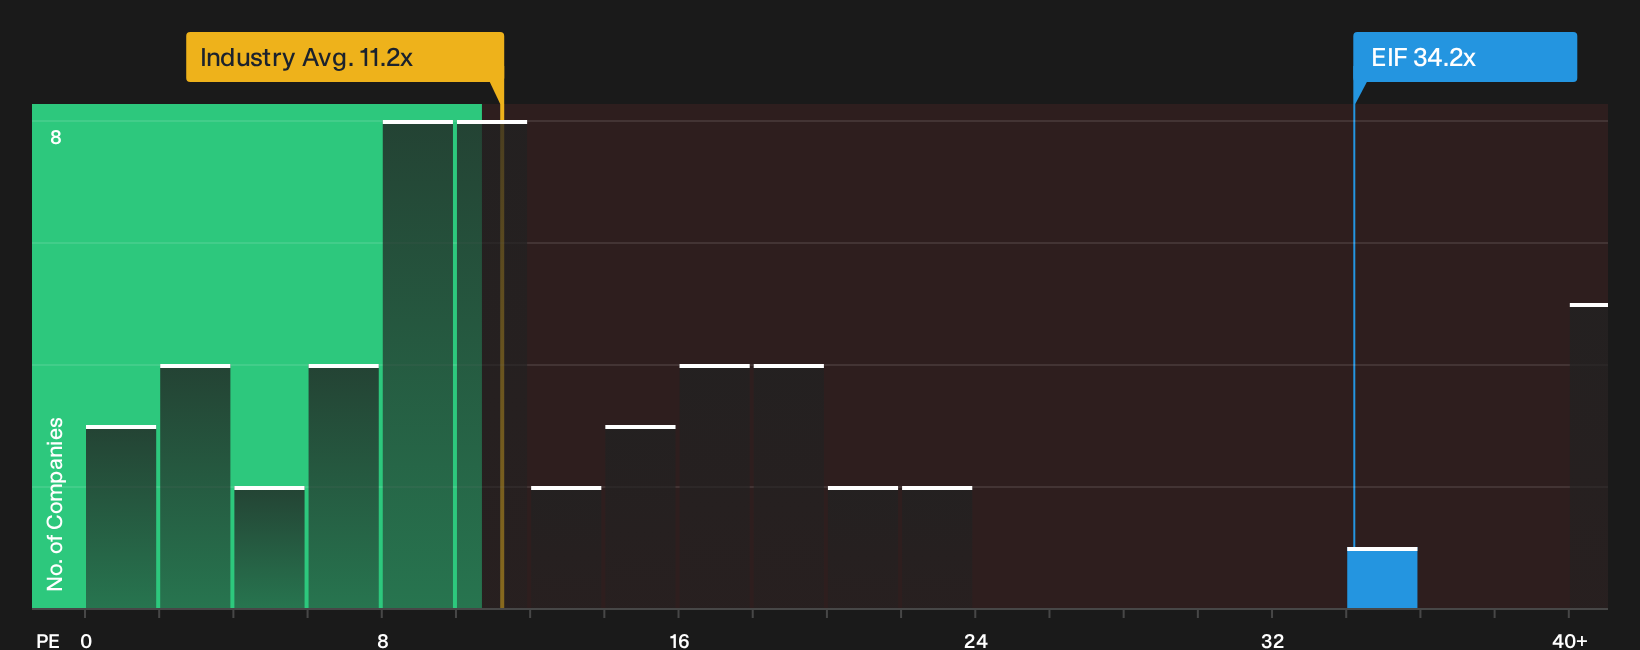
On a simple earnings yardstick, Exchange Income looks less comfortable. The stock trades on a P/E of 34.2x, which is far richer than the Global Airlines industry at 11.2x, peers at 20.3x, and even its own fair ratio of 24.4x. This raises the question of how much optimism is already baked in.
That gap suggests meaningful downside if sentiment shifts toward the fair ratio, or upside if earnings keep compounding into the current price. For a closer look at how this earnings based view fits with the broader valuation work, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Exchange Income story can be confusing, so move quickly, review the full data, and weigh the potential upside and downside for yourself by checking the 4 key rewards and 3 important warning signs
Looking for more ideas beyond Exchange Income?
If Exchange Income has sharpened your thinking, do not stop here. Use the Simply Wall St screener to spot fresh opportunities before everyone else catches on.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (5 results), which filters for financial strength and staying power.
- Hunt for quality at a discount by reviewing the 5 high quality undervalued stocks, which highlights companies where current pricing differs from underlying fundamentals.
- Focus on income potential by checking the 3 dividend fortresses, which surfaces higher yielding stocks with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com