
Did Federal Project Delays Just Shift Axon Stock's Investment Narrative?
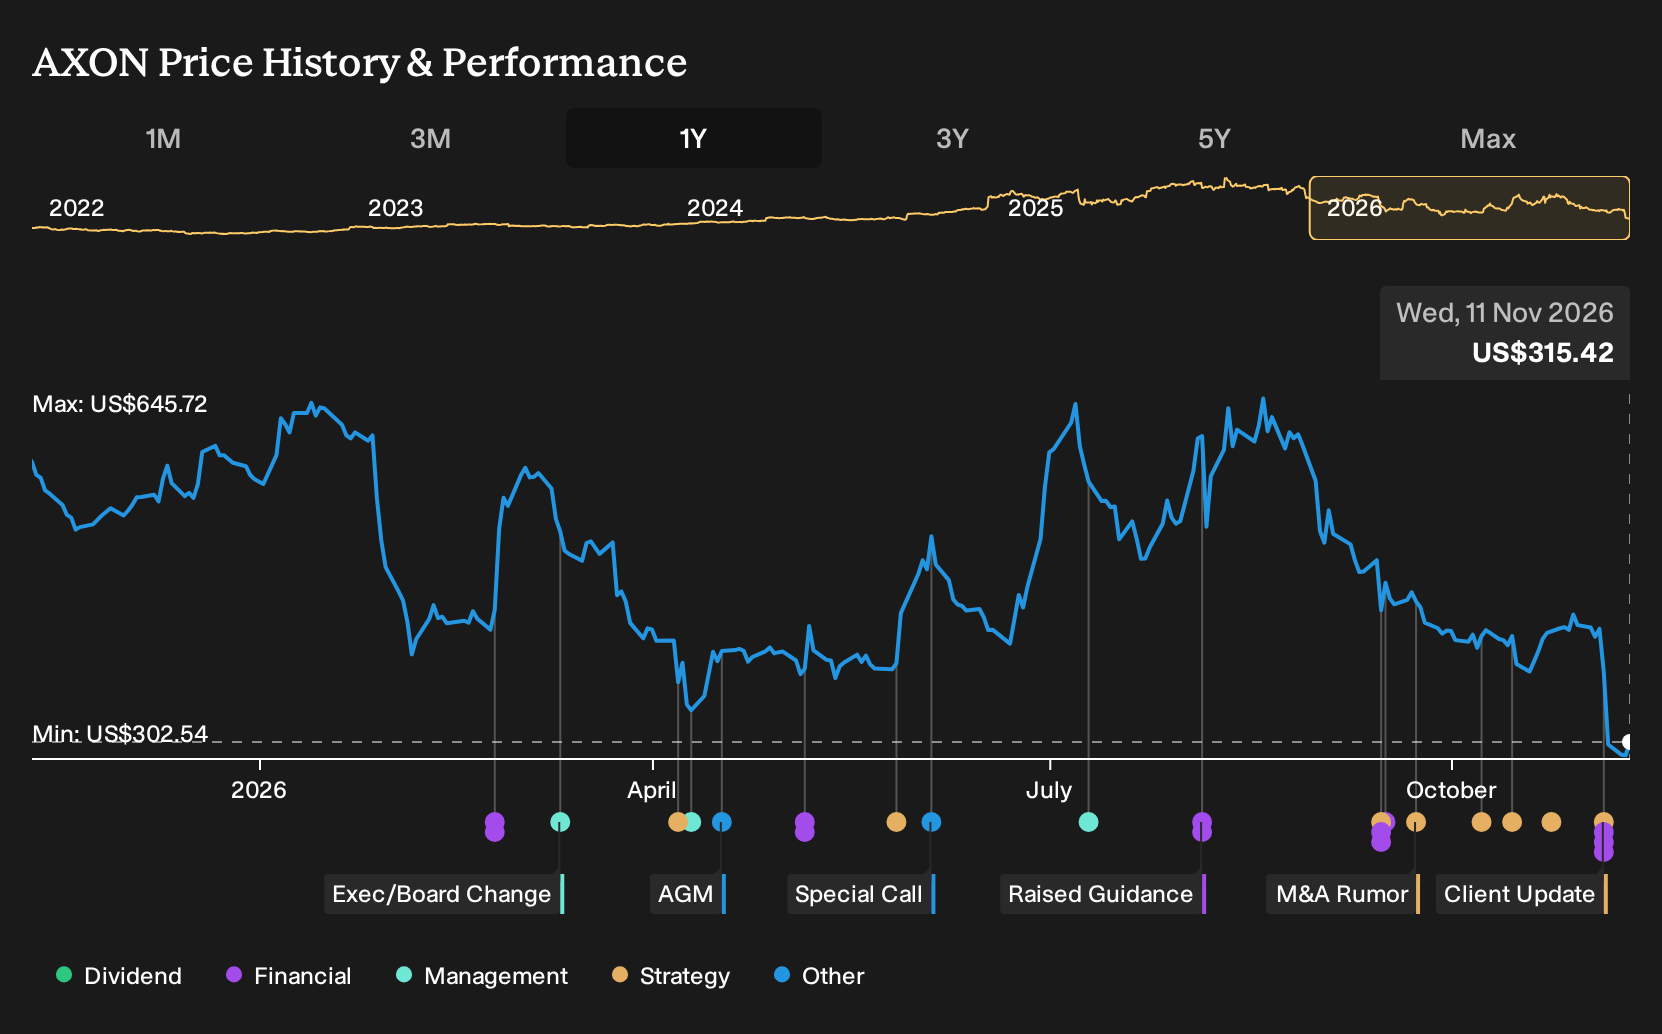
- Axon Enterprise reported past third quarter 2026 results with US$908.55 million in revenue and US$57.01 million in net income, then cut full year guidance after delaying three large federal Dedrone counter drone deployments that were previously included in its outlook.
- The business is committing about US$1.2 billion to deepen its Skydio partnership and expand Drone as First Responder coverage, even as higher component costs and timing shifts in federal projects put pressure on near term earnings guidance.
- Next, the focus will be on how Axon Enterprise's reduced guidance and counter drone project delays affect the longer term investment narrative.
Axon Enterprise Investment Narrative Recap
To stay invested in Axon Enterprise, you need to believe the analyst consensus narrative on Simply Wall St that public safety agencies keep shifting toward Axon’s bundled software, cameras, TASER devices and now drones. The trimmed 2026 outlook and Dedrone delays do not change that core idea. However, they sharpen the focus on timing risk in government projects.
The key near term catalyst is Axon executing on its revised fourth quarter revenue range of US$990 million to US$1.01 billion while managing higher component costs. The biggest current risk is that counter drone and newer hardware lines keep weighing on margins and free cash flow longer than expected as large federal deployments move around the calendar.
The US$1.2 billion commitment to Skydio is the announcement most tied to this news. Axon Enterprise is leaning harder into Drone as First Responder, where it already sees an estimated US$13 billion addressable market in the US and Canada and access to more than 1,500 public safety customers through Skydio.
For you as a shareholder, the Skydio expansion sits right next to the Dedrone delays. Execution here could be a major operational catalyst if Axon converts more agencies to recurring drone and software bundles. It also raises execution and capital allocation risk, because a larger drone footprint likely brings more hardware costs and potential margin pressure in the near term.
Axon Enterprise's current analyst narrative points to forecast revenue of US$7.2b and earnings of US$337.4 million by 2029, based on an assumed 28.0% yearly top line growth rate and an earnings increase of about US$78.9 million from US$258.5 million today.
Uncover how Axon Enterprise's fair value indicates a 78% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Axon Enterprise forecasts leaned hard on hardware margin risk instead of drone upside. Those analysts were already penciling in revenue of about US$6.8b and earnings of roughly US$533.4 million by 2029, and still saw the stock fully pricing in strong execution. With the new guidance cut and Skydio spend, that more cautious storyline could shift again. It is worth comparing both sets of assumptions before you decide how this drop fits your own view.
Explore 4 other Axon Enterprise fair value estimates, including one that suggests it could be worth just $453.59!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Axon Enterprise research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Axon Enterprise. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Axon Enterprise's overall financial health at a glance.
Looking For More Investment Ideas Beyond Axon Enterprise?
If Axon Enterprise has sharpened your thinking about tools, data and risk, it can help to compare that story with other opportunities filtered by clear fundamentals using the Simply Wall St Screener.
- For investors hunting for potential mispricing, review a curated group of companies with strong fundamentals that still trade at what may be appealing valuations through the 32 high quality undervalued stocks.
- If resilience matters most to you, focus on balance sheet strength and funding flexibility by scanning the list of solid balance sheet and fundamentals (24 results).
- For income focused portfolios that still pay attention to quality, check out a set of higher yielding payers screened as 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com