
SFL (SFL) Could Be 17% Below Fair Value On Q3 Results And New Charters
SFL (NYSE:SFL) just paired fresh third quarter results with a new fleet expansion, reporting US$201.58 million in revenue and US$37.35 million in net income, and confirming its US$0.22 per share quarterly dividend.
SFL shares trade at US$10.94, with the price down 19.32% over the past month and lower by 9.59% across the last quarter, even after a 38.66% year to date share price return and a 5 year total shareholder return of 102.35%. The recent pullback, alongside Q3 earnings and new long term vessel charters, points to investors reassessing near term risk while still crediting the longer track record of compounding returns.
Scan for more shipping and income plays moving on fresh contracts and dividends by reviewing our curated 6 dividend fortresses alongside SFL's latest earnings and fleet expansion story.
SFL now trades well below its recent highs while locking in fresh multi year charters and new vessels. Is it better to step in at this pullback, or to wait for potentially cheaper terms?
Most Popular Narrative: 17% Undervalued
SFL closed at $10.94, while the analyst consensus Narrative on Simply Wall St anchors fair value closer to $13.17 based on detailed revenue and earnings forecasts, using a 7.24% discount rate to bring those projections back to today.
SFL's ongoing investment in modern, fuel efficient and LNG capable vessels, including five dual fuel container newbuildings, four LNG dual fuel PCTCs and LNG upgrades on chemical tankers, aligns the fleet with tightening environmental requirements and cargo owner preference for lower emission transport. This may support stronger charter terms, high utilization and future net margins and earnings.
See why 15 investors see SFL as 17% undervalued.
Result: Fair Value of $13.17 (UNDERVALUED)
Still, SFL’s heavy exposure to energy linked assets and roughly US$1.2b of unfunded growth capex could quickly test that undervaluation story if conditions turn.
Find out about the key risks to this SFL narrative.
Another View: What SFL’s P/E Is Really Saying
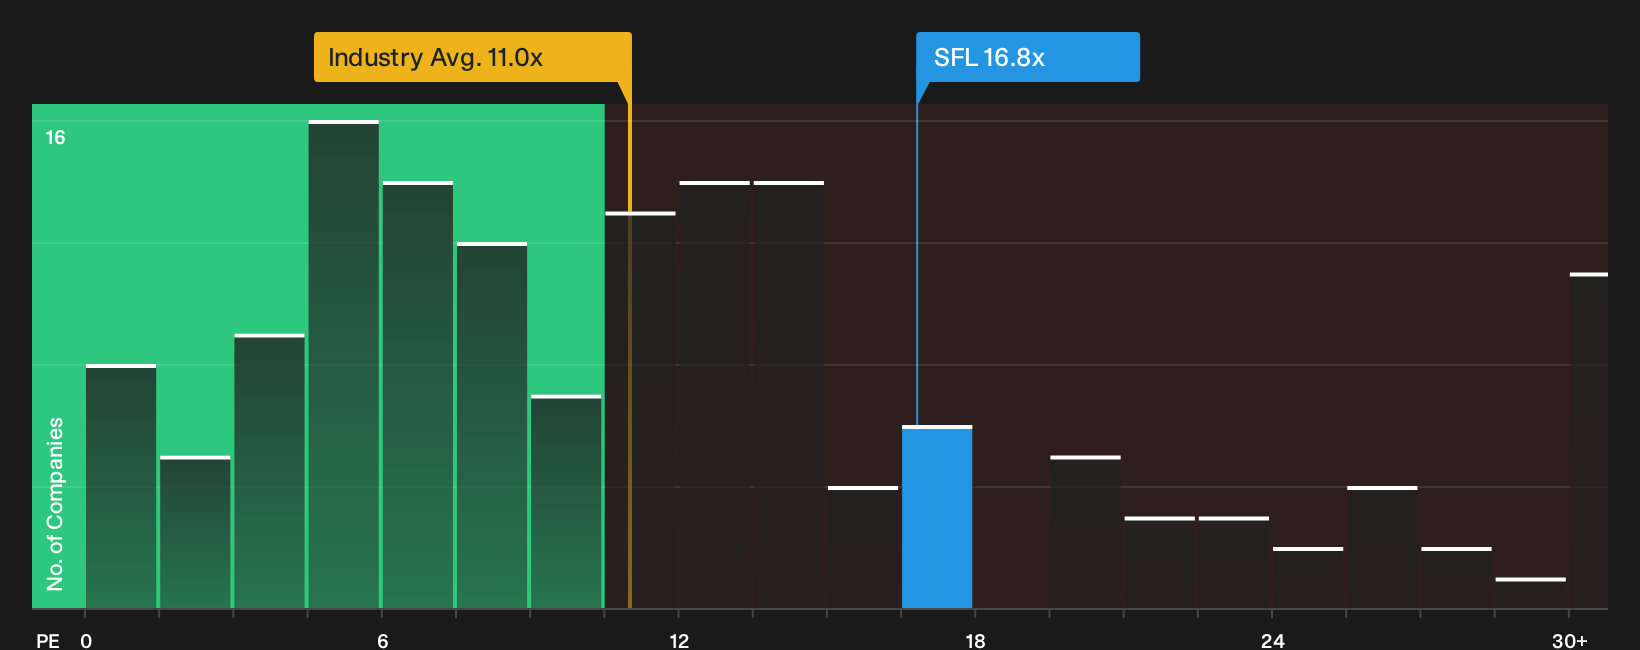
The first narrative argues SFL is about 17% below fair value at $10.94 using forward earnings and a discounted cash flow style framework. The simple P/E check tells a tougher story. SFL trades on 16.8x earnings, compared with 11x for the US Oil and Gas industry and a fair ratio of 12.4x.
That gap suggests investors are already paying a premium for SFL’s contracted backlog and dividend history. This leaves less room if the thesis around earnings growth or capital spending is tested. The question for you is whether that premium still feels comfortable after a sharp share price pullback.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SFL so far? Consider using the pullback, fresh contracts and valuation debate as a prompt to dig into the full picture and decide where you stand by weighing its 3 key rewards and 2 important warning signs.
Looking for more ideas beyond SFL?
If SFL has sparked fresh questions about value, income and risk, broaden your watchlist using focused screeners that surface stocks with very specific strengths.
- Target strong income potential by reviewing companies offering resilient payouts highlighted in the 6 dividend fortresses.
- Hunt for mispriced opportunities by scanning the 32 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
- Prioritize stability and capital protection by leaning on the 30 resilient stocks with low risk scores that flag businesses with more resilient profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com