
Why Infrastrutture Wireless Italiane (BIT:INW) Latest Update Has Investors Watching
Infrastrutture Wireless Italiane (BIT:INW) just released its third quarter and nine-month 2026 results, with both sales and net income lower than in the same periods last year, putting the stock back under closer investor review.
Recent trading tells a mixed story for Infrastrutture Wireless Italiane. The share price is up 18.62% over the past 90 days and 4.69% over the last month, even though the year-to-date share price return is still down 4.65%. The 1-year total shareholder return is 4.29% and the 3-year total shareholder return is lower by 13.49%, suggesting that near-term momentum has improved but longer-term performance has lagged.
Seize this earnings reset in Infrastrutture Wireless Italiane as a chance to scan a curated set of infrastructure peers with resilient balance sheets through our list of solid balance sheet and fundamentals (194 results).The rebound in Infrastrutture Wireless Italiane now meets a small discount to analyst targets, while earnings have just stepped down. Is the market being sensibly cautious, or leaving mispricing on the table as expectations reset?
Most Popular Narrative: 2.8% Undervalued
Infrastrutture Wireless Italiane last closed at €7.49, a touch below the analyst consensus Narrative fair value of €7.70. This frames a modest undervaluation in the analyst consensus Narrative on Simply Wall St that leans on long contracts and measured growth expectations.
The main thing that has to go right is that long-term master service agreements and ongoing demand for new towers, PoPs and indoor DAS continue to offset legal disputes, high leverage and any slowdown from discretionary projects, so that earnings and cash flow remain resilient.
See why 8 investors see Infrastrutture Wireless Italiane as 3% undervalued.
Result: Fair Value of €7.70 (UNDERVALUED)
Still, this narrative can crack if tenant legal disputes weaken those long master service agreements or if high leverage and large dividends start to squeeze investment capacity.
Find out about the key risks to this Infrastrutture Wireless Italiane narrative.
Another View: SWS DCF Flags A Very Different Fair Value
The analyst consensus on Infrastrutture Wireless Italiane points to a fair value near €7.70 and a small 2.8% discount at the current €7.49 share price. A second lens tells a very different story. The Simply Wall St DCF model estimates future cash flow value at €3.84, which implies the stock is trading well above that figure and screens as overvalued on this method. Which lens do you put more weight on when the cash flow view is this far away from the earnings based narrative?
For readers who want to see how that cash flow result is built up line by line, and what would need to change in the inputs for the gap to narrow, Look into how the SWS DCF model arrives at its fair value..
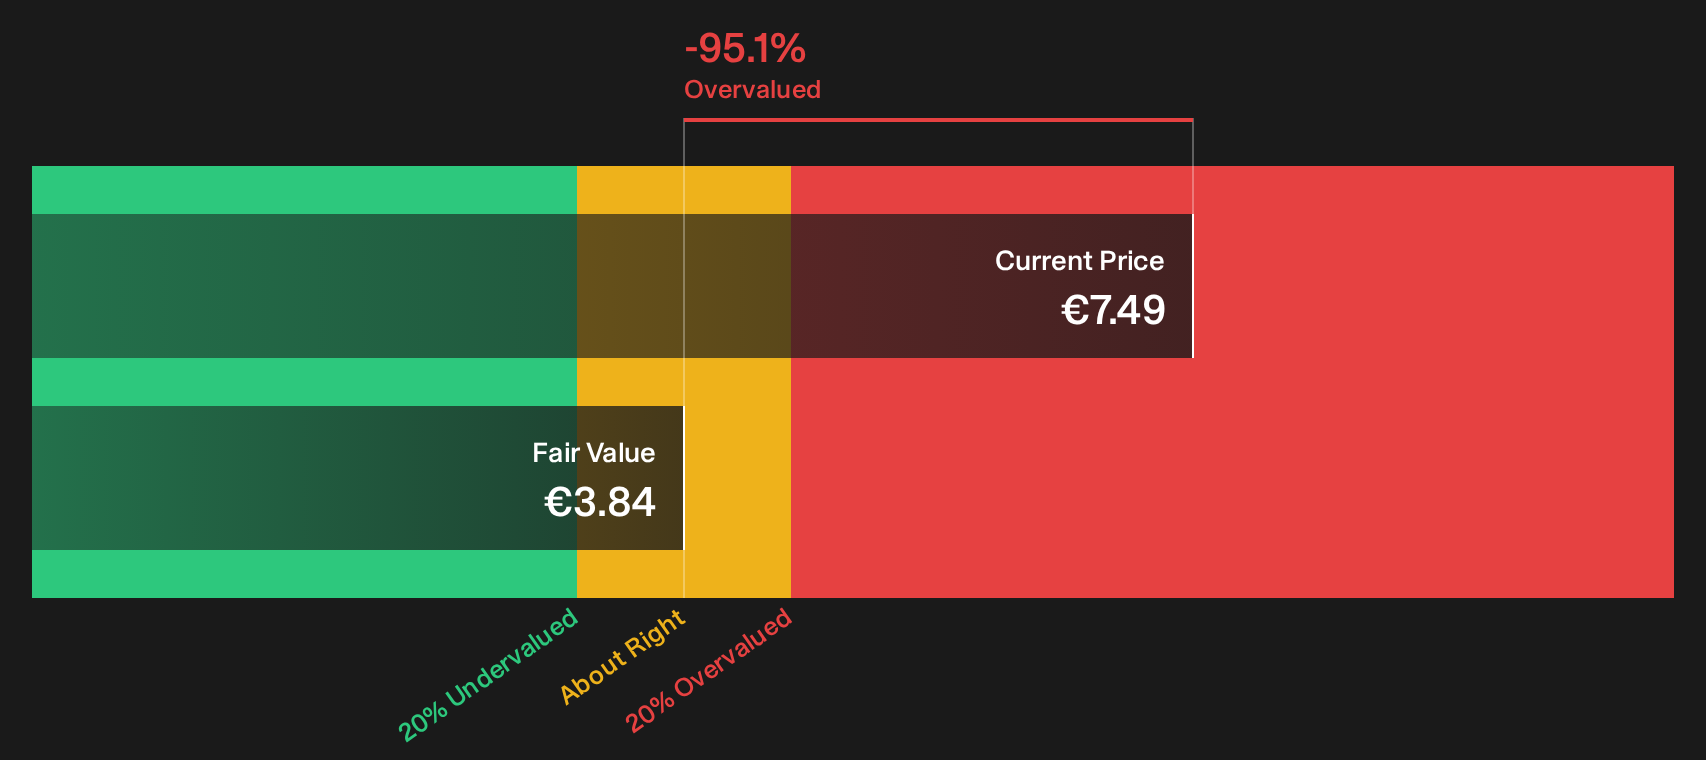
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Infrastrutture Wireless Italiane for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Infrastrutture Wireless Italiane so far. Act while the data is fresh and weigh the trade off between concern and optimism by checking the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Infrastrutture Wireless Italiane?
If you stop at one ticker, you risk missing stronger opportunities that better match your goals, risk comfort and income needs across the wider market.
- Target quality at a discount by scanning a focused set of attractively priced businesses through our 196 high quality undervalued stocks.
- Lock in income potential by reviewing companies that feature resilient payouts and higher yields using the 216 dividend fortresses.
- Prioritise resilience and capital preservation by filtering for companies with more robust financial footing through the 208 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com