
Earnings Beat Could Be A Big Deal For Gibson Energy Stock (TSX:GEI)
- Gibson Energy reported third quarter 2026 sales of C$3,688.77 million and net income of C$77.03 million, alongside record Infrastructure segment adjusted EBITDA and affirmed a quarterly dividend of C$0.45 per share payable in January 2027.
- The combination of higher earnings, strong Infrastructure EBITDA and a sanctioned 50% capacity expansion of the Chauvin Pipeline may influence how Gibson Energy’s fee based cash flows and future capital projects are considered together.
- This article reviews how Gibson Energy’s investment narrative is affected by record Infrastructure EBITDA and the newly approved Chauvin expansion.
Scan how Gibson Energy’s Infrastructure story compares with other pipeline and energy infrastructure opportunities by lining up its record EBITDA and dividend profile against 16 nuclear energy infrastructure stocks.
Gibson Energy Investment Narrative Recap
To own Gibson Energy, you have to be comfortable with a story built around fee based infrastructure, steady utilization at terminals and pipelines, and a relatively high reliance on dividends. The analyst consensus Narrative on Simply Wall St already assumes earnings growth but falling revenue, so the Q3 2026 beat and record Infrastructure EBITDA mainly confirm that the existing project pipeline still matters most in the near term.
The key short term swing factor remains execution on growth projects while keeping leverage and payout levels manageable. The biggest risk is that funding all these initiatives with already stretched coverage of interest and dividends leaves limited room if crude volumes, marketing contributions or contract renewals soften from here.
The announcement that feels most relevant right now is the affirmed C$0.45 quarterly dividend, backed by an 82% trailing payout ratio alongside C$192.9 million of consolidated adjusted EBITDA in the quarter. That combination underlines how tightly Gibson Energy’s shareholder return profile is linked to Infrastructure cash generation and to keeping assets well contracted.
For catalysts, the dividend decision ties directly into execution on the sanctioned Chauvin Pipeline expansion and other projects like Hardisty and Wink to Gateway. If those assets are delivered on time and run at healthy utilization, they can support the current payout framework, whereas any delay, cost pressure or weaker oil throughput would quickly test interest coverage and the flexibility around that dividend level.
Gibson Energy's narrative projects CA$11.2b revenue and CA$312.1 million earnings by 2029. This assumes revenue declining 6.3% per year and an earnings increase of about CA$112.3 million from current earnings of CA$199.8 million.
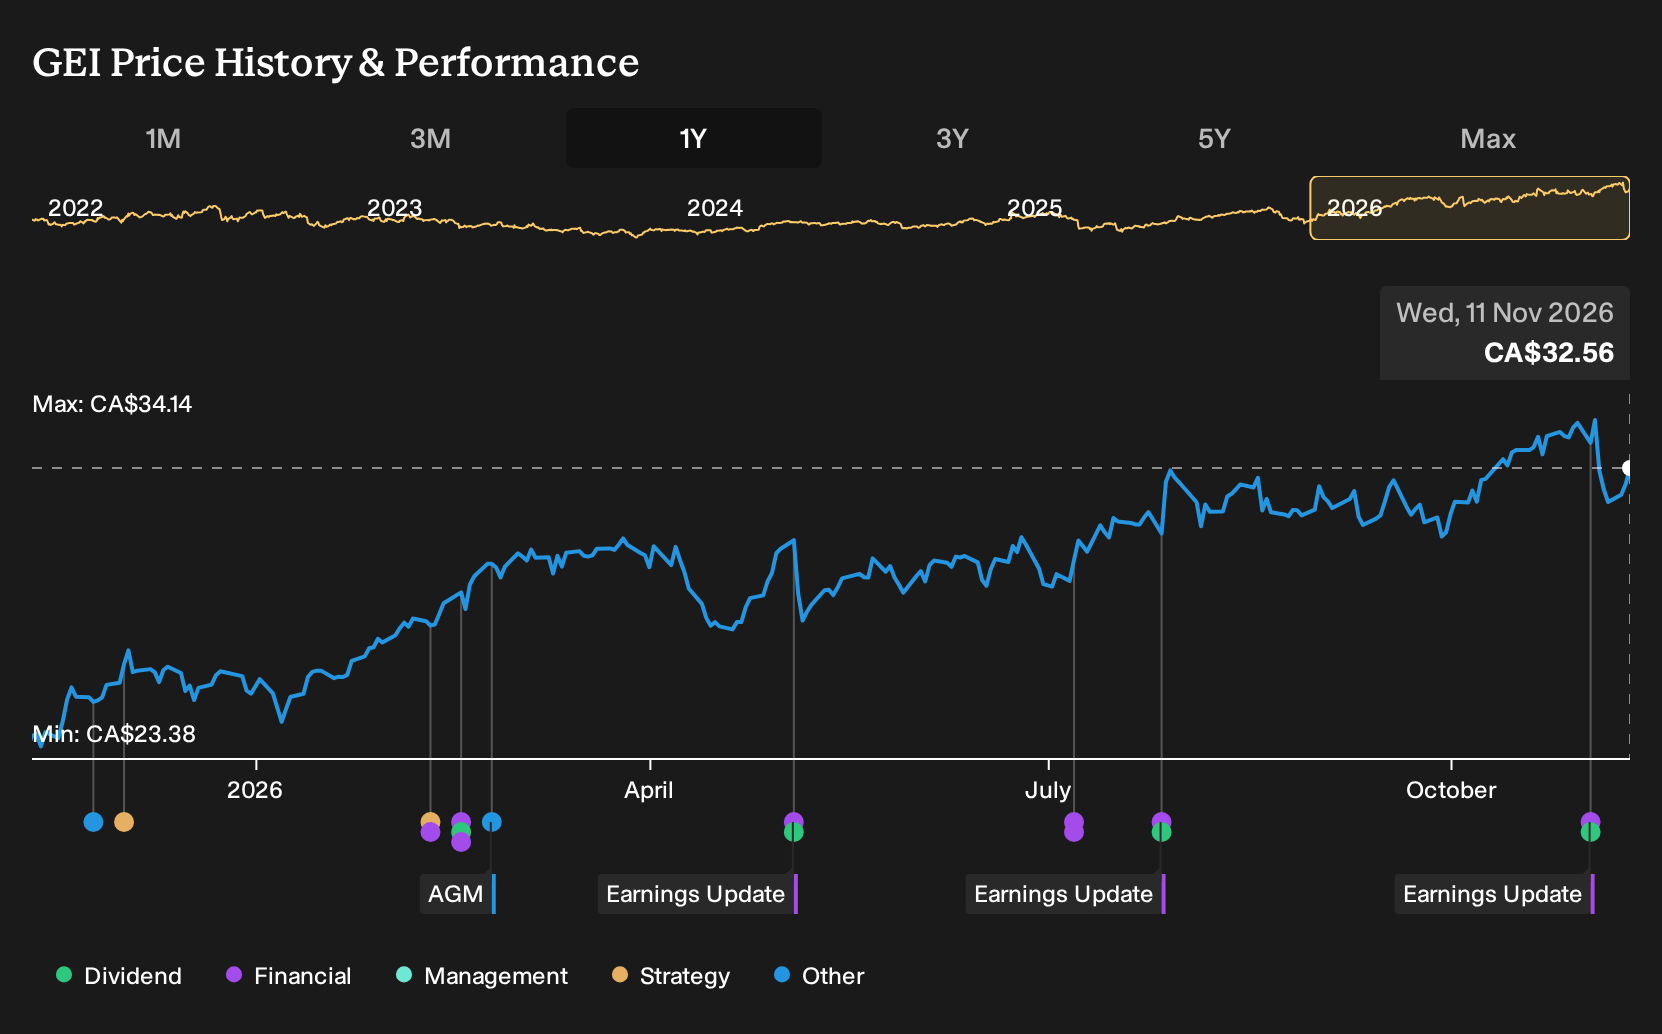
Uncover why Gibson Energy's fair value points to a 7% potential upside to its current price, a discount that could close sooner than anticipated.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly C$34.79 to C$80.25, which shows just how far apart retail views on Gibson Energy can be. Use that spread as a prompt to stress test your own stance against project execution risk, dividend funding pressure, and the potential impact of longer term energy transition trends.
Explore another Gibson Energy fair value estimate, including one that suggests as much as 146% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gibson Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gibson Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gibson Energy's overall financial health at a glance.
Looking for more investment ideas beyond Gibson Energy?
Once you have a view on Gibson Energy, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St screener gives you a structured way to do that so you can line up potential additions to your watchlist by quality, resilience and yield rather than by headlines.
- If you want income potential with an emphasis on payout strength, scan for high-yield opportunities built around 3 dividend fortresses.
- For investors who care most about balance sheet resilience and underlying fundamentals, filter candidates through a list of solid balance sheet and fundamentals (5 results) to see which businesses clear your quality bar.
- If you prefer to hunt for future leaders before they are widely followed, broaden your research with a 7 high quality undiscovered gems that match your return and risk preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com