
RPC Stock Price Outlook After Earnings Loss Despite Higher Sales
- RPC, Inc. reported third quarter 2026 sales of US$467.74 million with a net loss of US$41.93 million, and for the first nine months sales of US$1,383.36 million with a net loss of US$29 million, while affirming a regular US$0.04 per share quarterly dividend.
- The shift from net income a year ago to losses in both the quarter and year to date, despite higher sales, points to pressure on costs or pricing that investors will likely watch closely in relation to RPC's ongoing dividend payments.
- We will now look at how this swing to quarterly losses, alongside the maintained dividend, relates to RPC's existing investment narrative.
Stress test RPC's latest loss and dividend decision against peers by scanning a curated set of service providers with resilient balance sheets through the list of solid balance sheet and fundamentals (24 results) tool.
RPC Investment Narrative Recap
To own RPC, you need to be comfortable with an oilfield services business that is currently loss making but still investing in higher tech tools and larger coiled tubing capacity. The analyst consensus Narrative on Simply Wall St leans on that shift toward higher value work as a key driver. The latest quarter showed sales of US$467.74 million and a net loss of US$41.93 million, so the near term focus sits squarely on whether pricing and costs can line up better.
The most important short term swing factor is execution in services like MetalMax motors, large diameter coiled tubing and cavern gas storage inspections, because these areas underpin the mix shift thesis. The biggest risk right now is that cost pressure and any weakness in oilfield activity keep net margins compressed, which would make it harder for management to justify ongoing capital spending and the current dividend.
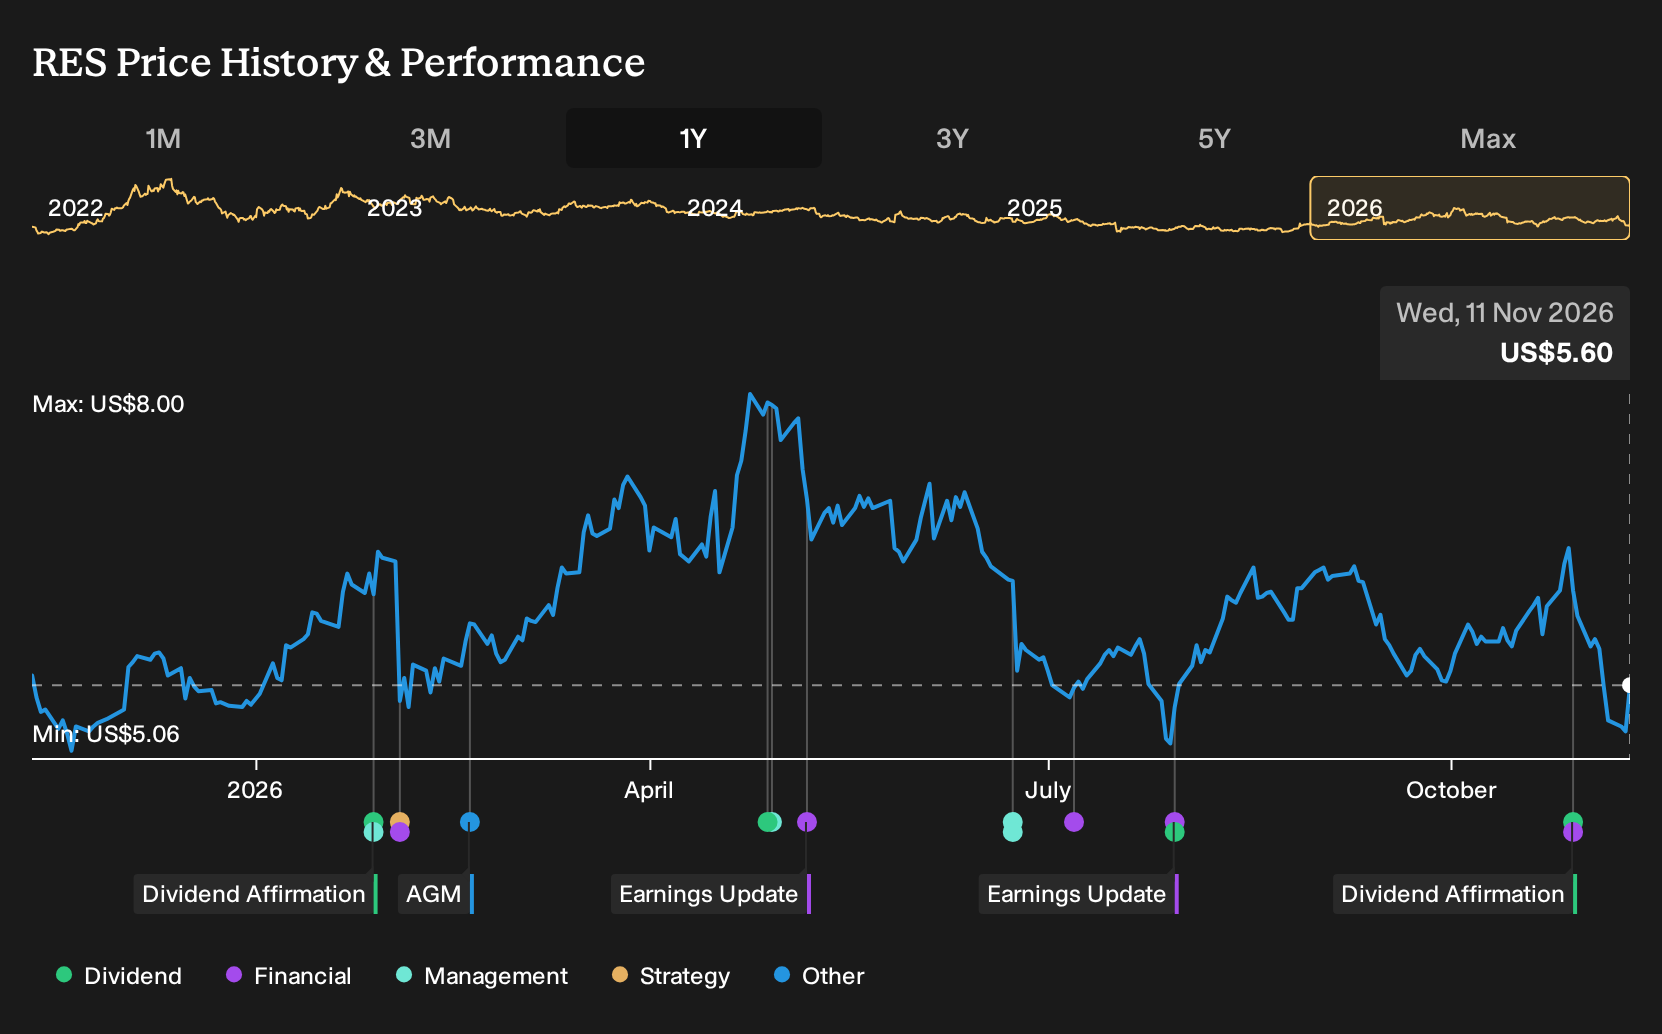
The dividend affirmation at US$0.04 per share alongside a quarterly loss is the announcement that ties most directly to this earnings release. RPC kept its payout even as the firm reported a net loss of US$41.93 million for the quarter and US$29 million for the first nine months of 2026. That decision brings the existing dividend risk into sharper focus for income focused holders.
Analysts already flagged, in the analyst consensus Narrative on Simply Wall St, that the dividend yield of 2.86% is not well covered by earnings or free cash flows. With the company still reporting losses, readers will probably pay closer attention to how quickly operations in higher tech tools, coiled tubing upgrades and recurring cavern inspection work can support more consistent cash generation if the dividend is to remain a core part of the RPC story.
RPC's current analyst narrative points to revenues of US$1.9 billion and earnings of US$155.9 million by 2029. This outlook is built on forecast top line growth of 2.4% per year and a move from current earnings of a US$33.1 million loss to that US$155.9 million profit, which is an earnings swing of about US$189 million.
Uncover why RPC's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most cautious analysts focus on capital intensity as the key risk for RPC. Before this earnings release, the lowest forecasts were built around revenue of about US$1.8b and earnings of US$91.4 million by 2029, which is far below the consensus. That camp already saw limited room for error, so this shift to losses and a maintained dividend may push their narrative even more toward the downside. Use that gap in expectations as a prompt to compare several viewpoints, not just one headline number.
Explore 3 other RPC fair value estimates, including one that suggests as much as 55% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your RPC research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RPC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RPC's overall financial health at a glance.
Looking for more investment ideas beyond RPC?
Once you have a view on RPC, it often helps to set that story alongside a wider watchlist of companies with different balance sheet strength, valuation profiles and income characteristics. The Simply Wall St Screener can help you quickly build that comparison set without wading through every ticker on the market.
- If capital preservation is high on your list, check out companies that score well on resilience through 30 resilient stocks with low risk scores for a starting pool of candidates.
- For readers hunting for mispriced opportunities, scan the market for quality businesses trading below their estimated worth using the 32 high quality undervalued stocks filter.
- If income is the priority, focus on cash return potential by reviewing a curated group of higher yielding payers through the 6 dividend fortresses screen.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com