
Is SoftBank Group (TSE:9984) Undervalued Following Its Malaysia AI Infrastructure Deal?
SoftBank Group (TSE:9984) has moved back into the spotlight after agreeing with Grab and Petroleum Sarawak Berhad to commit an initial US$1.85b to AI infrastructure projects across Malaysia.
For SoftBank Group, this Malaysia AI commitment comes after a tough stretch in the market, with the share price down 33.57% over the past month and 16.47% year to date. However, the 3-year total shareholder return of 158.88% and 5-year total shareholder return of 122.18% still reflect a very strong longer term payoff for investors who stayed in through the volatility.
Capture how SoftBank Group’s AI push compares by scanning a curated set of 53 AI infrastructure stocks that are already shaping the next wave of compute buildouts.SoftBank Group is leaning hard into AI infrastructure just as its share price has stepped back sharply. The business case looks ambitious. The open question is whether the current valuation already offers enough compensation for that volatility.
Most Popular Narrative: 50.5% Undervalued
On the Simply Wall St analyst consensus Narrative, SoftBank Group’s fair value of ¥7,782.47 sits well above the last close at ¥3,855. That gap reflects a view that the market is heavily discounting the group’s AI build out, funding structure and future cash flows. The model uses a 5.0% discount rate.
Arm’s AGI CPU orders of more than US$2b across the current and next fiscal years, which are not yet fully reflected in formal guidance due to wafer capacity limits, point to additional royalty and product revenue that could support future earnings and lift SoftBank Group’s consolidated net income.
OpenAI’s enterprise products such as Codex and ChatGPT Work, which have seen weekly active users for Codex move from 400,000 to 10,000,000 within seven months, create scope for higher usage based fees that can feed through to SoftBank Group’s share of equity value and potential future gains when liquidity events occur.
See why 23 investors see SoftBank Group as 50% undervalued.
Result: Fair Value of ¥7,782.47 (UNDERVALUED)
Still, the story can flip fast if SoftBank Group faces tighter credit on roughly US$65b of AI funding, or longer delays to key liquidity events like OpenAI.
Find out about the key risks to this SoftBank Group narrative.
Another View: SoftBank Group Through The P/E Lens
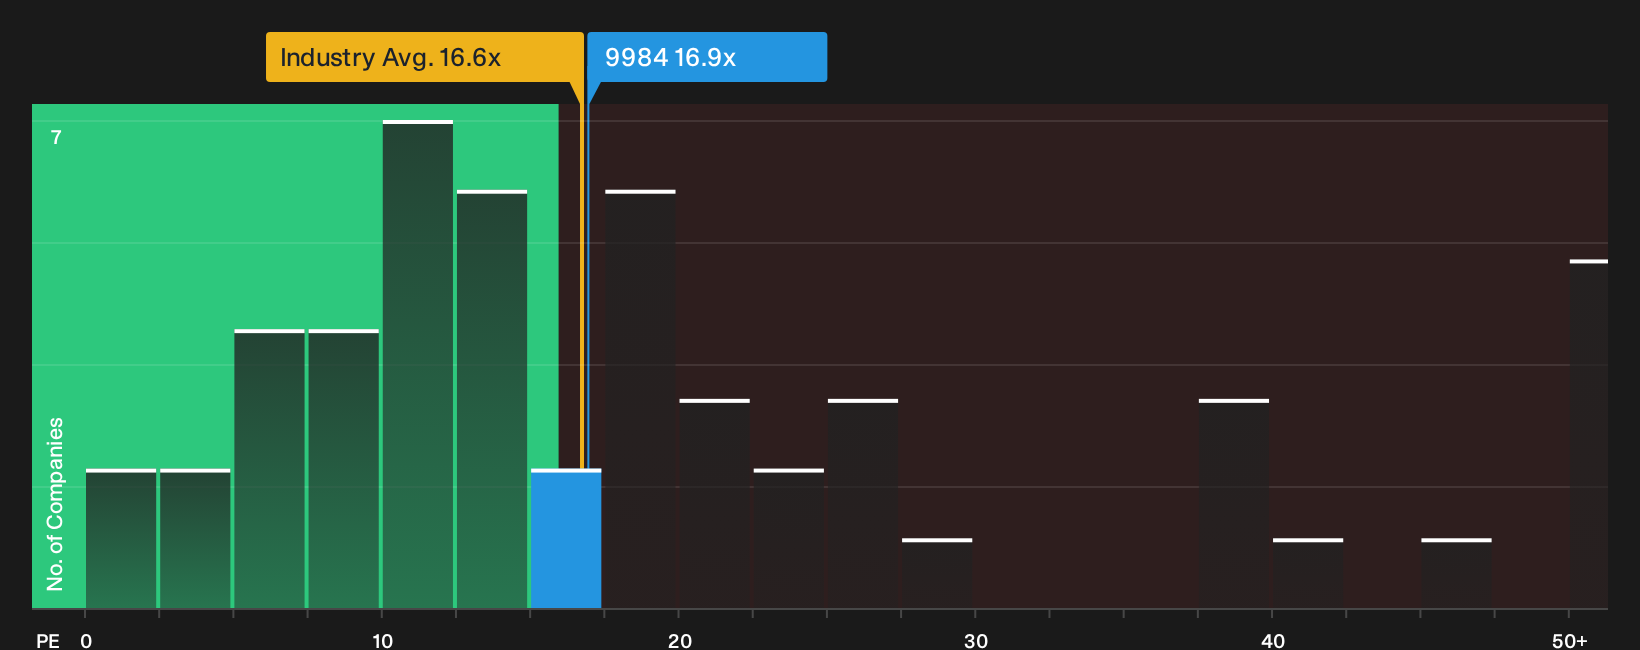
SoftBank Group might look undervalued against the ¥7,782.47 fair value from the analyst narrative, but the P/E of 16.9x paints a tighter picture. It is only slightly above the Asian wireless telecom average at 16.6x and above the fair ratio of 14.5x, which points to some valuation risk if sentiment cools.
Put simply, the current multiple already bakes in more optimism than the fair ratio suggests. The real question is whether SoftBank Group can deliver enough AI driven earnings to keep investors comfortable with that extra premium or even push it higher over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment around SoftBank Group leaves you undecided, act promptly to review the data for yourself and weigh both sides using the 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond SoftBank Group?
If SoftBank Group has sharpened your focus on AI and valuation, you can broaden your opportunity set now before the next wave of strong ideas moves without you.
- Target potential value gaps by scanning a curated 24 high quality undervalued stocks that pair robust fundamentals with prices that may not yet reflect their full potential.
- Strengthen your income stream by reviewing a hand picked set of 29 dividend fortresses that combine higher yields with disciplined payout histories.
- Prioritize resilience by filtering for a 19 resilient stocks with low risk scores that focuses on sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com