
Yesway (YSWY) Faces A Valuation Test Following Its Midwest Store Sale
Yesway (YSWY) just exited most of its Midwest footprint, closing a US$21 million sale of convenience stores in Iowa and Kansas to Texas based Now & Forever.
The sale comes after a strong run in the Yesway share price, with a 30 day share price return of 21.33% and a year to date share price return of 20.82% from a latest close of US$25.65. Momentum has picked up in the past month compared with the more modest 90 day share price return of 5.34%, which suggests that investors are reassessing both growth prospects and the risk profile as the business reshapes its footprint.
Scan other reshaping consumer retailers with a similar footprint tilt using our curated list of 32 high quality undervalued stocks as potential reference points beside Yesway.
Yesway has just shrunk its Midwest footprint, yet the share price has run hard into that reset. Does the balance of risk and potential reward still lean toward buyers at US$25.65 once you line it up against fundamentals?
Preferred P/E of 9.8x: Is it justified?
Yesway screens as cheap on earnings, with a P/E of 9.8x at a last close of $25.65, compared with both peers and the wider US consumer retailing group. That gap points to investors pricing the stock below what its recent profit trajectory and cash flow valuation might suggest.
The P/E ratio compares what you pay for each dollar of earnings. For a retailer like Yesway that already generates profits, it is a direct way to see how the market values those earnings relative to similar businesses in the sector.
On that yardstick, the discount is clear. The P/E of 9.8x is well below the peer average of 15.2x and also below the broader US consumer retailing industry at 18.6x. Against an estimated fair P/E of 12x, the current level points to investors applying a heavier discount than the fair ratio implies the market could move toward.
Explore the SWS fair ratio for Yesway.
Result: Price-to-earnings of 9.8x (UNDERVALUED)
Still, the story carries clear risks, including annual net income that recently declined 4.10% and a footprint reset that could disrupt Yesway’s revenue growth of 8.55%.
Find out about the key risks to this Yesway narrative.
Another view on Yesway’s value
The earnings based picture points to Yesway looking cheap, yet the SWS DCF model paints an even stronger tilt. That framework puts future cash flow value at $140.96 per share versus today’s $25.65, which suggests a very wide gap. As an investor, how much weight do you give to a model that far out on the spectrum?
Look into how the SWS DCF model arrives at its fair value.
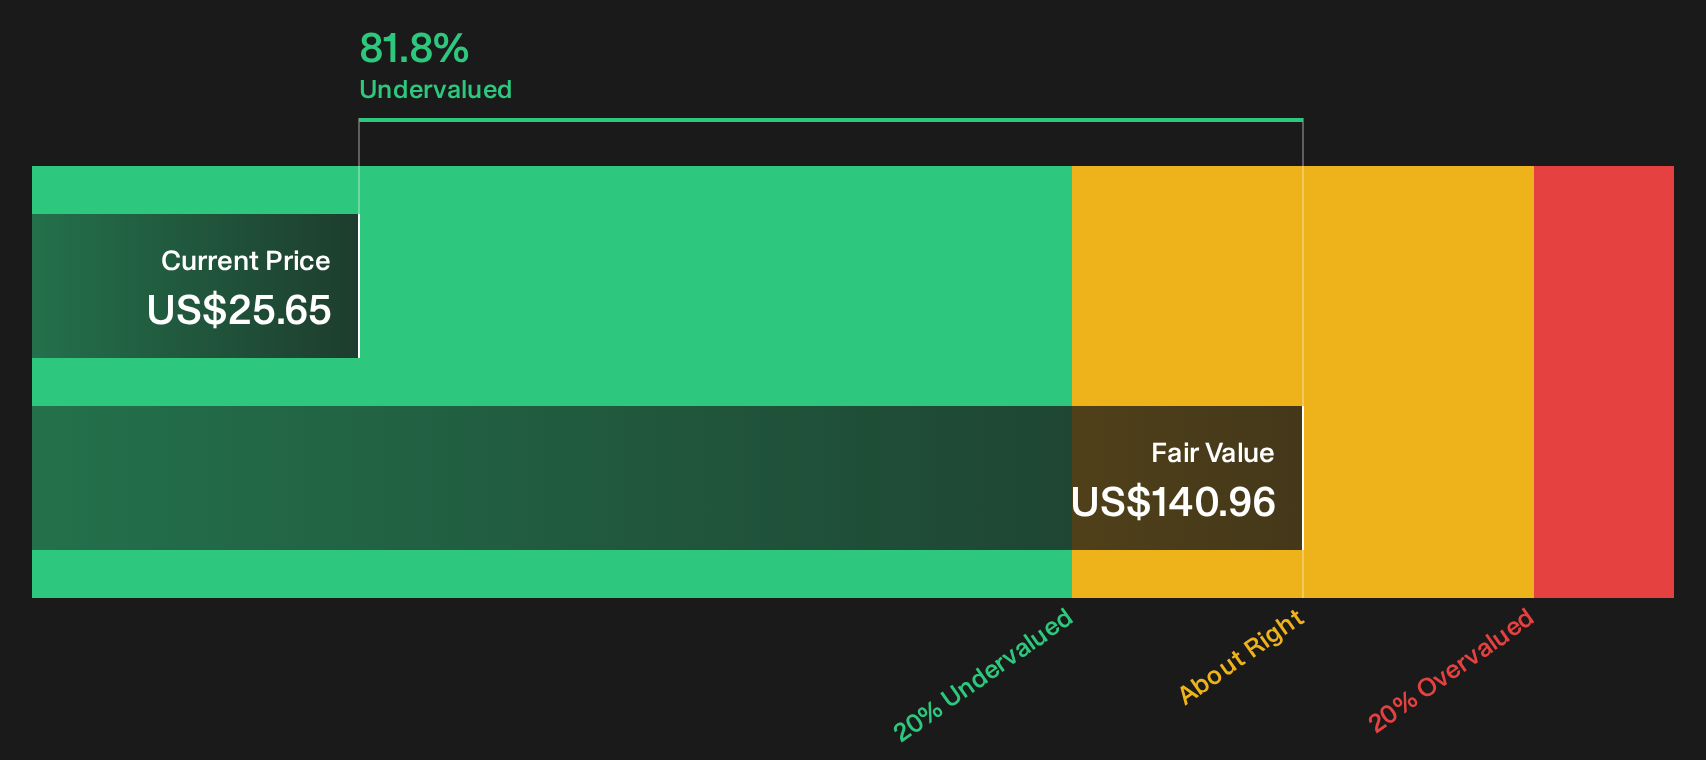
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yesway for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big valuation gaps like this often split opinion among Yesway investors, so if you want to move fast and rely on more than headlines, weigh up the full balance of risks and potential upsides through the 3 key rewards and 2 important warning signs.
Want more ideas beyond Yesway?
If Yesway has sharpened your focus on value and quality, do not stop here. A few targeted screens can quickly surface other stocks worth your attention.
- Target dependable cash generators by scanning companies with solid balance sheets and fundamentals through this curated list of solid balance sheet and fundamentals (24 results).
- Hunt for strong businesses priced below what their quality might imply by reviewing this focused set of 32 high quality undervalued stocks.
- Spot under the radar opportunities with robust financial footing by running through this hand picked pool of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com