
Ubiquiti (UI) Posts Strong Growth And A Dividend, Is The Valuation Too Rich?
Ubiquiti (UI) just paired a first quarter earnings release with a fresh dividend decision, as the board approved a US$1.00 per share cash payout alongside higher year over year sales and profit.
Ubiquiti’s latest print and dividend decision land after a strong run, with the share price up 21.11% over the past week and 19.98% year to date, and longer term momentum reflected in a three year total shareholder return of roughly 4.8x.
Scan how Ubiquiti’s latest results compare with other fast growing, high quality networks and hardware plays by running through our curated list of 19 high quality undiscovered gems.
After a surge like this, Ubiquiti now forces a practical choice: lean into the momentum at today’s price, or wait for a cooler entry that better matches the fundamentals about to be unpacked.
Preferred P/E of 38.3x: Is it justified?
On valuation, Ubiquiti trades on a P/E of 38.3x, which represents a clear premium on the $679.42 share price compared with several peers.
The P/E multiple compares the current market price per share to earnings per share and gives a quick sense of how much investors are paying for each dollar of profit. For a hardware and networking specialist like Ubiquiti, that ratio often reflects expectations around future earnings strength, product traction across regions, and the perceived durability of current profitability.
Analysts describe Ubiquiti as good value versus a peer average P/E of 70x, which suggests earnings are priced lower than some comparable communications stocks. At the same time, the multiple stands above the broader US Communications industry on 24.7x and above an estimated fair P/E of 29.9x, which indicates the market is assigning a relatively rich valuation that could compress if sentiment or growth assumptions soften.
Result: Price-to-Earnings of 38.3x (OVERVALUED)
Explore the SWS fair ratio for Ubiquiti.
Still, Ubiquiti’s premium 38.3x P/E and heavy exposure to hardware spending cycles leave little room for disappointment if demand or sentiment cools.
Find out about the key risks to this Ubiquiti narrative.
Another view on Ubiquiti’s valuation
The SWS DCF model points a different way, with Ubiquiti’s estimated future cash flow value sitting at $492.32 per share versus the current $679.42 price, which screens as overvalued on this measure. That gap raises a simple question for you: Is the market paying up too far in advance?
Look into how the SWS DCF model arrives at its fair value.
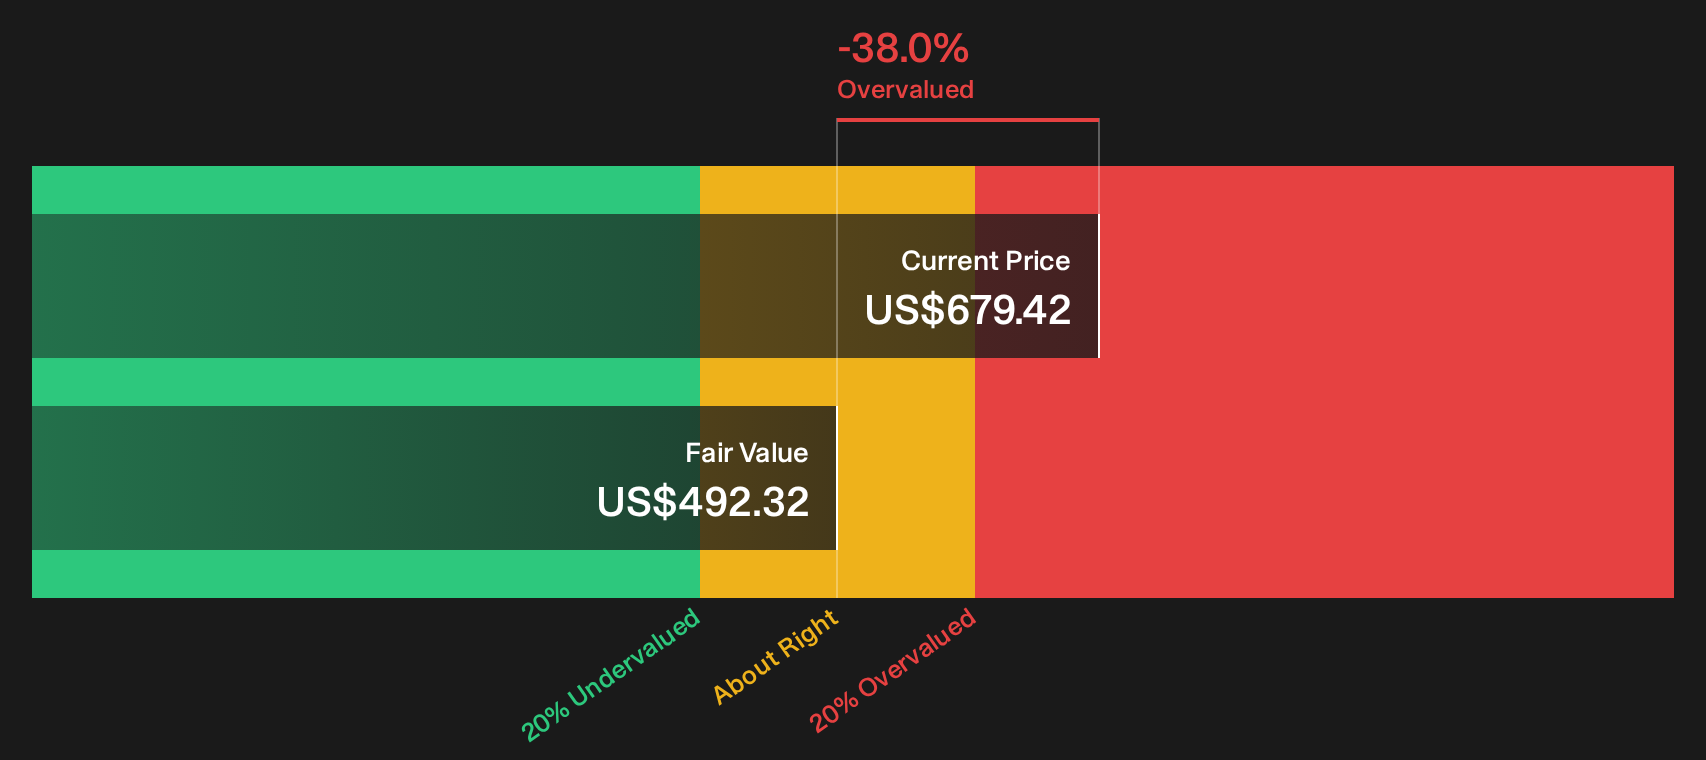
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ubiquiti for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the mixed valuation message around Ubiquiti leave you excited or cautious? Consider your options while the data is fresh and test your own thesis against the 2 key rewards.
Looking for more investment ideas beyond Ubiquiti?
Ubiquiti’s setup might be interesting, but your next strong move often comes from comparing it with other opportunities that fit clear, disciplined criteria.
- Target resilient balance sheets and steady fundamentals by filtering for companies in our list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value opportunities by scanning through 32 high quality undervalued stocks before prices move away from your comfort zone.
- Prioritize stability and income by checking companies in the 6 dividend fortresses that align with your own payout expectations and risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com