
Black Stone Minerals (BSM) Moved Today, What Is Behind The Attention?
Black Stone Minerals (BSM) has just released third quarter and nine month 2026 figures, showing lower revenue, net income, and production volumes compared with the same period a year earlier.
Recent trading has been choppy for Black Stone Minerals, with a 1-day share price return of 2.27% but a 30-day move that is down 5.80%, hinting at fading short term momentum after the weaker third quarter update. Even so, the year to date share price return of 3.48% and a 1-year total shareholder return of 11.11% stand alongside a much stronger 5-year total shareholder return of 98.37%. This keeps the longer term story intact for investors focused on income and mineral exposure.
Scan beyond Black Stone Minerals and compare its latest update with a curated 19 high quality undiscovered gems that are quietly building strong fundamentals in the background.
After a softer quarter and a share price that has slipped over the past month, Black Stone Minerals now trades below both analyst targets and some intrinsic value estimates. How wide is that gap in practical terms for investors?
Most Popular Narrative: 13% Undervalued
Black Stone Minerals last closed at $13.98, against a fair value of $16.00 in the analyst consensus Narrative on Simply Wall St. This estimate applies a 7.24% discount rate and ties that valuation directly to revenue and earnings forecasts.
The expansion of the Shelby Trough and new development agreements, now covering about 500,000 gross acres with minimum drilling obligations ramping to 50 gross wells per year by 2031, continue to tie Black Stone Minerals to Gulf Coast natural gas demand and could support higher royalty revenue and distributable cash flow.
See why 20 investors see Black Stone Minerals as 13% undervalued.
Result: Fair Value of $16.00 (UNDERVALUED)
Still, the narrative for Black Stone Minerals could be knocked off course if EBITDA margin pressure persists or if approximately US$300 million of acquisitions fail to lift cash flow.
Find out about the key risks to this Black Stone Minerals narrative.
Another View: What Black Stone Minerals' P/E Is Really Saying
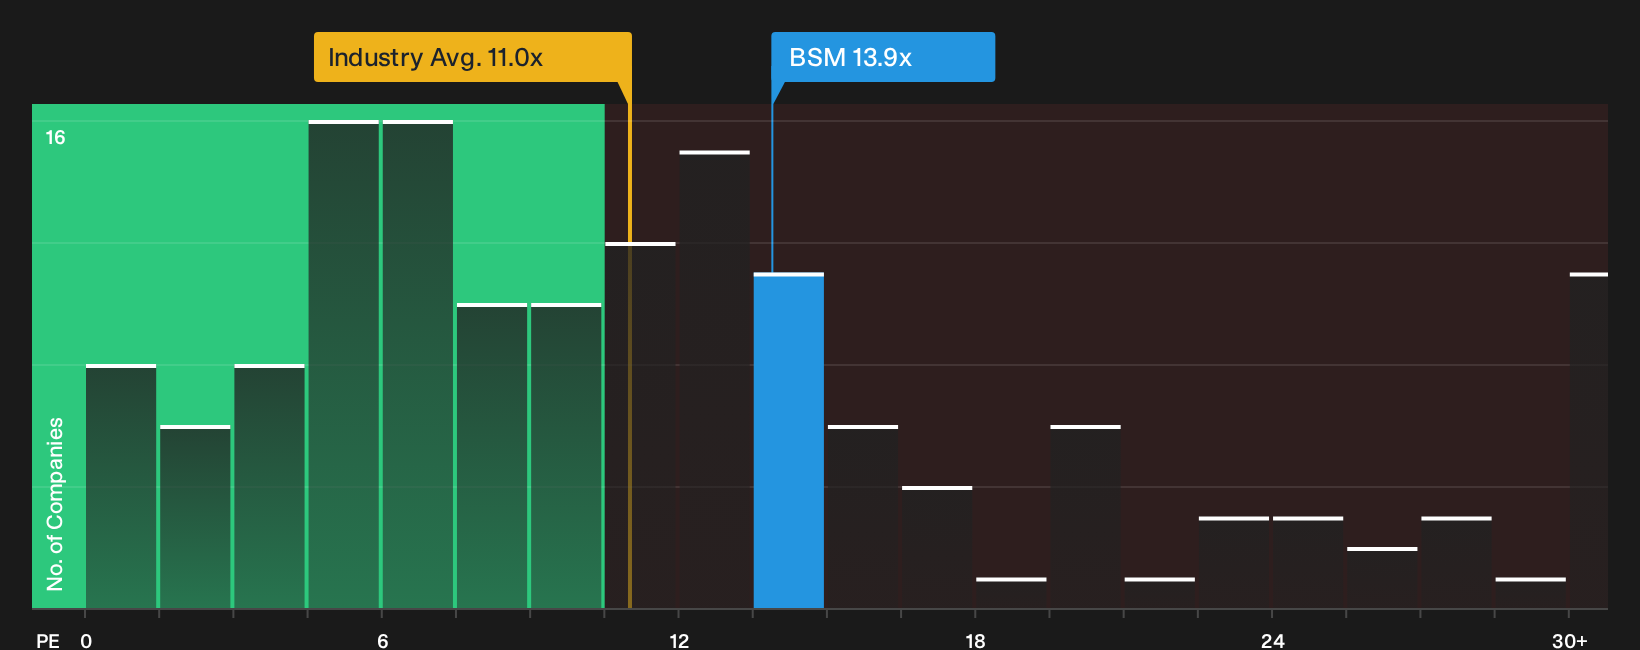
On a simple earnings multiple, Black Stone Minerals screens as expensive. The unit trades on a P/E of 13.9x, compared with 11x for the wider US oil and gas group and 12.3x for its direct peers, so investors are already paying a premium for each dollar of profit.
Yet the fair ratio for Black Stone Minerals is estimated at 18.3x earnings, which is materially higher than both its current P/E and the sector yardsticks. That gap points to a trade off. There is less obvious downside protection if sentiment turns, but also room for the multiple to move closer to the fair ratio if the story holds together. Which side of that trade off are you really underwriting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the story so far. If you want to move quickly and test the bullish and cautious threads against hard numbers, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Black Stone Minerals?
If you only stop at Black Stone Minerals, you risk missing other opportunities that match your goals, income needs, and appetite for steadier returns.
- Zero in on quality by using the 32 high quality undervalued stocks that filters for companies combining stronger fundamentals with prices that sit below their estimated worth.
- Turn income into a focus and scan the 6 dividend fortresses to see which higher yielding businesses pair payouts with more durable balance sheets.
- Dial down portfolio stress and shortlist steadier candidates through the 30 resilient stocks with low risk scores that highlights stocks with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com