
What United Therapeutics Holders Bought Into
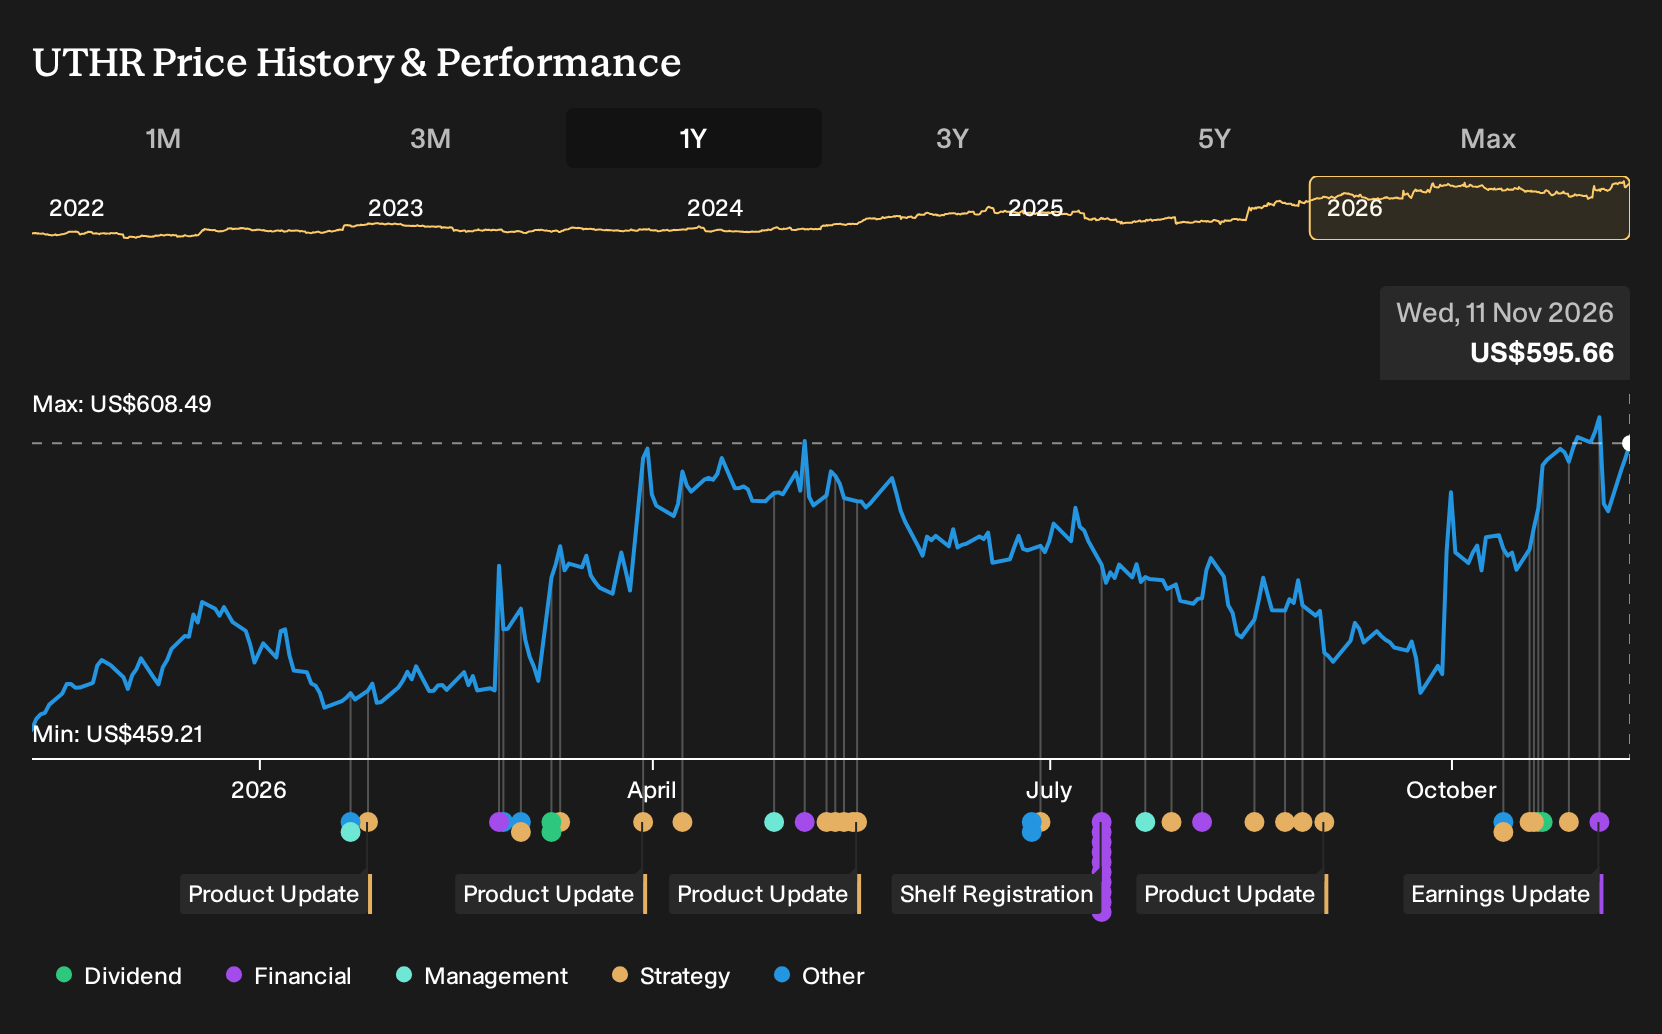
If you only glanced at headlines, the Phase 3 wins for ralinepag and Tyvaso in pulmonary disease or the deal for Thymmune’s thymic cell program might look like the whole story at United Therapeutics. Holding United Therapeutics over the past year would have returned 29.1%, including dividends. If you had been deciding on 11 November 2025, what did you need to believe about organ manufacturing and PAH leadership before any of this fresh news hit the tape?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
United Therapeutics is not the only name tied to this theme. Zero in on 36 healthcare AI stocks and compare how each one is priced.
The Two United Therapeutics Stories Investors Were Weighing
The shares cost US$459 at the start of the period. Anyone looking at United Therapeutics then had to decide whether pulmonary arterial hypertension strength and organ manufacturing efforts could justify paying more than that.
The bullish narrative pointed to a fair value of US$510, built on the idea that revenue could grow 14.0% a year with profit margins rising to 45.5% and earnings reaching US$2.1b by 2028.
The bearish case argued for a fair value of US$295, built around earnings declining to US$962.0m by 2028 and margins compressing to 29.0% as patents aged and biosimilars advanced.
What The Evidence Did To The United Therapeutics Argument
The FDA clearance for United Therapeutics to begin the EXPRESS UHeart xenotransplant trial directly addressed the organ manufacturing pillar in the bullish script, while the Thymmune deal and LungFX approval added extra transplant tools. At the same time, Q3 2026 results showed revenue at US$832.5m but net income at US$258.6m, with net margin slipping to 31.1%. Taken together, the evidence cut both ways.
The useful takeaway is clear. When a story leans on future high-margin platforms, track whether new approvals and trials arrive alongside stable or improving reported net margin rather than just headline pipeline milestones.
What United Therapeutics' Price Already Bakes In
United Therapeutics now trades at US$596, up 29.1% over the past year, with this bearish analyst Narrative on Simply Wall St placing its Fair Value below that level.
The Narrative focuses on flat earnings and heavier spending for fibrosis and organ platforms. A buyer today effectively assumes those efforts translate into durable revenue and margin strength, so how much weight should you place on its concern about execution risk and higher ongoing costs?
"Although United Therapeutics now has highly statistically significant Phase 3 data in idiopathic pulmonary fibrosis and a supplemental application under FDA review, the recent revenue decline of 1.9% year over year and withdrawal of 2026 growth guidance signal that execution risk in converting pulmonary fibrosis trial success into durable revenue growth is higher than the current long-term revenue targets imply."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 34% below our estimate - uses AI centric networking and cloud infrastructure to emphasize recurring service revenue.
- Company 2 - 31% below our estimate - expands an app driven physical store network while managing traffic and occupancy headwinds.
- Company 3 - 16% below our estimate - grows a branded teahouse franchise system as newer outlets alter store economics.
That is three of the list. See every one of the 32 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com