
Will Strong Earnings And Dividend Hike Change Peyto Exploration & Development's (TSX:PEY) Narrative
- Peyto Exploration & Development reported third quarter 2026 revenue of C$400.75 million and net income of C$155.65 million, with basic EPS from continuing operations of C$0.75. For the first nine months of 2026, revenue was C$1,167.59 million and net income was C$433 million.
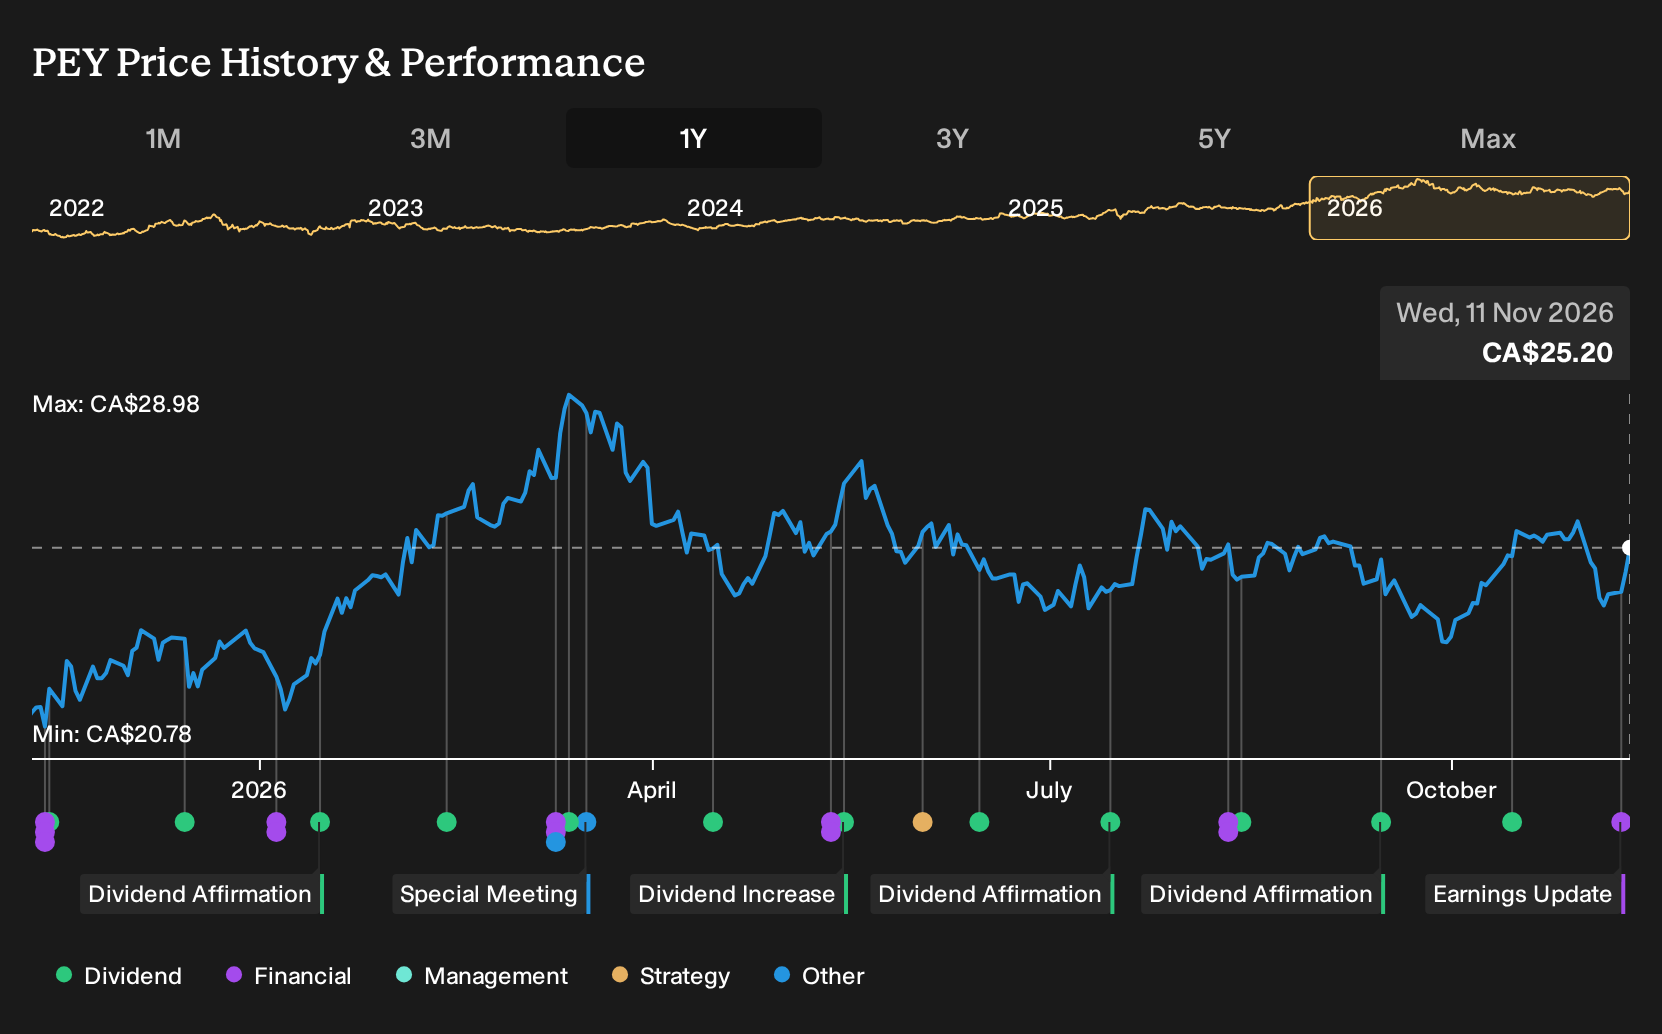
- The producer lifted its monthly dividend to C$0.13 per share and paired that with higher production, greater liquids output and lower controllable cash costs of C$1.02 per Mcfe. This highlights how Peyto Exploration & Development is currently using operational efficiency to support cash returns.
- We will now see how Peyto Exploration & Development's investment narrative could be influenced by these earnings results and the higher dividend.
Compare Peyto Exploration & Development's mix of higher liquids output, lower controllable costs and a rising payout with hand-picked peers using the 3 dividend fortresses
Peyto Exploration & Development Investment Narrative Recap
For Peyto Exploration & Development, the key belief supporting the analyst consensus narrative on Simply Wall St is that a low cost, liquids rich Alberta gas producer can keep cash flow relatively steady through efficiency, hedging and disciplined spending, even when sector sentiment is weak. The latest quarter, with higher revenue, net income and EPS plus lower controllable cash costs and more liquids, aligns with that operational story.
The main near term swing factor still appears to be natural gas pricing and any Alberta specific regulatory or operating disruption, because the asset base is highly concentrated. The increased dividend lifts the short term appeal but also raises the risk that a prolonged period of weaker gas prices could pressure payout sustainability if conditions turn against Peyto Exploration & Development.
The move that most directly ties into this update is the 18% increase in the monthly dividend to C$0.13 per share, on top of stronger quarterly earnings and lower controllable cash costs of C$1.02 per Mcfe. For you as a shareholder or potential shareholder, that combination links current operating performance with near term cash returns from Peyto Exploration & Development.
Higher liquids output and the focus on Cardium drilling contribute to that same catalyst because liquids volumes supported recent revenue and profit figures. At the same time, the higher payout sits beside a preliminary 2027 capital budget of C$475 million to C$525 million. This means execution risk around spending discipline, Alberta focused operations and future gas prices remains important when considering how durable this dividend level might be.
Peyto Exploration & Development's current earnings are CA$494.0 million. Analysts expect earnings to reach CA$436.5 million by 2029, which implies an earnings decline of about CA$57.5 million from today, alongside forecast revenue of CA$1.6 billion and annual top line growth of 8.6% over the next few years.
Uncover why Peyto Exploration & Development's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from C$27.75 to about C$118 per share, so private investors are clearly not aligned on Peyto Exploration & Development. That spread sits against Alberta concentration risk and future LNG driven gas demand, which together can materially influence how you think about earnings resilience and dividend durability. Readers should expect wide disagreement and explore multiple viewpoints before forming a view.
Explore 2 other Peyto Exploration & Development fair value estimates, including one that suggests as much as 370% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Peyto Exploration & Development research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Peyto Exploration & Development. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Peyto Exploration & Development's overall financial health at a glance.
Looking For More Investment Ideas Beyond Peyto Exploration & Development?
If the Peyto Exploration & Development story has you thinking about income, quality and valuation together, it can be useful to scan a wider opportunity set using the Simply Wall St Screener. That way you can pressure test your thesis against companies with different balance sheets, payout profiles and risk levels.
- For investors who care most about stability and capital protection, consider starting with a set of companies screened for resilience and low risk using the 9 resilient stocks with low risk scores.
- If yield is your priority and Peyto's higher dividend caught your attention, you can compare it with other income focused opportunities surfaced by the 3 dividend fortresses.
- When you want to look for quality that the market may not be fully pricing in yet, broaden your watchlist with the 7 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com